
Green Brick Partners (GRBK) Posts Weaker Earnings, Is The Stock Fairly Valued?
Green Brick Partners (GRBK) just paired a fresh quarterly dividend on its 5.75% Series A preferred stock with third quarter 2026 results that showed lower revenue and earnings compared with the same period last year.
At a share price of $62.92, Green Brick Partners has given investors a 7 day share price return of 3.69%, although the 90 day share price return is down 10.28% and the 1 year total shareholder return is down 2.34%, even after a 5 year total shareholder return of 152.89% that reflects longer term compounding.
Scan how Green Brick Partners compares with other builders facing similar earnings pressure and capital return decisions by reviewing our hand picked list of solid balance sheet and fundamentals (24 results).
Green Brick Partners now trades close to its recent pullback level, with weaker quarterly earnings already on the table and a fresh preferred dividend announced. Does that set up an early entry or argue for more patience before committing new capital?
Most Popular Narrative: 1% Overvalued
Green Brick Partners closed at $62.92 against a widely followed fair value estimate of $62.00, which leaves the stock framed as slightly overvalued with only a narrow gap between price and narrative value. That small difference puts the focus on how resilient margins and capital allocation choices develop from here.
The main thing that has to go right is that Green Brick Partners converts its land heavy, self development model and growing mortgage capture into sustainably strong margins and returns, despite weaker backlog and higher discounting.
The numbers imply the share price already reflects a fairly valued, bearish view that balances industry leading profitability and institutional support against earnings declines, backlog pressure and mixed valuation signals.
See why 19 investors see Green Brick Partners as 1% overvalued.
Result: Fair Value of $62 (OVERVALUED)
Still, that view could be challenged if the backlog weakens further or if higher land and development spending ties up more cash than expected.
Find out about the key risks to this Green Brick Partners narrative.
Another View On Green Brick Partners Using Earnings Multiples
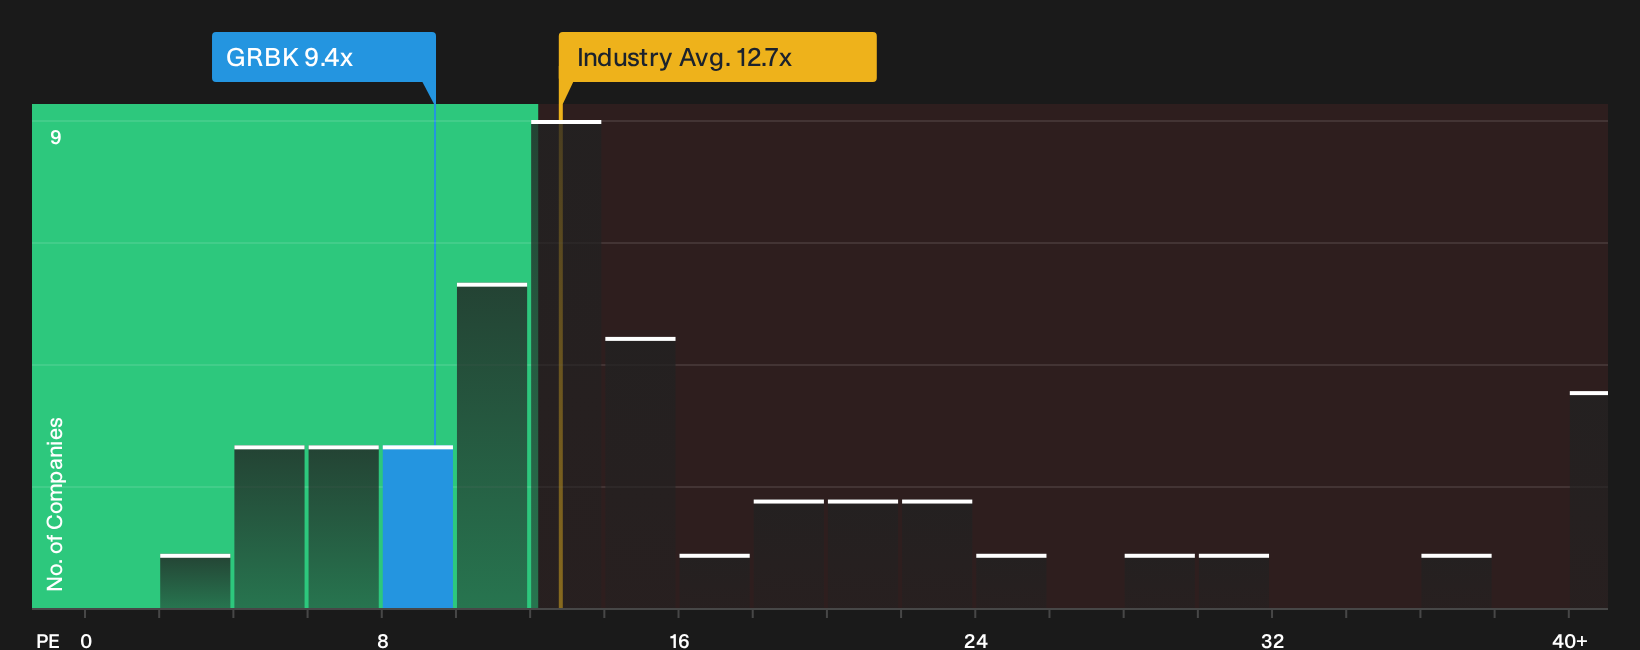
That fair value of $62 comes from a narrative built around future earnings and margins. Step away from that and the current P/E of 9.4x for Green Brick Partners looks cheaper than peers at 17.1x and below a fair ratio of 11.3x, which implies the market may be pricing in extra risk.
If earnings hold near current levels, that sort of discount can either close or widen depending on how investors reassess those risks over time. The key question is whether you see that valuation gap as a cushion against more bad news or a signal to demand an even bigger margin of safety.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around Green Brick Partners is clearly mixed, with solid long term returns sitting alongside fresh concerns about softer earnings and capital deployment. Act quickly, review the full picture for yourself, and weigh both sides of the story through the 2 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Green Brick Partners?
You do not need to stop your research with Green Brick Partners. Use targeted screeners to surface fresh opportunities that fit the kind of portfolio you want to build.
- Target resilient performers with balanced finances by scanning a 32 resilient stocks with low risk scores. This can help you focus on companies with measured risk profiles.
- Hunt for potential bargains by reviewing a 26 high quality undervalued stocks. This filters for stocks combining quality fundamentals with prices that may not fully reflect them.
- Spot underfollowed opportunities early by checking a 19 high quality undiscovered gems. This zeroes in on strong businesses receiving less attention from the market.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com