
Is Earnings Miss Altering The Investment Case For Meritage Homes Stock?
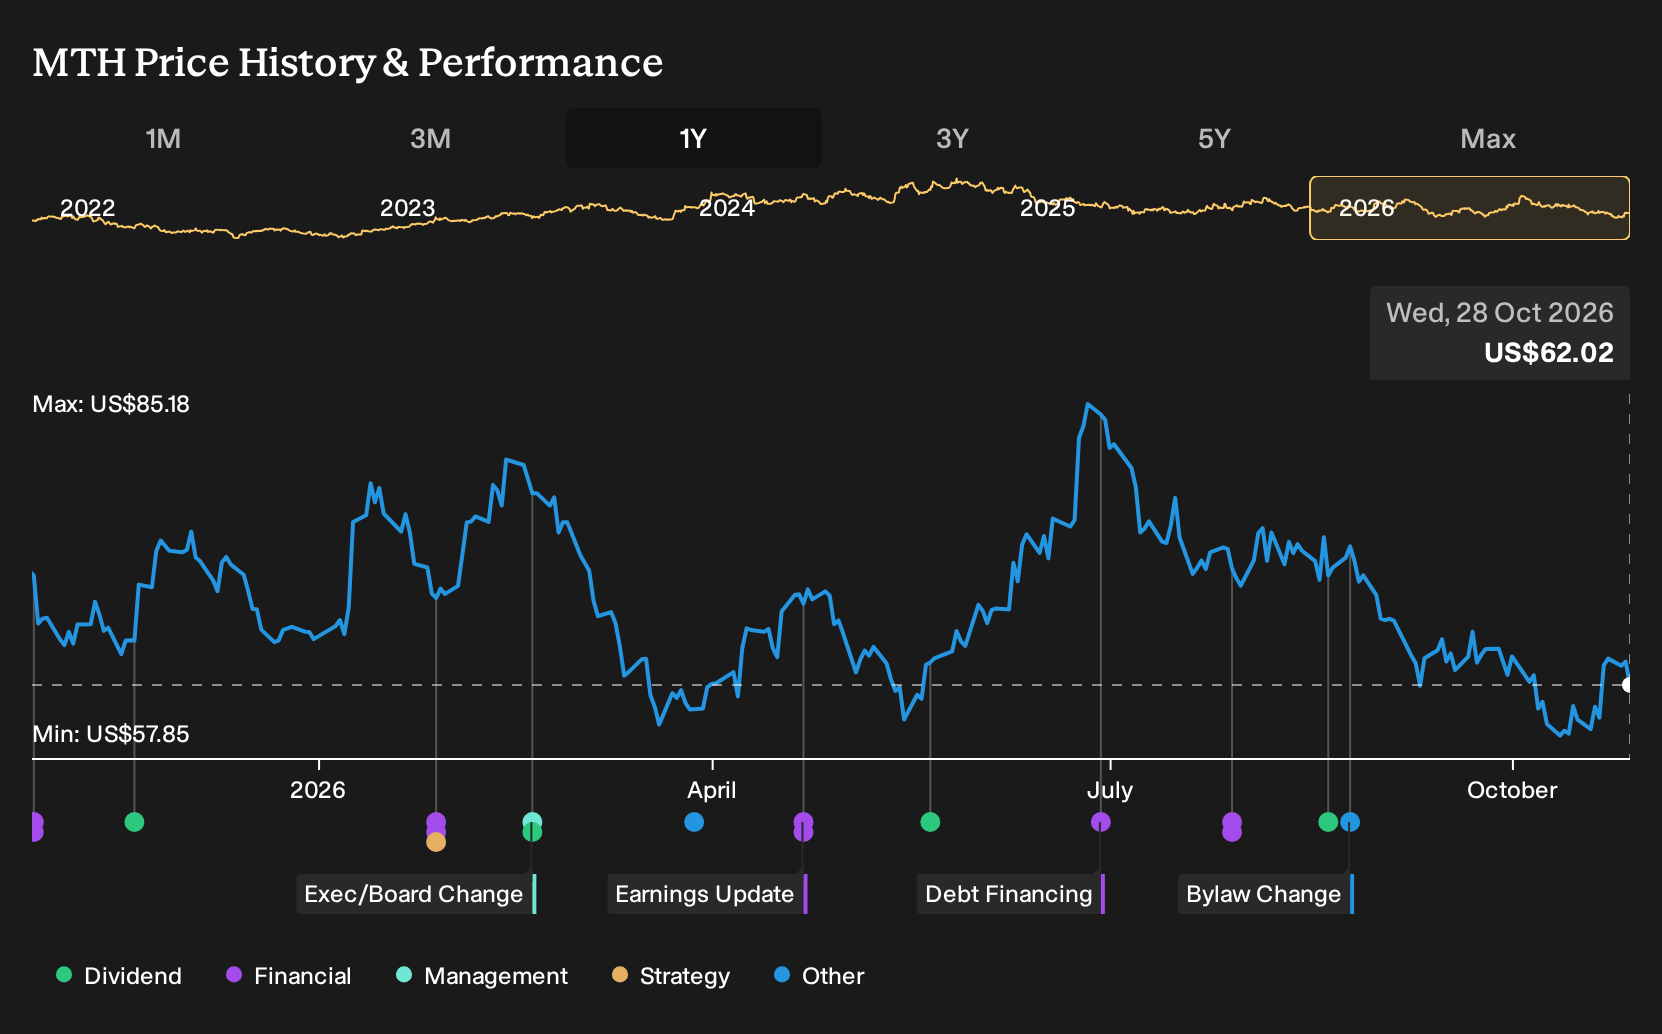
- Meritage Homes reported third quarter 2026 revenue of US$1.17b and net income of US$67.78m, both lower than the prior year, with diluted EPS from continuing operations at US$1.04 versus US$1.39 a year earlier.
- The builder is cutting land spending and emphasizing capital returns after softer home orders, weaker backlog and reduced home closing margins signaled pressure on its core homebuilding operations.
- This article will examine how Meritage Homes' weaker Q3 earnings and softer demand metrics may influence the longer term investment narrative around the business.
Meritage Homes Investment Narrative Recap
For a shareholder in Meritage Homes, the core belief is that its focus on entry level and first move up buyers, quick close spec inventory and cost discipline will translate into steady orders and healthier margins over time. The latest quarter, with revenue at US$1.17b and diluted EPS from continuing operations at US$1.04, highlights that this is not a straight line story.
In the short term, the key catalyst is whether demand and pricing in Meritage Homes’ communities can stabilize enough for margins to stop slipping. The biggest near term risk is that affordability pressure forces heavier incentives, which could keep profit margins under strain and slow any recovery in earnings and cash generation.
The most relevant update here is the third quarter 2026 report, which showed revenue of US$1.17b, net income of US$67.78m and diluted EPS from continuing operations of US$1.04, all below the prior year. That result sat alongside softer home orders, weaker backlog and reduced home closing margins, pointing to pressure on the core building engine.
For you as an investor, that report feeds directly into the existing catalysts and risks. Faster cycle times and backlog conversion can still help Meritage Homes react quickly if demand firms. At the same time, the Q3 numbers underline how exposed the business remains to affordability shocks and the possibility that margin compression, already visible in lower profit margins, lingers longer than hoped.
What The Analyst Framework Implies For Meritage Homes
Analysts sketch a version of Meritage Homes that leans on gradual revenue expansion, modest margin repair and fewer shares in circulation. The assumptions are fairly tight. Forecasts point to revenue growth of 4.7% per year over the next three years and an uplift in profit margins from 6.1% today to 6.8% on that timeframe. On the earnings line, the consensus view looks for net income to move from US$329.3m today to US$422.1m by 2029, with the most optimistic estimate at US$508.5m and the most cautious at US$367.0m. That path asks the business to lift earnings by roughly US$92.8m from the current base while absorbing macro and affordability swings along the way.
Meritage Homes' narrative projects US$6.2b revenue and US$422.1m earnings by 2029. This requires 4.7% yearly revenue growth and roughly US$92.8m earnings increase from US$329.3m today.
Uncover why Meritage Homes' fair value indicates a 21% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
One alternate view focuses on Meritage Homes’ capital returns as a risk. The most cautious analysts were already penciling in 3.6% annual revenue growth and about US$366.8m in earnings by 2029 before this Q3 miss. That group effectively saw today’s price as full. This shows how sharply opinions can diverge. Use this earnings reset as a prompt to compare several narratives, not just the consensus line.
Explore 3 other Meritage Homes fair value estimates, including one that suggests it could be worth just $59.00.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider conducting your own research and forming your own view.
- A great starting point for your Meritage Homes research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Meritage Homes. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Meritage Homes' overall financial health at a glance.
Looking For More Investment Ideas Beyond Meritage Homes?
If Meritage Homes has sharpened your focus on balance sheets, cash generation and valuation, use that same lens across the wider market with the Simply Wall St Screener. It is a straightforward way to filter for stocks that match your risk tolerance, income goals and quality thresholds instead of relying on headlines alone.
- For investors who care most about financial resilience, start with a list of solid balance sheet and fundamentals (24 results) that can handle tougher conditions without stretching the balance sheet.
- If your priority is finding quality at a reasonable price, scan our 26 high quality undervalued stocks that pair stronger fundamentals with valuations that do not look stretched.
- Income focused readers can zero in on potential cash return opportunities through a curated set of 6 dividend fortresses that may suit a yield oriented portfolio.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com