
What Perrigo (PRGO)'s Lowered Earnings Estimates Mean For Shareholders
- Perrigo is expected to report lower earnings and revenue for the quarter ended September 2026 compared with the same period a year earlier, ahead of its November 4 results release.
- The downward revision in consensus EPS estimates may reflect cost, demand, or execution pressures that could matter more to Perrigo’s long-run cash generation than short-term analyst sentiment alone.
- This article examines how Perrigo's investment narrative is being affected by recently lowered earnings estimates ahead of the upcoming quarterly report.
Compare Perrigo’s setup with a curated 26 high quality undervalued stocks that analysts expect to hold up better if earnings pressure spreads across the sector.
Perrigo Investment Narrative Recap
To own Perrigo, you need to believe its self-care portfolio can turn steady consumer demand and private label share gains into healthier margins over time. In the near term, the story is all about execution. Softer earnings for the September 2026 quarter may weigh on confidence but do not automatically change the long-run appeal of store-brand OTC and nutrition.
The key near-term catalyst remains Perrigo’s ability to convert cost savings and portfolio simplification into cleaner, more predictable profitability. The biggest current risk is pressure on volumes and pricing in infant formula and OTC categories. Combined with cost inflation, this could keep the business unprofitable and limit cash available for debt reduction and dividends.
Recent commentary around Project Energize and supply chain reinvention remains highly relevant given the latest earnings expectations. Management has outlined US$150m to US$200m in savings from these efforts. If delivered cleanly, these savings can help offset weaker quarters like the one now anticipated and support reinvestment in core brands and private label relationships.
Portfolio simplification, including the earlier sale of the Dermacosmetics unit, also matters for this setup. A tighter focus on Consumer Self-Care Americas and International leaves Perrigo more exposed to category consumption swings but provides a clearer line of sight on where execution needs to improve. For readers, the question is whether cost actions and contract wins can arrive fast enough to counter the earnings pressure flagged ahead of November 4.
Perrigo Consensus Assumptions and Valuation Setup
Perrigo's current analyst framework leans heavily on earnings repair rather than aggressive top line expansion. Forecasts describe revenue as staying fairly flat, with analysts looking for around US$4.2b of sales and US$73.4m of earnings by 2029. That path assumes a shift from a loss of US$1.8b in earnings today to positive profit over the next few years, as margins move from a loss of 42.9% to a modest 1.8%.
Perrigo's narrative projects US$4.2b revenue and US$73.4m earnings by 2029. This implies fairly flat yearly revenue performance and an earnings increase of about US$1.9b from a loss of US$1.8b today.
That swing in profitability underpins the current valuation debate. Analysts are effectively saying the stock needs to support a P/E of 41.9x on those 2029 earnings, compared with a current multiple that screens as unhelpful because today’s result is a loss. For context, the US Pharmaceuticals industry is referenced at 14.8x; the Perrigo story therefore leans on confidence that the margin rebuild and cost programs like Project Energize can support a richer multiple than the sector average.
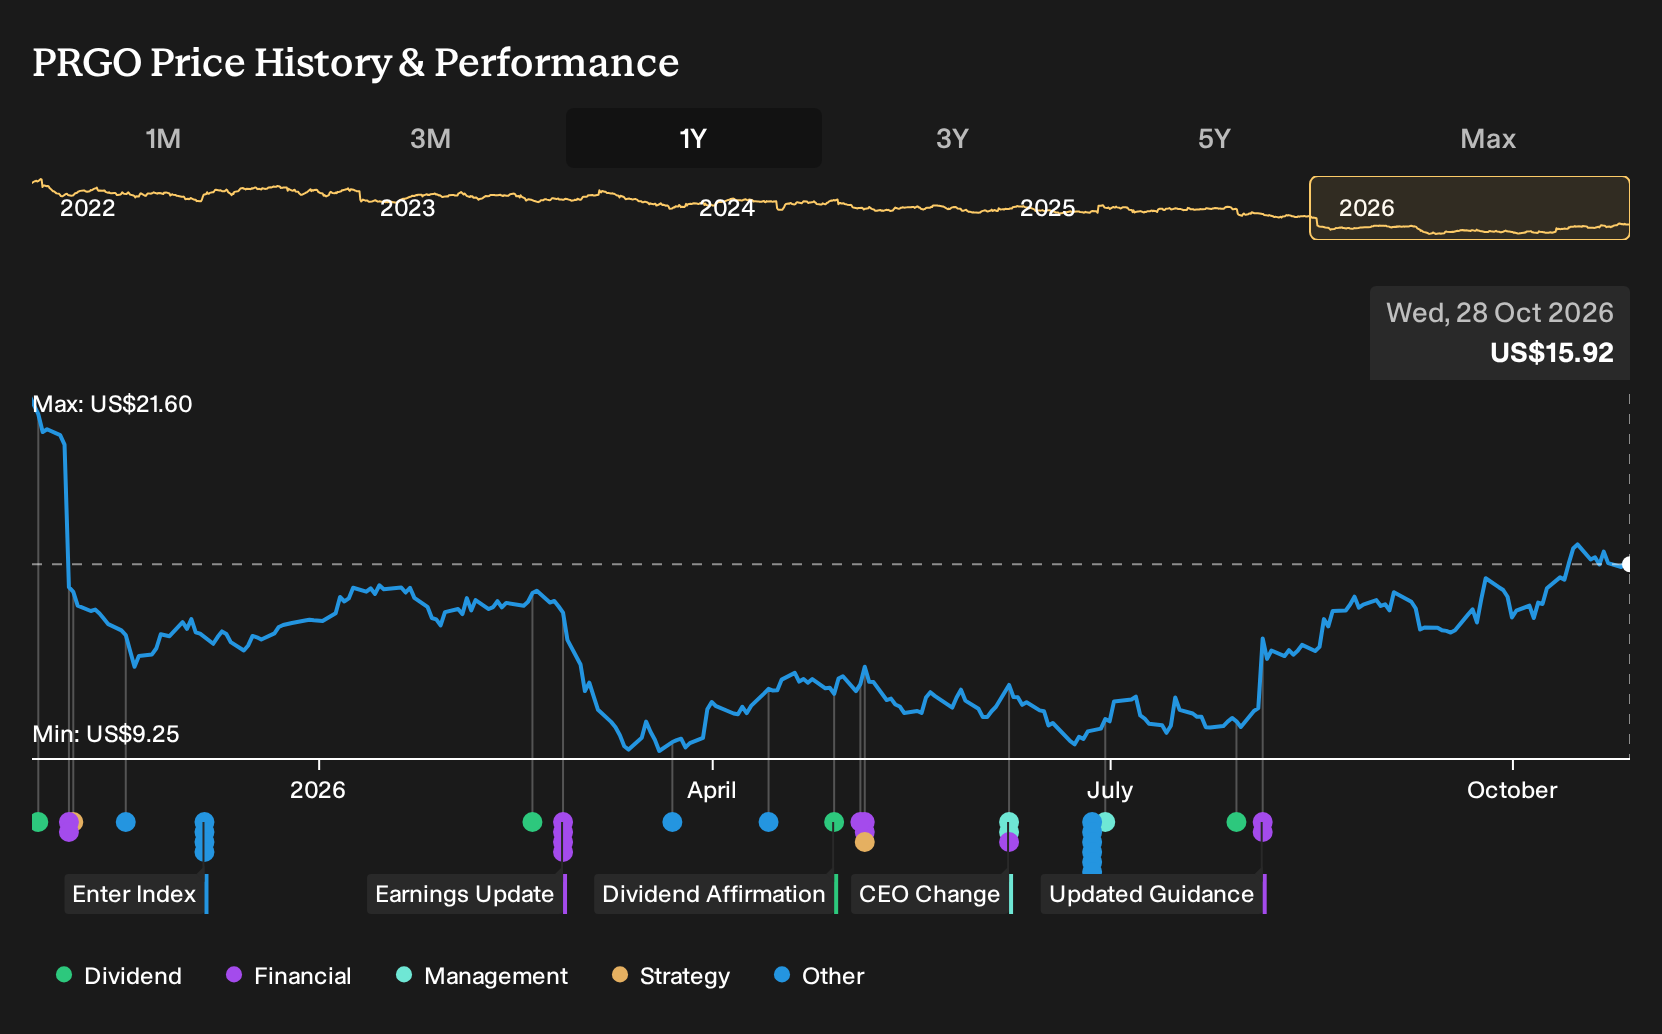
Price targets cluster around a US$16.50 consensus, with the most optimistic view at US$20.00 and the most cautious at US$14.00. With the shares recently trading near US$10.46, that spread highlights how differently the market is weighing risks like infant formula volatility, private label pricing power, and supply chain reliability. For readers tracking Perrigo, the key task is to decide whether flat revenue tied to store-brand self care plus a return to positive earnings justifies a future valuation closer to the analyst playbook or something more conservative.
Uncover how Perrigo's fair value indicates a 4% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One alternative view focuses on Perrigo’s governance and legal overhang around Infant Formula. That camp was already cautious before this earnings reset, with the lowest analysts still modeling about US$4.1b of revenue and roughly US$132.5m in earnings by 2029. Their US$14.00 target reflects a far more pessimistic story that you may want to compare with your own assumptions.
Explore 3 other Perrigo fair value estimates, including one that suggests it could be worth just $16.50.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Perrigo research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Perrigo. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Perrigo's overall financial health at a glance.
Looking For More Investment Ideas Beyond Perrigo?
If Perrigo has sharpened your view on earnings risk and valuation, it can help to widen the lens and compare it with other opportunities that fit different risk and income profiles.
- For readers who want potential upside with strict quality filters, start with a curated set of 19 high quality undiscovered gems that pair stronger fundamentals with cleaner balance sheets.
- If capital preservation comes first for you, stress test your ideas against a 32 resilient stocks with low risk scores that focuses on businesses with more resilient risk scores.
- Income focused investors may prefer to anchor their watchlist around a handful of 6 dividend fortresses that combine higher yields with sturdier cash generation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com