
Is Aptamer Diagnostics Exposure Altering The Investment Case For Kaneka (TSE:4118)?
- Kaneka Corporation has recently been cited as a key participant in the global aptamer diagnostic kits market, which is projected in third-party industry research to reach about US$3.97b by 2030, supported by broader healthcare spending and technology progress.
- This spotlight on Kaneka in a fast-expanding niche of diagnostic tools highlights how its biotechnology capabilities intersect with demand for more precise, AI-enabled point-of-care testing.
- We will now look at how Kaneka's role in aptamer diagnostic kits could influence the investment narrative investors use to assess it.
Scan how Kaneka's aptamer focus compares with other potential beneficiaries of AI-driven diagnostics by reviewing the handpicked 10 healthcare AI stocks.
What Is Kaneka's Investment Narrative?
The big picture for a Kaneka shareholder is a diversified chemicals and materials group that is trying to build higher margin health care and nutrition lines on top of a heavy, capital intensive base. Earnings growth over the past year of 58.2% and improving net profit margins to 4.3% give that story some credibility, although one off gains of ¥12.0b complicate the read through. The recent aptamer diagnostic kits mention reinforces that the health care solutions unit matters for the narrative, but it does not suddenly rewrite near term drivers that still hinge on execution in core materials and nutrition.
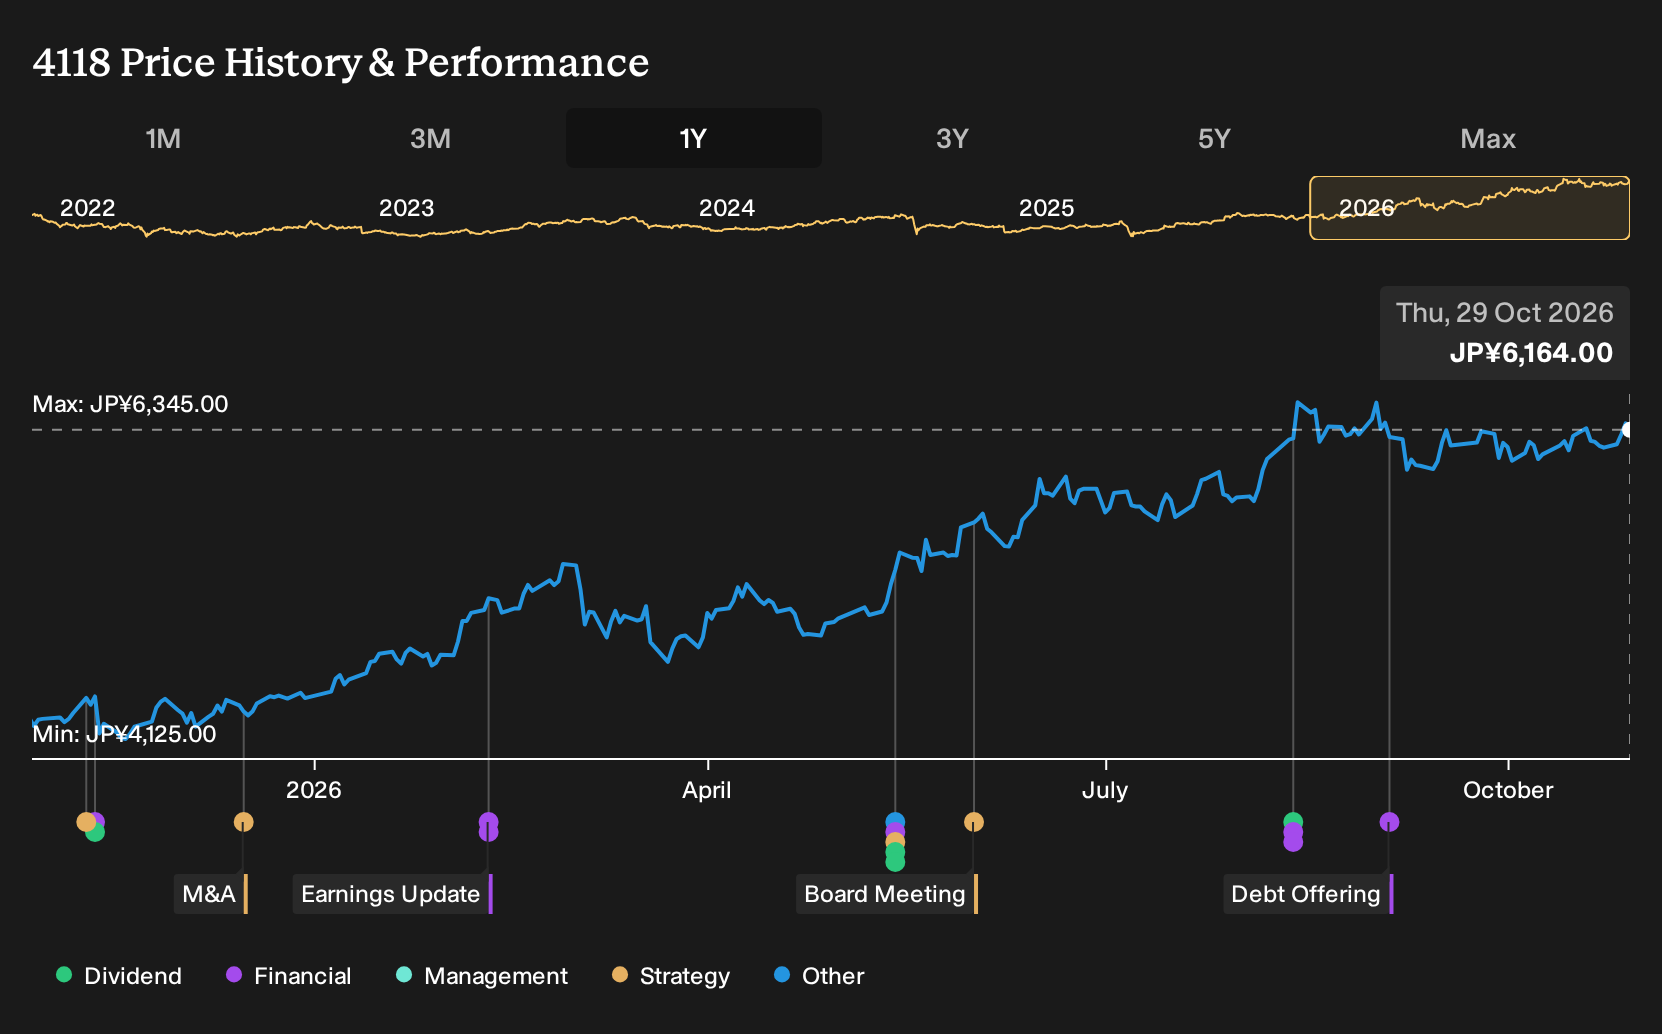
In the short term, you are weighing solid recent share returns and a P/E of 10.4x against forecasts that point to declining earnings over the next three years and slower revenue growth than the wider Japanese market. The aptamer news supports the idea that Kaneka is present in a growing diagnostic niche, yet it also sharpens the question of whether cash flows can comfortably support a 3.41% dividend when funding still leans on higher risk borrowing.
Yet the more uncomfortable part of the Kaneka story sits where those earnings forecasts, one off gains, and board structure all intersect...
There's only one way to know the right time to buy, sell or hold Kaneka. Head to Simply Wall St's company report for the latest analysis of Kaneka's Fair Value.
Exploring Other Perspectives
The Simply Wall St Community currently shows two fair value views for Kaneka, clustered tightly between ¥5,541.67 and ¥5,815.67, which indicates a clear gap in opinions. Those figures also predate the aptamer diagnostic kits spotlight and the projected US$3.97b market, so a broader set of updated perspectives could reshape how you frame Kaneka’s potential.
Explore another Kaneka fair value estimate, including one that suggests it could be worth as much as ¥5816.
Reach Your Own Conclusion
Don't just follow the ticker, dig into the data and build a conviction that's truly your own.
- A great starting point for your Kaneka research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Kaneka. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Kaneka's overall financial health at a glance.
Looking For More Ideas Beyond Kaneka?
If Kaneka has sharpened your curiosity, it can help to widen the search and see how other businesses stack up on income potential, balance sheet strength, and risk.
- If you want yield plus resilience, scan income plays that aim to combine high payouts with staying power through the 29 dividend fortresses.
- If capital preservation matters most to you, focus on sturdier balance sheets and steadier fundamentals using the 25 resilient stocks with low risk scores.
- If you are hunting for businesses that have strong fundamentals but fly under most radars, widen your watchlist through the 72 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com