
China National Building Material (SEHK:3323) Q3 Earnings Revive Profit But Pressure Lingers
China National Building Material went into this Q3 2026 earnings print with its Hong Kong shares under pressure, down around 24% over three months and closing at HK$2.845 on 29 October. The stock trades on a deep discount story. The latest quarter delivered a sharp reset in that narrative. Revenue reached C¥48,502.2m, and the headline surprise was a return to profit, with net income of C¥101.2m after a string of quarterly losses. The market reaction has been muted so far, which leaves a clear gap between the one day price move and the shift in the income statement.
Love the return to profit at China National Building Material but wary of owning a deep discount story on its own? Compare this setup against our 189 high quality undervalued stocks to see how other companies with stronger fundamentals line up.
Q3 2026 Earnings Summary
- Revenue (Q3 2026 vs Q3 2025): C¥48,502.2m vs. C¥50,163.1m (decline of 3.3%)
- Net Income (Excl. Extra Items, Q3 2026 vs Q3 2025): C¥101.2m profit vs. C¥1,599.4m profit (decline of 93.7%)
- Basic EPS (Q3 2026 vs Q3 2025): C¥0.0134 vs. C¥0.2106 (decline of 93.6%)
- Trailing 12-Month Net Income (Excl. Extra Items, to Q3 2026 vs to Q3 2025): C¥7,433.2m loss vs. C¥6,031.3m profit (very large swing from profit to loss)
Losses widened even as Q3 revenue climbed. Ask Charlie what makes China National Building Material look so cheap.
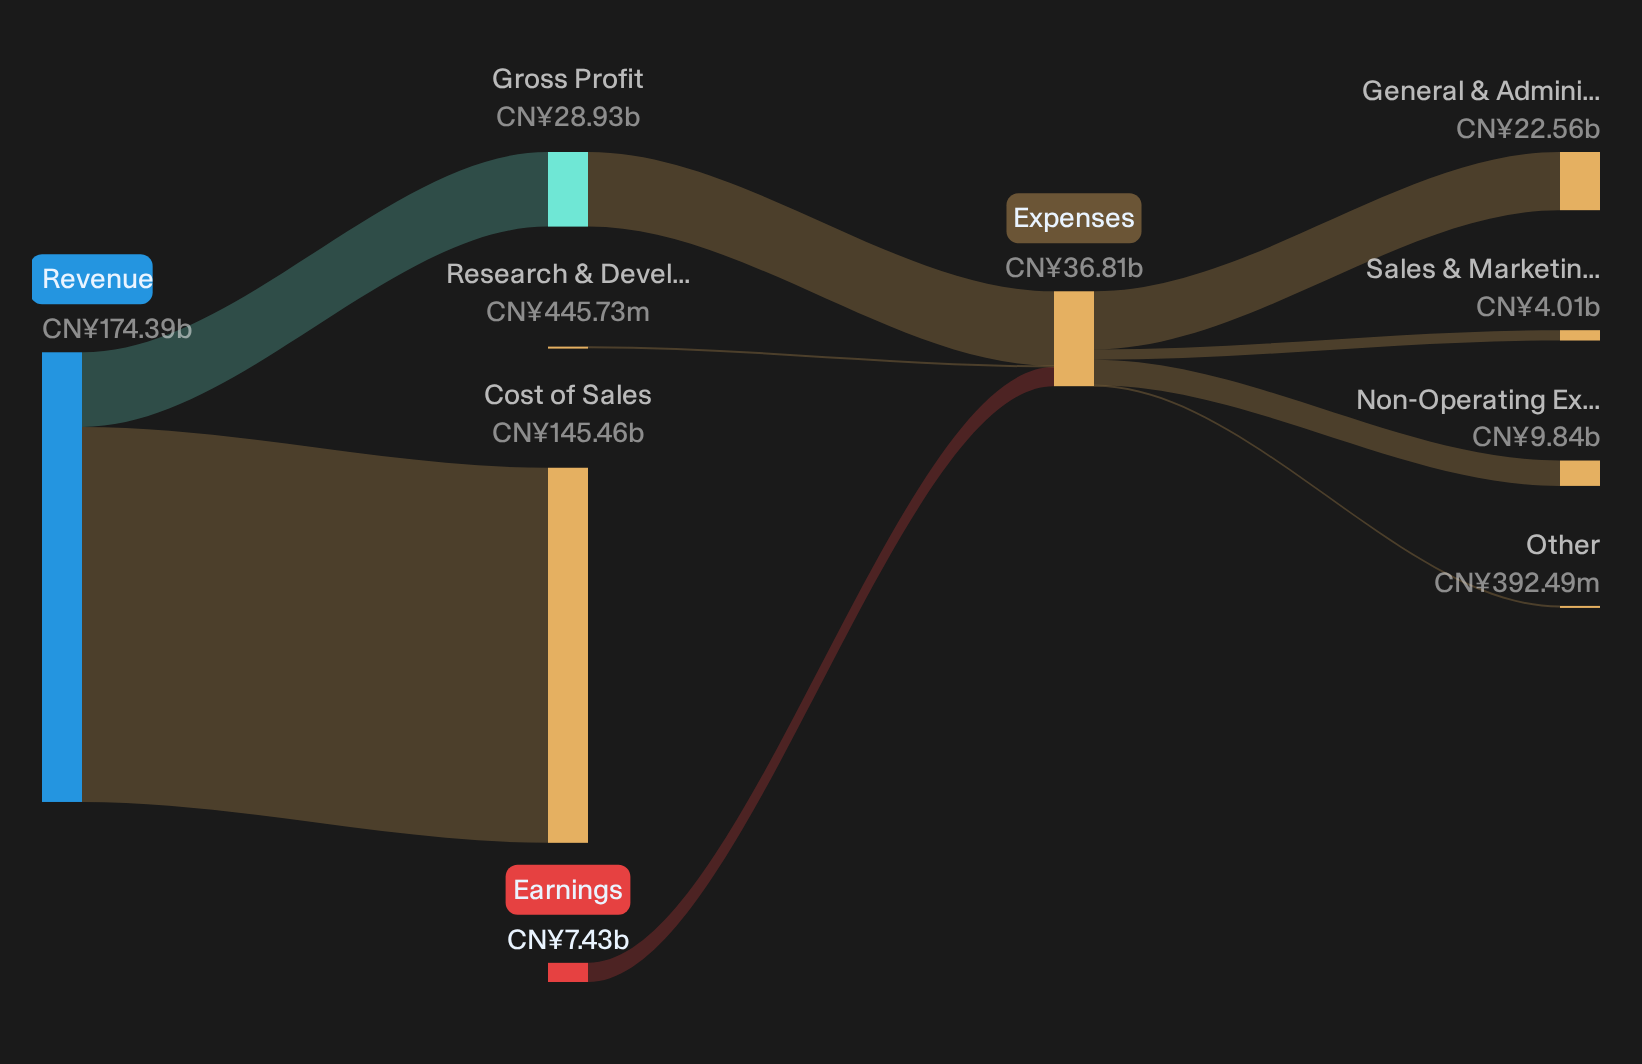
China National Building Material: Testing The Bullish Story
For anyone leaning optimistic on China National Building Material, the simple fact is this. The group moved from a trailing loss of C¥7,433.2m to a Q3 profit of C¥101.2m. Even though that figure is much smaller than a year ago, it shows the business can still generate black ink. Revenue at C¥48,502.2m also stayed close to last year’s level. For a diversified materials group exposed to construction cycles, that mix of stabilising sales and a return to profit offers some support to a cautiously positive view.
Bear Case Check: Profit Reset, Earnings Power Questioned
On the risk side, the bears have plenty to point to. Net income excluding extra items fell 93.7% year on year, and basic EPS dropped in line with that hit. Over the past twelve months the group swung from a C¥6,031.3m profit to a C¥7,433.2m loss. Share performance echoes that pressure, with the stock down about 24% over three months. For a business tied to construction and new materials, the latest numbers keep the debate focused on earnings resilience rather than recovery.
After such a sharp drop in earnings power and with China National Building Material carrying meaningful interest and dividend commitments, it is worth asking whether this is just a temporary squeeze or a deeper structural issue. Review the full risk analysis for China National Building Material which shows 2 important warning signsHunt For Mispriced Earnings Power
China National Building Material recently showed that improving earnings and a steady share price can occur together. The real opportunity is identifying stocks that could be undervalued before that potential becomes widely recognized.
- Company 1 - 16% below our estimate - builds electrical and communications systems for hyperscale data centers as project backlogs and working capital demands grow.
- Company 2 - 50% below our estimate - focuses on higher margin gear and direct channels while an efficiency program aims to lift profitability in newer mobility categories.
- Company 3 - 23% below our estimate - sells AI centric networking and data center infrastructure as a major acquisition integration becomes critical for recurring revenue and margin goals.
That is three of the list. See the full list of 189 companies trading below our fair value estimates →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com