
Wingstop (WING) Could Be 26% Below Fair Value As Earnings Reset The Story
Wingstop (WING) is back in focus after its third quarter on October 28, combining three signals investors watch closely. Earnings per share topped expectations, revenue missed, and guidance pointed to a 6.5% to 7% drop in domestic same store sales.
The third quarter update has reset expectations but also jolted interest in Wingstop. The 1 day share price return of 12.18% and 30 day share price return of 27.57% around the results contrast sharply with a year to date share price decline of 46.05%, while the 1 year total shareholder return is down 35.22%. This leaves recent momentum strong but set against weak longer term performance as investors reassess earnings resilience and the same store sales reset.
Scan how other consumer-facing stocks with recent share price resets and earnings surprises compare with Wingstop using our curated list of 26 high quality undervalued stocks.
Bulls see Wingstop’s earnings beat and restaurant expansion as the story, while bears point to falling same store sales and weak long term returns. Which side do today’s valuation markers lean toward next?
Most Popular Narrative: 26% Undervalued
Wingstop’s most followed narrative pegs fair value near $188 against a last close of $138.57, which puts today’s price at a clear discount and turns the spotlight onto what could drive that gap to close.
The current global development pipeline of more than 2,200 committed restaurants, alongside 15% to 16% unit growth guidance and domestic AUVs around US$2 million on roughly US$580,000 build costs, points to continued mix shift toward royalty and franchise fee income. This can support growth in high margin revenue and earnings even when domestic traffic is under pressure.
See why 28 investors see Wingstop as 26% undervalued.
Result: Fair Value of $187.92 (UNDERVALUED)
Still, the narrative around Wingstop can change quickly if domestic same store sales weakness persists or if rapid expansion results in newer restaurants delivering softer returns.
Find out about the key risks to this Wingstop narrative.
Another View: Multiples Paint A Richer Wingstop Picture
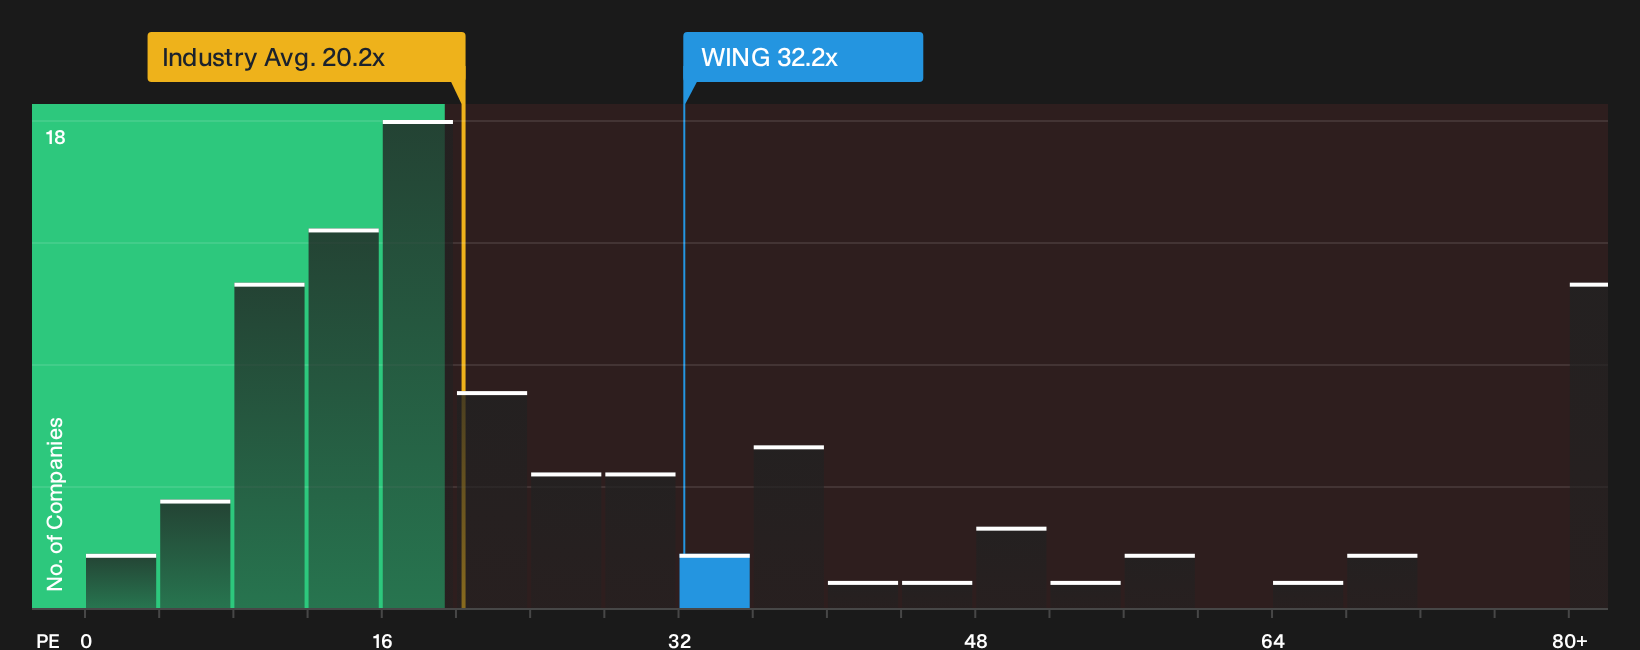
That $188 fair value mark and 26% discount story leans on future cash flows. The snapshot using today's earnings tells something different. Wingstop trades on a P/E of 32.2x, well above the US Hospitality industry at 20.2x and its own fair ratio of 21.8x, which signals less margin for error if earnings or sentiment soften.
For investors weighing these conflicting signals, the question is simple: does the earnings and sentiment gap close upward toward the cash flow view or downward toward that fair ratio the market could move toward next, and how patient are you willing to be while that plays out?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Wingstop do not have to leave you on the fence, especially when the story contains both pressure points and bright spots. Act while the numbers are fresh and weigh both sides for yourself by starting with the 2 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Wingstop?
Do not stop your research with Wingstop alone. Broader opportunity often sits just one strong screener away, where fresh ideas line up with the risk profile you actually want.
- Target steady cash generators and use the 6 dividend fortresses to focus on companies that prioritize regular income.
- Hunt for resilient balance sheets by running the list of solid balance sheet and fundamentals (24 results) so you can focus on financially stronger businesses.
- Zero in on mispriced potential with the 19 high quality undiscovered gems and avoid missing businesses the broader market has not fully noticed yet.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com