
Is Buckle (BKE) Below Fair Value Based On Future Cash Flow?
Buckle has delivered a strong share price gain over the past three years, which puts fresh attention on what investors are really paying for its cash flows at around US$45 a share. With a Discounted Cash Flow (DCF) view available, the key issue is how that long term cash generation stacks up against where the stock trades today.
- Over the past three years the stock has returned 75.6%, which puts meaningful weight on whether that share price now lines up with the cash the business can produce over time.
- Buckle relies heavily on converting retail profits into free cash flow, so the durability of that cash conversion may support or limit how much value investors ascribe to the shares.
- If you'd rather focus on earnings, this one's for you. See why Buckle's 10.4x P/E tells a different valuation story.
The stock's next move may depend on whether Buckle's current market price is adequately supported by the intrinsic value suggested by its cash flows.
If you are weighing Buckle's recent 3 year gain against what you are paying for its cash flows, a focused stock screen of 26 high quality undervalued stocks can provide another starting point for your research.
Is Buckle Still Cheap on Cash Flow?
The Discounted Cash Flow (DCF) approach here focuses on the cash Buckle can reasonably generate and return to shareholders over time. Latest twelve month free cash flow sits at about $204.9 million, and the projections in the 2 Stage Free Cash Flow to Equity model build in relatively modest growth in those yearly cash flows rather than big step changes.
Those steady cash assumptions, when discounted back, result in an estimated intrinsic value that the DCF model indicates is substantially above the current share price of $45.46. For anyone tracking Buckle, the key question is whether that pattern of mid-range free cash flow and measured growth is a fair reflection of how the retailer will keep converting its store profits into cash over the next decade. Find out what Buckle could be worth using our Discounted Cash Flow (DCF) estimate.
The Buckle Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the Buckle valuation puzzle leaves off by clarifying which expectations for future growth, margins and earnings would need to occur for the share price to sit materially above or below where it trades today. Each Narrative on Buckle is set up as a thesis about fair value that can be revisited over time so you can see how the underlying business performance tracks against the original idea on the Community page.
One of the top community narratives on Buckle: roughly fairly valued
"The main factor that has to go right is that merchandise margins and store productivity remain high enough to cover rising occupancy and SG&A spending..."
Discover why this Narrative puts Buckle at roughly fairly valued.
One more Buckle factor that could matter for you
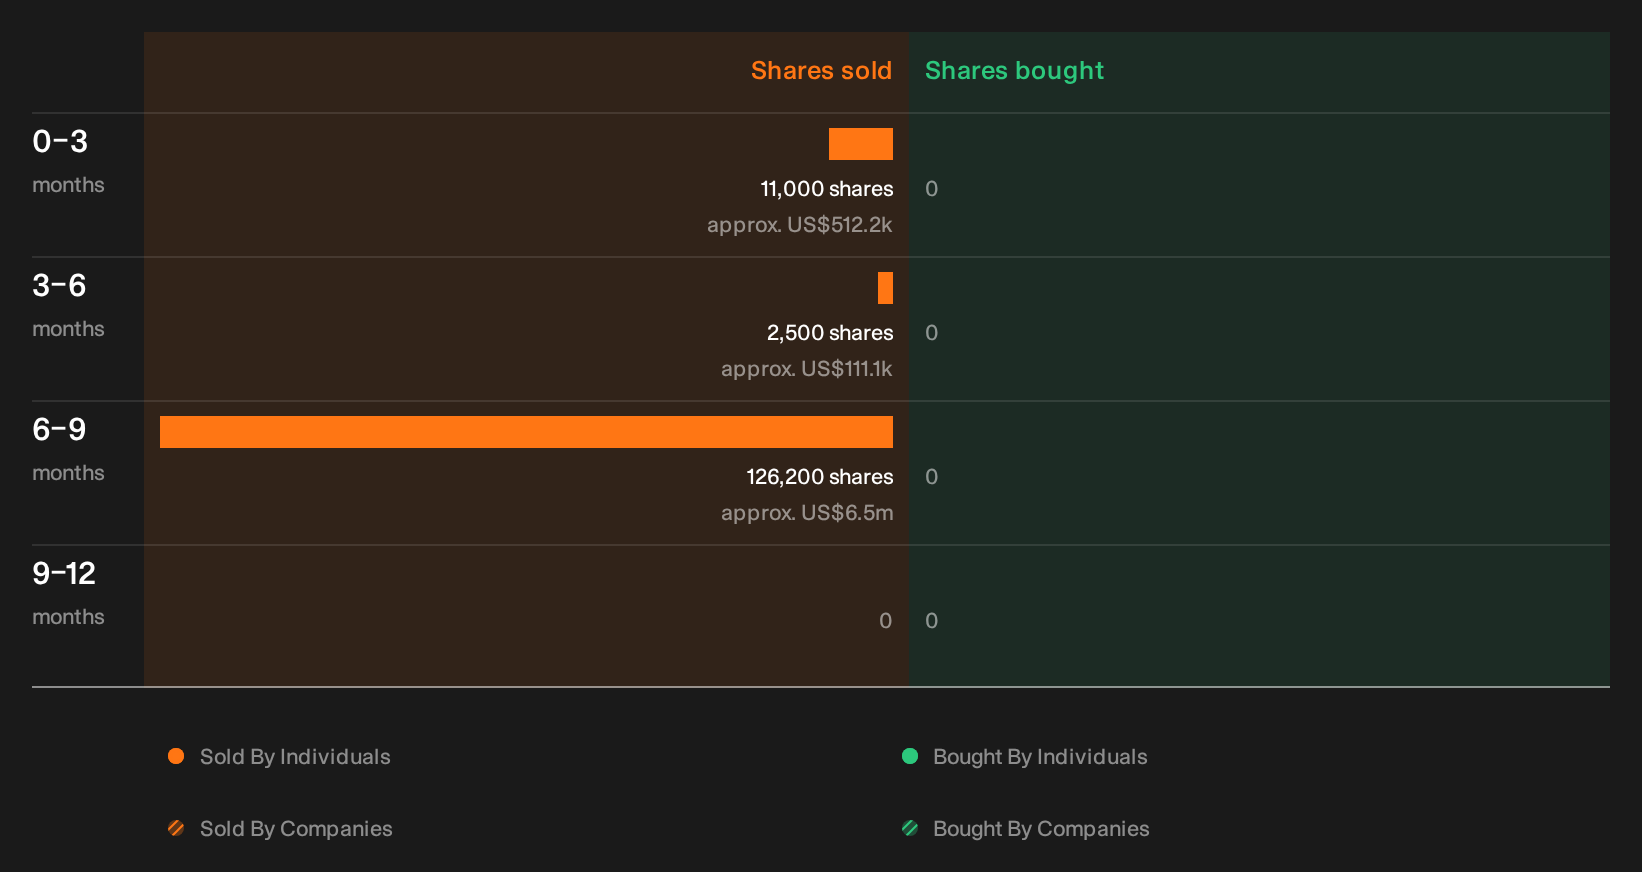
Valuation models tell one story about Buckle, but recent trading activity from people inside the business can tell a different one, and the specific sellers, volumes and possible read throughs are waiting for you to review. See the recent insider selling flagged for Buckle.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com