
Compass (COMP) Stock Trades At A Premium To Earnings
Compass has delivered a very large 3 year share price gain, and that kind of move naturally raises a simple question for investors who focus on earnings. Is the current US$9.17 price being supported by what the business is actually making today and expected to earn over time.
- The stock is up about 3.8x over the past 3 years, which puts real pressure on the numbers to show that this rise is grounded in Compass' earnings power.
- Recent legal disputes over listing rules and data sharing may affect how Compass sources deals and converts its brokerage model into earnings, which can matter for how sustainable its current profit base looks.
- The analysts covering Compass have run their own numbers. See what analysts think Compass's shares could be worth.
The issue now is whether Compass' current share price is adequately supported by its earnings when judged against the Fair Ratio benchmark.
If you are weighing Compass against other opportunities tied to housing and real estate trends, it can help to line it up beside 43 power grid technology and infrastructure stocks.
Is Compass Getting Expensive on Earnings?
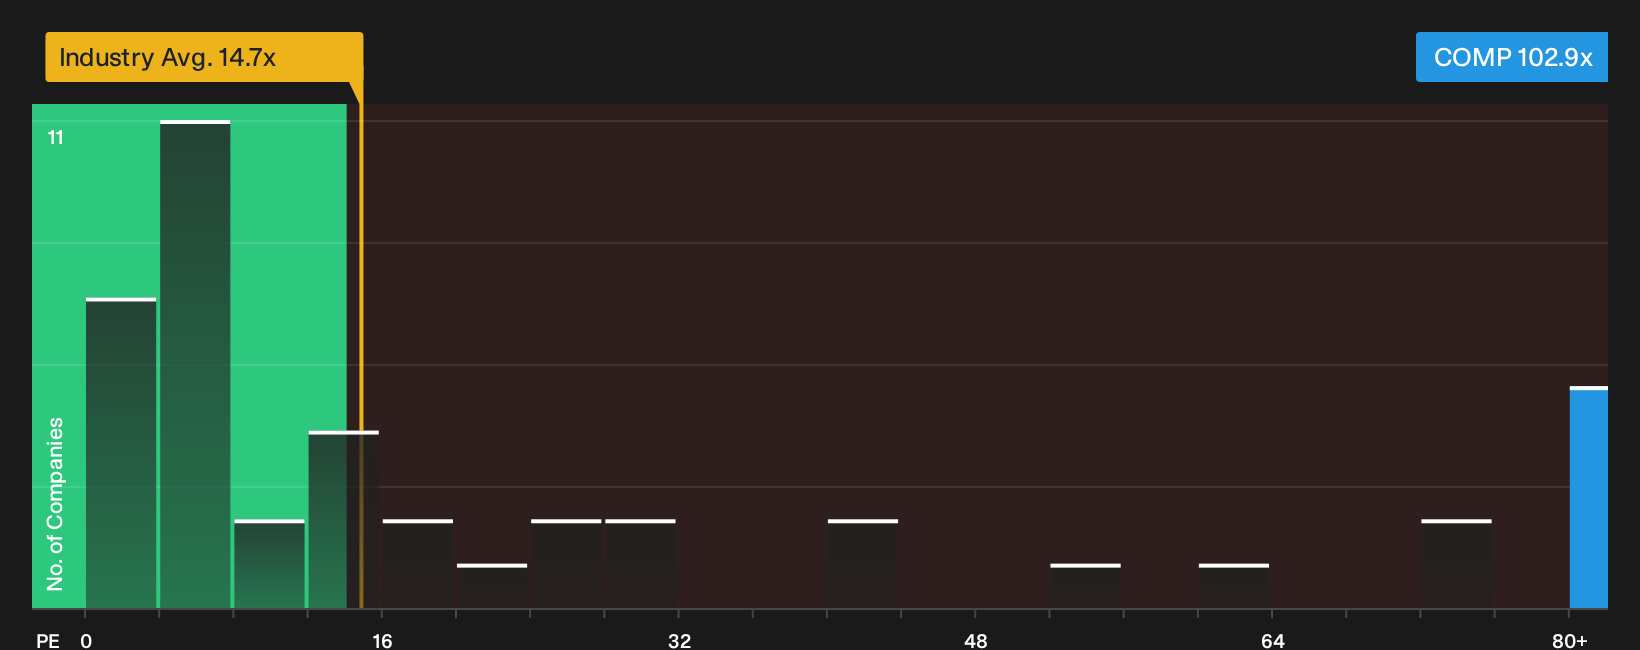
A P/E lens suits Compass because earnings now matter more as investors look past the initial growth story and toward ongoing profitability. On this measure, the stock trades on a P/E of 102.9x, while the wider Real Estate group sits nearer 14.7x. Against a peer average of 55.4x, Compass changes hands at a clear premium.
Recent legal disputes over listing rules have not stopped the valuation from stretching. On the Fair Ratio benchmark, which reflects what the P/E might look like once growth prospects, profitability profile, size and risk are blended together, Compass screens as overvalued because its current multiple sits above that reference point. That leaves the current share price heavily reliant on the market staying comfortable with paying far more per dollar of earnings than is typical for both the sector and comparable brokers. Explore the numbers behind Compass's P/E valuation.
The Compass Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the Compass valuation puzzle leaves off by spelling out which paths for future growth, profitability and earnings would need to play out for the shares to look meaningfully higher or lower than today’s price. Each narrative links its number to a specific view on how Compass' expansion, margin profile and risks might evolve, giving you a reference point you can revisit as fresh information arrives.
One of the top community narratives on Compass: 36% undervalued
"Expansion and increasing attach rates of high margin, adjacent services is elevating wallet share per transaction and raising overall adjusted EBITDA margins..."
Discover why this Narrative puts Compass at 36% undervalued.
One unresolved question on Compass still matters
Valuation only tells part of the story for Compass, since recent research flags specific business concerns that could change how you weigh everything you have just read. Take a closer look at 3 warning signs (2 major) before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com