
CNX Resources (CNX) Stock Still Looks Like A Bargain Despite Its 163% Run
CNX Resources has delivered a strong run in recent years, which puts the spotlight squarely on what investors are paying for its earnings today. With the share price now reflecting a long stretch of gains, the question is how closely that market value lines up with what the business is generating in profit.
- Over the past 5 years CNX Resources has returned 162.8%, so a lot now hinges on whether that performance is backed by sustainable earnings power.
- The company’s investment case leans heavily on how efficiently it can turn its natural gas assets into recurring profit, since production discipline, operating costs and capital spending all feed directly into the earnings stream investors are valuing.
- Your read on CNX Resources is one view; the desks covering it have another. See what analysts think CNX Resources's shares could be worth.
The issue now is whether CNX Resources’ current share price can be justified by the level and quality of the earnings the business is producing.
If you are weighing CNX Resources on its earnings alone, it can help to compare that thinking with a broader set of companies filtered by 26 high quality undervalued stocks.
Is CNX Resources Still Cheap on Earnings?
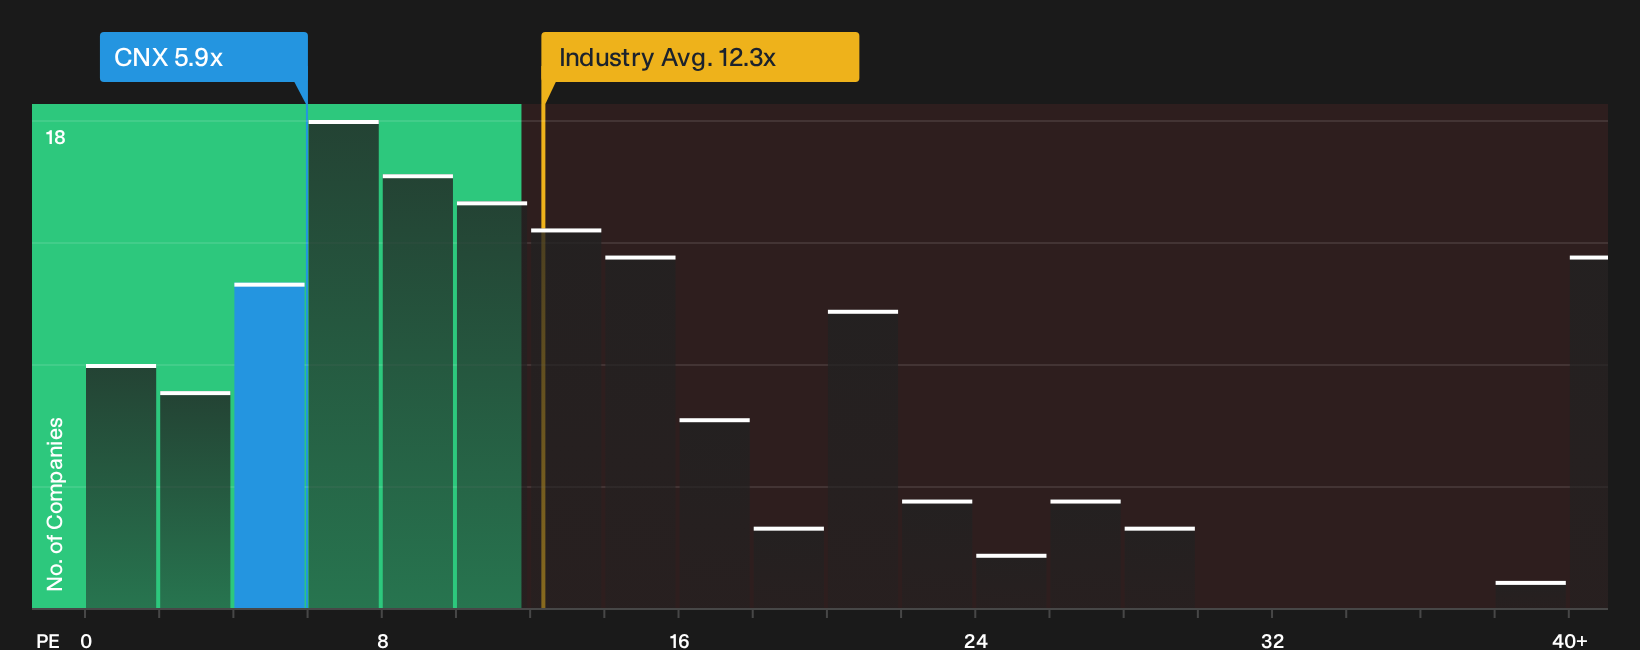
P/E fits CNX Resources because earnings are a key yardstick for a producer that leans heavily on cash generation from existing reserves. On that measure, the stock trades on a P/E of 5.9x, which is well below the Oil and Gas sector average of 12.3x and far under the wider peer group at 36.9x. That kind of gap means the market is putting a much lower price on each dollar of CNX Resources’ profit than on many comparable producers.
The Fair Ratio for CNX Resources, which reflects what investors might typically pay given its returns, scale, industry and risk profile, sits above the current 5.9x P/E. That places the shares in undervalued territory on this framework, although the headline discount still needs to be weighed against the stability and quality of the company’s earnings stream. Explore the numbers behind CNX Resources's P/E valuation.
The CNX Resources Narrative: What Would Justify Today's Price?
Narratives for CNX Resources pick up where the simple P/E comparison leaves off by spelling out which paths for future growth, margins and earnings would need to play out for the stock to be worth materially more or less than it is today on Simply Wall St's Community page. Instead of a single output from a ratio or model, they unpack the future that figure leans on so you can watch in real time whether the business is tracking that path or drifting away from it.
CNX Resources attracts one camp that sees more upside in the current set up, and another that views it as closer to fairly priced.
Bull case: 15% undervalued
"The numbers imply the share price embeds limited credit for CNX Resources' planned roughly $90 million annual low carbon cash flows..."
Discover why this Narrative puts CNX Resources at 15% undervalued.
Bear case: roughly fairly valued
"CNX Resources' practice of adding longer dated hedges, already covering over 60% of 2027 volumes at a weighted average NYMEX price around US$4..."
Explore why this Narrative puts CNX Resources at roughly fairly valued.
Before making a move on CNX Resources, one more factor needs attention
Numbers tell only part of the story for CNX Resources, because the people setting priorities, allocating capital and rewarding themselves can tilt outcomes in ways the headline valuation never shows. See who runs CNX Resources and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com