
Forestar Group (FOR) Could Be 24% Undervalued After Chairman Retirement News
Forestar Group (FOR) just announced a leadership change, with Executive Chairman Donald J. Tomnitz set to retire on October 31, 2026, and CEO Anthony W. Oxley will take on the combined role of Executive Chairman and CEO.
Forestar Group shares trade at US$25.92 after a 1 day share price return that declined 1.29%, with a 7 day share price return of 2.78%, a 90 day share price return that fell 9.91%, a 1 year total shareholder return that declined 4.25%, and a 5 year total shareholder return that improved 24.98%. This suggests shorter term momentum has cooled compared with longer term results as investors weigh this leadership transition against the broader business track record.
Scan how other real estate and development players are pricing leadership and governance shifts by reviewing our curated list of 32 resilient stocks with low risk scores alongside Forestar Group.
Forestar Group trades below analyst targets while also screening as slightly above intrinsic value estimates. Is that a fair discount for a maturing lot developer under a combined Executive Chairman and CEO, or an overly cautious market reset ahead of leadership change?
Most Popular Narrative: 24% Undervalued
Forestar Group's most followed narrative pegs fair value at $34, well above the last close of $25.92. The current price therefore assumes a sizeable discount to that thesis.
The main thing that has to go right is that Forestar Group converts its large contracted lot backlog and planned US$1.4b of land and development spending into consistently profitable lot sales, despite recent volume declines, margin pressure, and negative free cash flow.
See why 12 investors see Forestar Group as 24% undervalued.
Result: Fair Value of $34 (UNDERVALUED)
Still, shrinking margins and declining returns on invested capital could undermine the Forestar Group backlog thesis if lot volumes remain under pressure for a longer period.
Find out about the key risks to this Forestar Group narrative.
Another View: Forestar Group Through A Cash Flow Lens
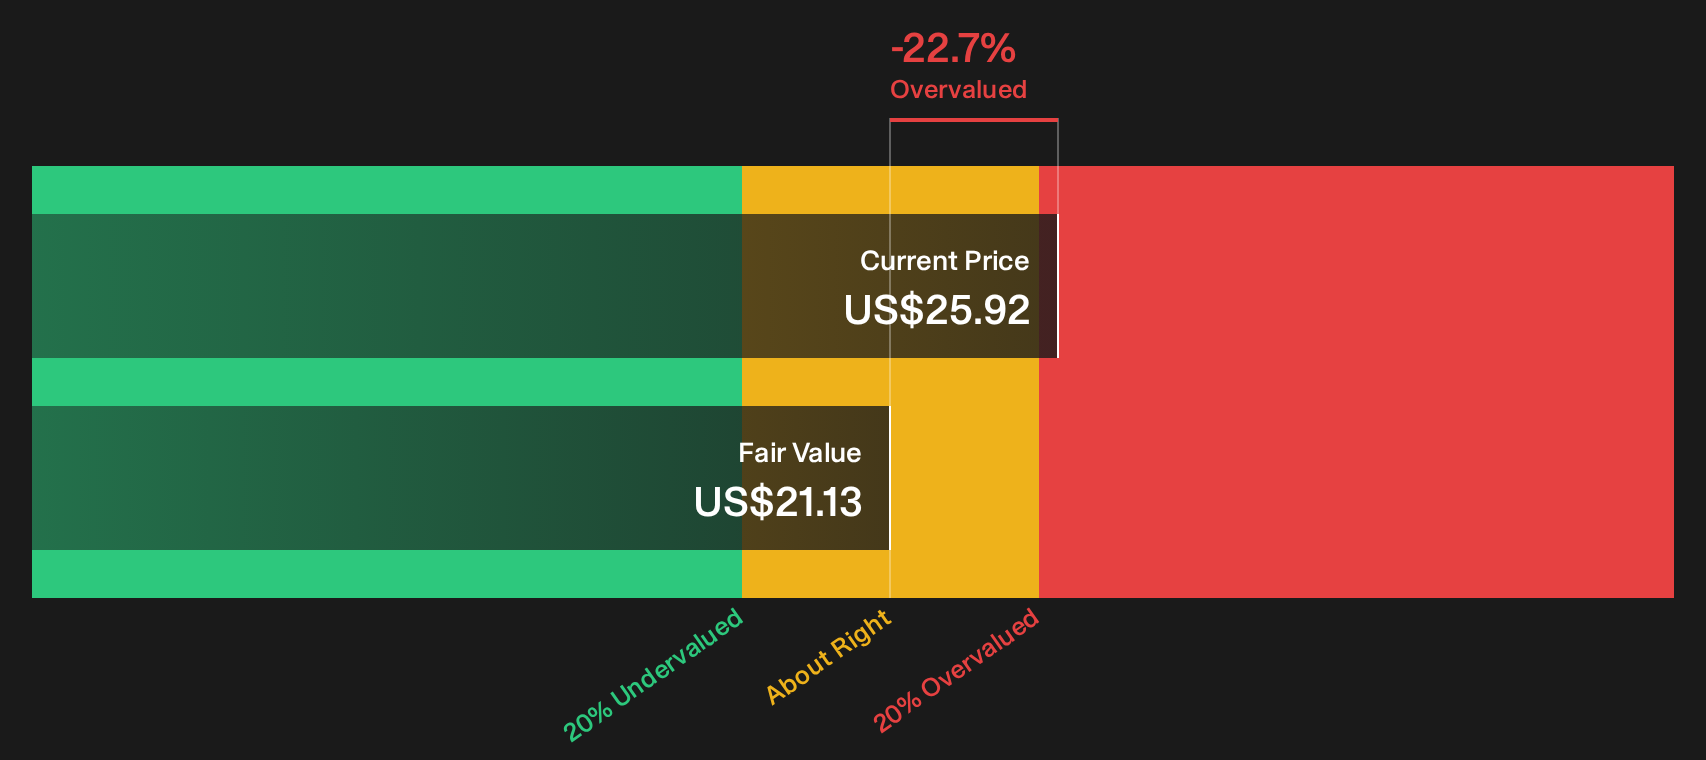
The story looks different when switching from analyst targets to the SWS DCF model. On this framework, Forestar Group shares at $25.92 sit above an estimated future cash flow value of $21.13, which screens as overvalued rather than discounted. That gap raises a simple question for investors: Are earnings multiples too generous for a business with softer cash flow assumptions?
For readers who want to see how that cash flow outcome was built from the ground up, the SWS DCF model lays out every input and step in one place. Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Forestar Group for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 26 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Forestar Group so far. If you want to act while sentiment is split, start with the 3 key rewards and 1 important warning sign
Looking for more Forestar Group style investment ideas?
If you want to keep your edge instead of reacting late, line up your next candidates now with a focused sweep through curated screeners on Simply Wall St.
- Target resilient balance sheets and sturdier fundamentals by scanning the list of solid balance sheet and fundamentals (24 results) that investors often turn to when capital preservation matters most.
- Hunt for mispriced opportunities by running through the 26 high quality undervalued stocks that highlights businesses where quality metrics and current pricing do not fully line up.
- Strengthen your income watchlist by reviewing the 6 dividend fortresses that groups companies combining higher yields with an emphasis on payout stability.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com