
What Compagnie de Saint Gobain Investors Missed Before The Fall
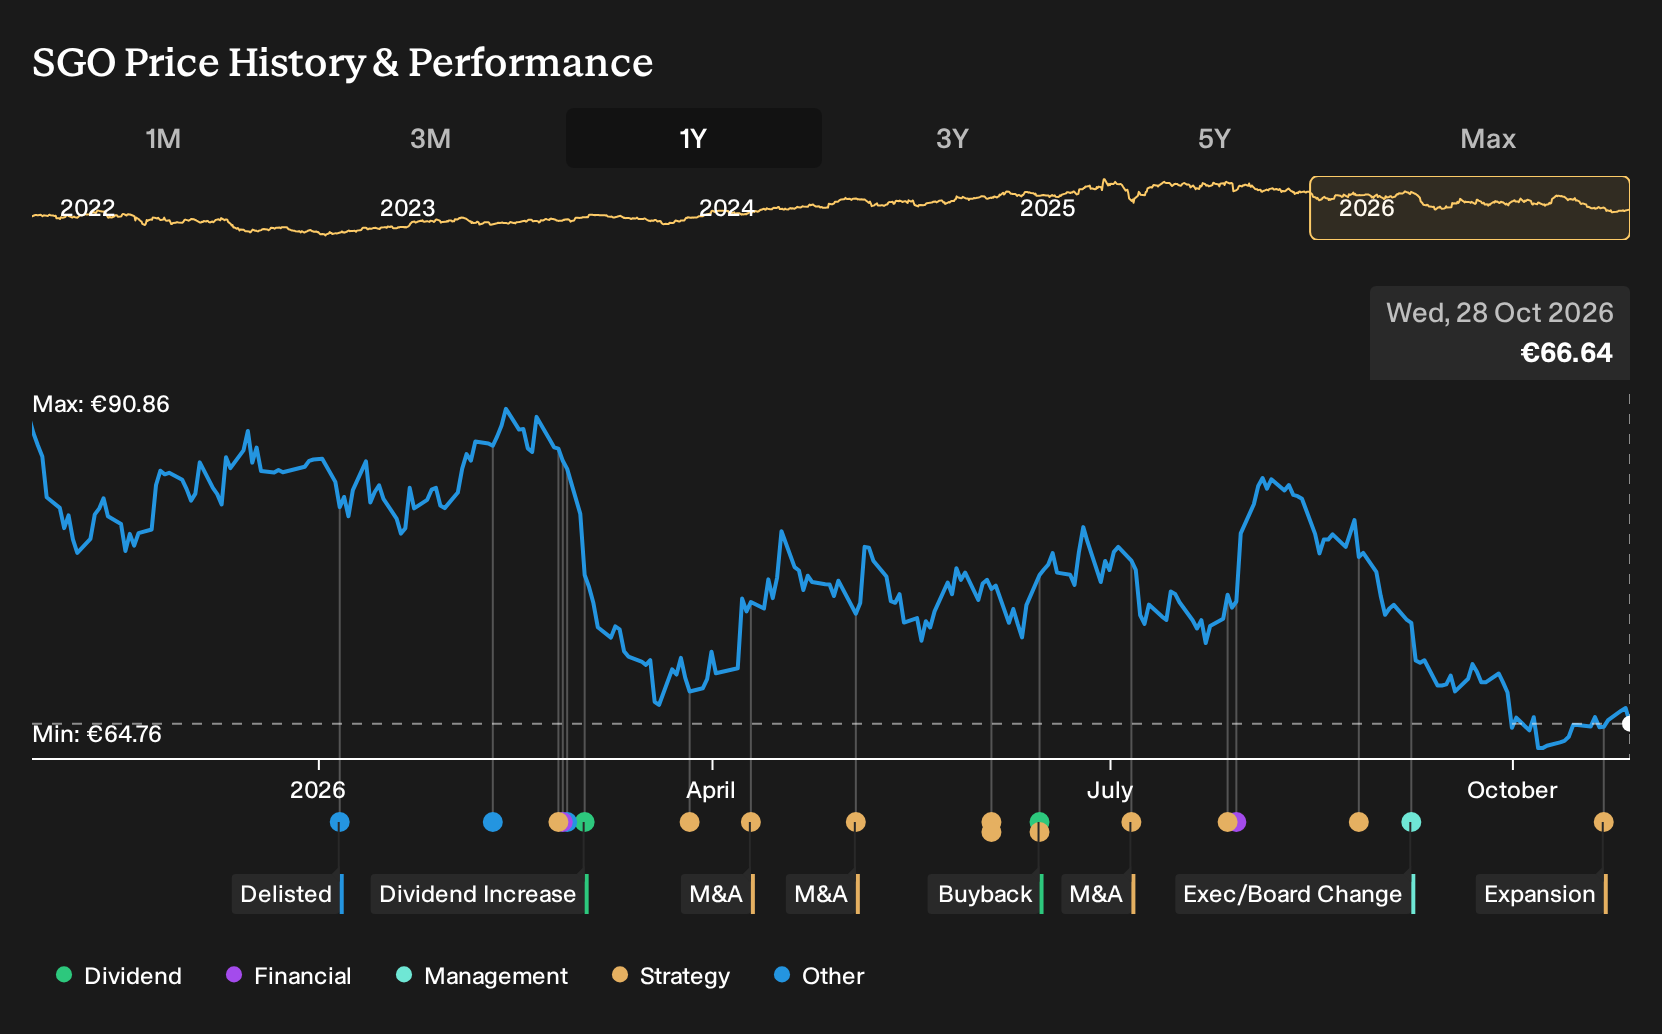
Saint-Gobain has kept investors busy this year, from reaffirming an EBITDA margin target above 15% on its Q2 2026 call to pushing deeper into gypsum recycling in Canada and glass and plasterboard capacity in Egypt. For Compagnie de Saint-Gobain shareholders, the loss over the past year was 22.0%, including dividends. If you had bought on 28 October 2025 with those upbeat and cautious narratives on record, how do these recent moves change what you now expect from the business?
The easy part of this move is behind Compagnie de Saint-Gobain. Zero in on 192 high quality undervalued stocks for companies trading below our estimates.
The Two Compagnie de Saint-Gobain Stories Investors Had To Weigh
The shares cost €88.96 at the start of the period, and you had to choose between two very different stories about Compagnie de Saint-Gobain.
The bullish narrative pointed to a Fair Value of €108, a price implied by expectations of 3.4% annual revenue growth and a profit margin moving toward 7.4%, backed by demand for sustainable building solutions and acquisitions in high growth regions.
The cautious view argued for a Fair Value of €72, based on slower 2.0% annual revenue growth and the risk that heavy European exposure and rising decarbonization costs could squeeze future earnings quality.
What The Results Changed For Compagnie de Saint-Gobain
Compagnie de Saint-Gobain reaffirmed an EBITDA margin above 15% for 2026 while pushing deeper into gypsum recycling in Canada and new glass and plasterboard capacity in Egypt, which leans toward the optimistic renovation and growth story. The harder fact cut the other way. H1 2026 revenue fell to €23,595m, net income slipped to €1,417m, and net margin moved from 6.8% to 6.0%, so the period cut both ways.
The big assumption investors made in October 2025 was higher profitability. When you judge another stock, track whether net margin and absolute profit move toward the thesis, even if management keeps repeating strong guidance.
What Compagnie de Saint-Gobain’s Lower Price Now Asks You To Believe
Compagnie de Saint-Gobain now trades at €66.64, with the share price down 22.0% over the past year. The selected Narrative’s Fair Value sits above the current price and leans on sustainable construction demand, higher growth regions and construction chemicals to carry returns.
The argument turns on Saint-Gobain using capacity additions, digital tools and capital returns to turn that portfolio mix into resilient cash generation. A buyer today would need to believe those execution gains outweigh pressure in mature markets and any extra cost from decarbonization and circularity projects.
"The main thing that has to go right is that Saint-Gobain continues to execute on portfolio rotation, decarbonization projects and digital tools such as AI-driven quoting and sales support, so that high-growth regions, construction chemicals and solutions-based offerings offset pressure in more mature markets."
The price and this Narrative do not agree. → Uncover what this Narrative says Compagnie de Saint-Gobain is actually worth
Looking Beyond Saint-Gobain
Compagnie de Saint-Gobain is tied to how buildings get made and upgraded. One step away, another kind of infrastructure quietly shapes that demand.
Data centres rely on robust power and cooling so digital services stay online. Without that backbone, many construction projects would lose a central purpose.
One specialist concentrates on these systems, from thermal control to monitoring. Its work helps operators keep dense computing hardware within safe temperature limits.
As AI workloads expand and older facilities change, that support role grows more intricate. If Saint-Gobain reflects the envelope, this other business reflects the engine room.
One Narrative has already put a figure on it. → Uncover the company trading 41% below one Narrative's Fair Value
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com