
Is Immunome (IMNM) Undervalued After New Varegacestat Data And FDA Review Progress?
Immunome (IMNM) is back in focus after presenting additional clinical data for varegacestat at the 2026 ESMO Congress, highlighting patient outcomes in desmoid tumors alongside advancing regulatory reviews in the United States and Europe.
Against this clinical backdrop, Immunome’s share price has given back some ground in the short term, with a 30 day share price return down 13.47% and a 90 day share price return down 18.72%. At the same time, the 1 year total shareholder return of 19.04% and 3 year total shareholder return of 118.90% point to longer term momentum that has rewarded patient holders.
Capitalize on the renewed interest in Immunome by scanning a curated set of oncology and higher potential healthcare names through our 34 healthcare AI stocks tailored for investors watching this space closely.Immunome is now trading well below recent highs after strong clinical headlines, which puts you at a fork in the road: lean into the current pullback or wait for a cleaner valuation setup ahead?
Most Popular Narrative: 48% Undervalued
Immunome last closed at $18.76, while the most followed narrative points to a fair value of about $36.31. This frames the recent pullback as a potential valuation gap rather than just weak sentiment.
The move from a single lead asset to a broader Immunome oncology platform, with IM-1021, IM-1617 and IM-3050 already in Phase 1 and two additional solid tumor ADC INDs planned for 2026, increases the number of shots on goal that could support multi-asset revenue streams and help spread fixed costs over a larger base, which may benefit margins over time.
See why 1 investors see Immunome as 48% undervalued.
Result: Fair Value of $36.31 (UNDERVALUED)
Still, the Immunome story can break if varegacestat runs into regulatory setbacks or if desmoid specialists adopt oral gamma secretase inhibitors more slowly than analysts anticipate.
Find out about the key risks to this Immunome narrative.
Another View: Immunome Looks Expensive On Book Value
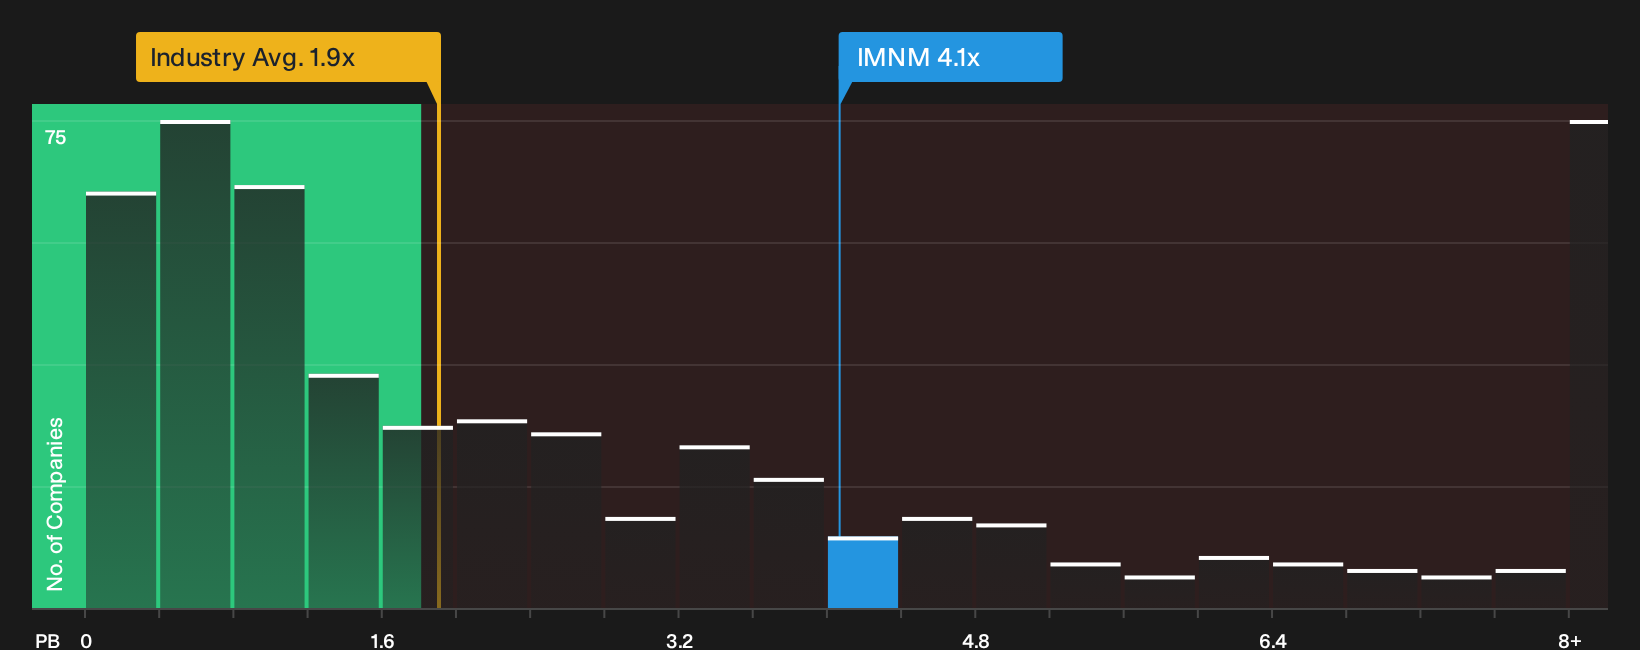
On one hand, Immunome screens as undervalued on fair value models that point to a big gap between price and future cash flow potential. On simple market ratios, the picture is very different. The stock trades on a P/B of 4.1x versus 1.9x for the US Biotechs industry and 3.1x for peers, which signals investors are already paying a premium for each dollar of net assets and leaves less room for error if the growth story slips.
For a closer look at how that premium lines up with the underlying business drivers, run through the valuation breakdown in the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed signals around Immunome can either spook you or sharpen your process. Move fast, pull up the full scorecard, and weigh the 3 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Immunome?
If you only stop at Immunome, you might miss other setups that better match your goals, risk tolerance, and timeline across sectors and market caps.
- Target aggressive upside potential by scanning the 7 elite penny stocks with strong financials that pair higher risk with focused, stock specific growth stories.
- Zero in on quality at a discount by reviewing the 29 high quality undervalued stocks that combine solid fundamentals with prices below fair value estimates.
- Prioritise resilience and capital preservation by filtering for a 30 resilient stocks with low risk scores that screens for sturdier balance sheets and lower risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com