
Electrolux Professional (OM:EPRO B) Stock Can Q2 Earnings Ease Margin Concerns
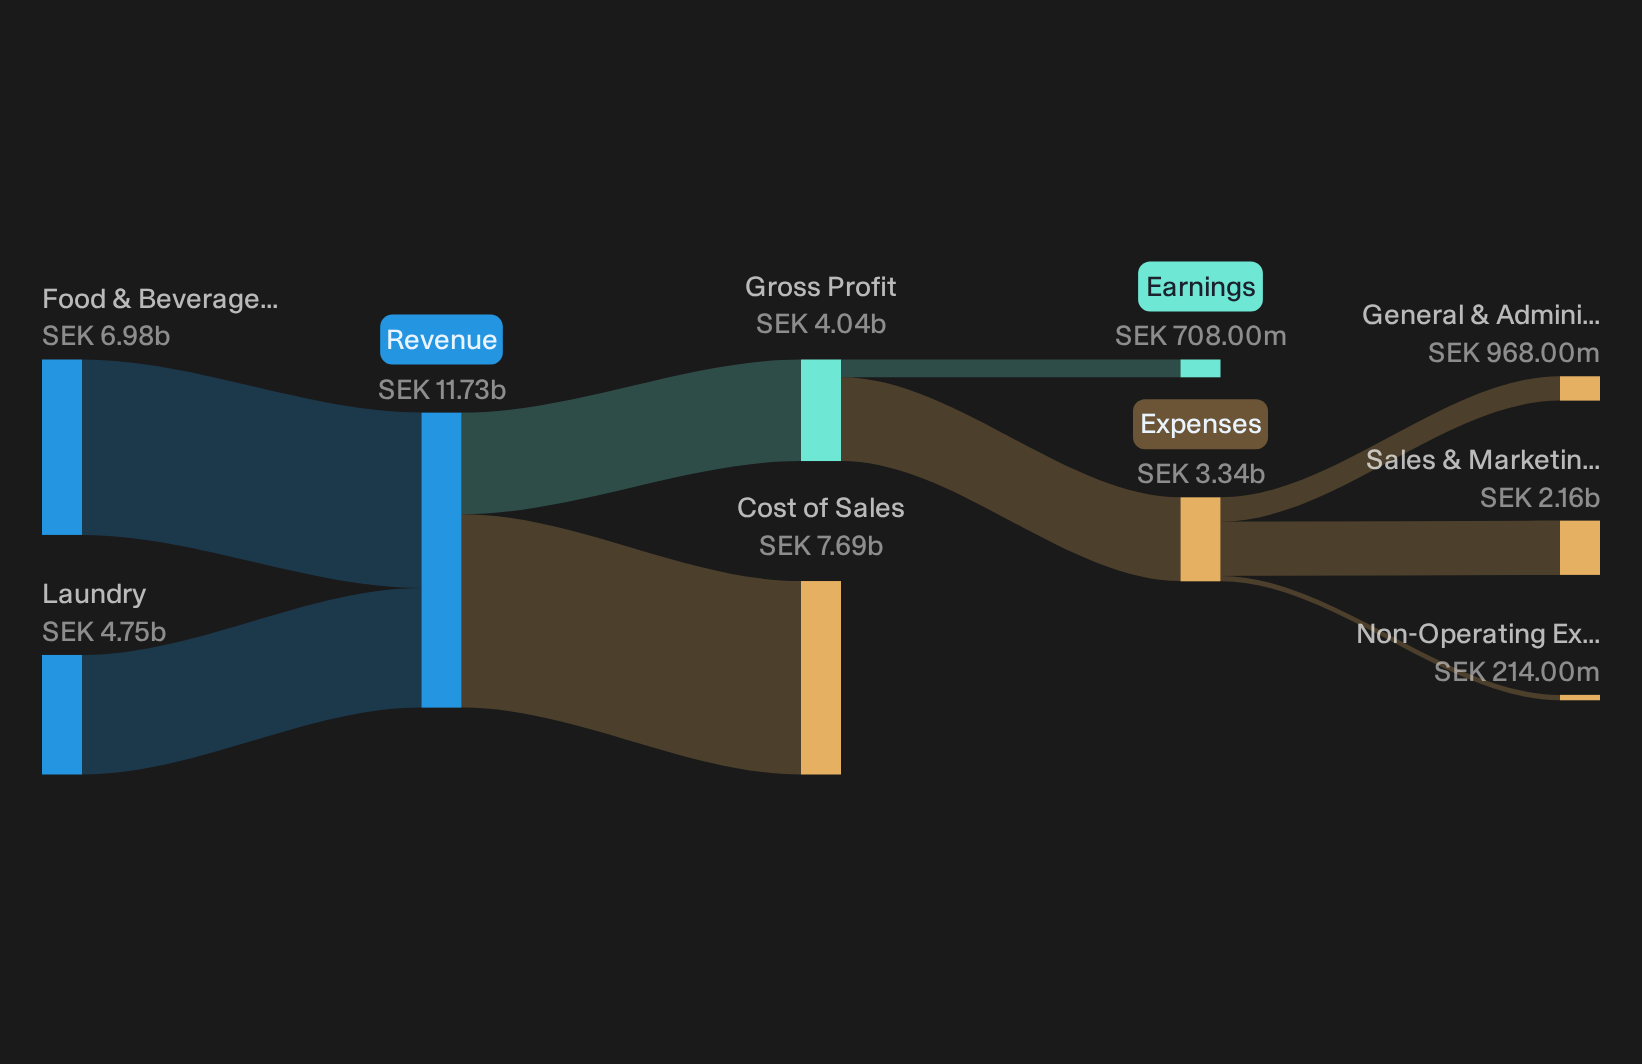
Electrolux Professional stock closed today at SEK52.4 after a steady run over the past month, yet the real story sits in the fresh Q2 2026 earnings. The company printed basic earnings per share of SEK0.80 on revenue of SEK3,036m, with net profit of SEK230m. Those numbers feed into a price that still screens cheap on a P/E of 21.3x versus peers on 24x, even as margins have eased to a 6% trailing net level. Short term traders are watching the chart, while long term holders are looking at a different equation.
Like the earnings profile of Electrolux Professional but uneasy about margins easing while the P/E still leans on peer comparisons? See how that trade off stacks up against companies in our list of solid balance sheet and fundamentals stocks (207 results)
Q2 2026 Electrolux Professional Earnings Summary
- Revenue (Q2 2026 vs Q2 2025): SEK3,036m vs. SEK3,195m (down 5.0%)
- Net Income (Q2 2026 vs Q2 2025): SEK230m vs. SEK217m (up 6.0%)
- Basic EPS (Q2 2026 vs Q2 2025): SEK0.80 vs. SEK0.76 (up 6.0%)
- Trailing 12-month Net Profit Margin (Last 12 Months vs Prior Year): 6.0% vs. 6.5% (margin softened)
Prefer clean, visual charts instead of another dense wall of earnings tables and ratios? See Electrolux Professional's full financial picture with a focus on valuation trends in the company report for Electrolux Professional.
Electrolux Professional: Pricing And Efficiency Score Early Wins
For Electrolux Professional, the bullish story claims that smarter pricing and cost cuts can lift earnings quality while R&D spending eases off.
"For Electrolux Professional, analysts expect pricing, surcharges and efficiency measures to support earnings quality as new product launches move from heavy R&D spend into commercialization."
Q3 backs part of that script. Organic sales grew 3.4% and EBITA margin reached 12.6%, helped by pricing, volume and tariff refunds. The efficiency program has delivered SEK65m to SEK70m in savings year to date toward an SEK85m target, which points to execution progress. Laundry margins at 18.1% indicate that mix and newer platforms can support profitability.
Cost Inflation And U.S. Weakness Still Shadow The Story
There is also a clear worry that external pressures and execution missteps could eat away at those gains.
"The main thing that has to go right is that cost savings from the efficiency program and pricing actions continue to offset tariffs, currency effects, higher capital expenditure and the weakness in U.S. Food & Beverage."
Recent numbers show some of this risk persisting. Americas Food & Beverage remains soft, even if the decline eased late in Q3. Transport costs have risen and raw material inflation is set to hit from Q4. FX moved from a drag to a small positive this quarter, so the idea that internal actions can counter external headwinds is not fully proven yet but has not broken either.
That disagreement has a full argument behind it. → Uncover the higher Fair Value this Narrative argues for.
Hunt For Quiet Earnings Mispricing
Electrolux Professional illustrates how an earnings narrative can obscure what its current price reflects. The real opportunity is finding stocks that could be undervalued before the market corrects them.
- Company 1 - 22% below our estimate - uses unmanned naval systems and inertial navigation contracts to convert a defense backlog into longer revenue visibility.
- Company 2 - 45% below our estimate - pushes a single technology platform so fee businesses can scale while cost controls reshape loan profitability.
- Company 3 - 40% below our estimate - focuses on longer civil and data center projects that secure high-margin construction work and free capital for property divestments.
That is three of the list. See every one of the 195 undervalued companies on it →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com