
Invesco (IVZ) Q3 Results Put Margin Strength In Focus
Invesco came into this Q3 2026 earnings print with a stock that had drifted, down about 2% over the past week and roughly 6% over the past month. Yet the immediate reaction told a different story. Shares inched up less than 1% to US$28.68 by the close after the release, a muted move compared with the scale of improvement in the quarter’s profitability.
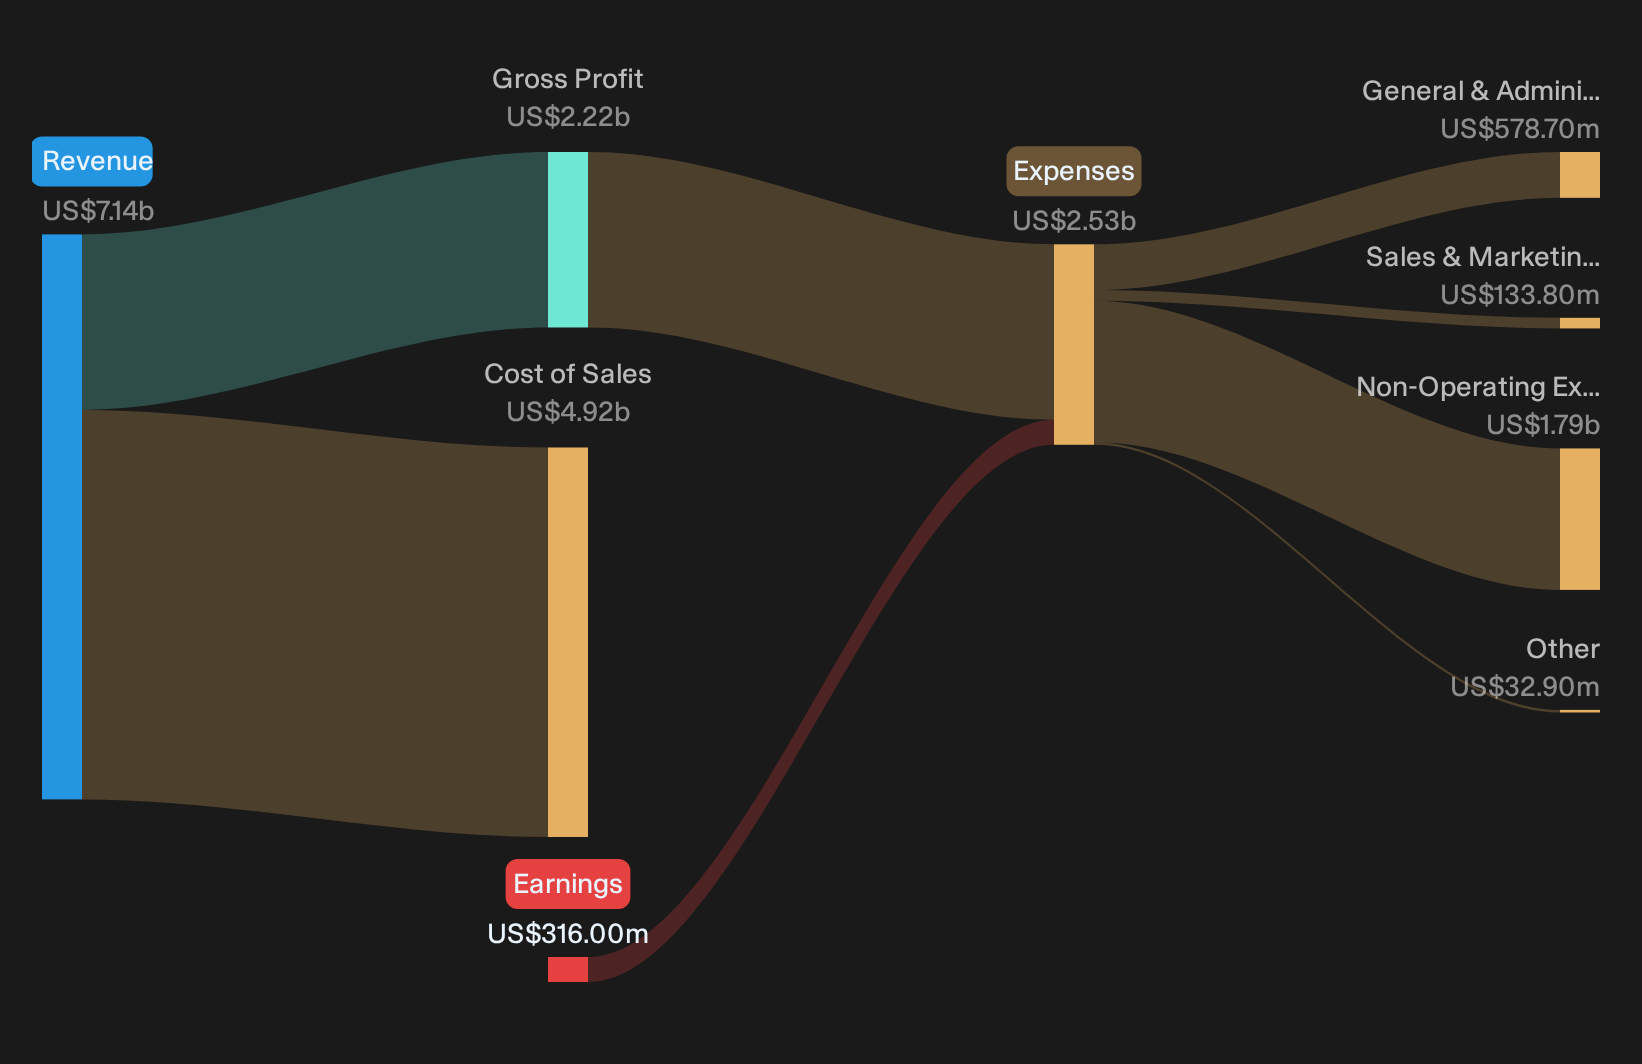
The real headline is margin and profit strength. Net revenue reached about US$1.4b and adjusted operating income hit US$562m, with adjusted diluted EPS at US$0.72. For an asset manager that has been wrestling with uneven earnings, this quarter landed well ahead of the recent narrative baked into the price.
Impressed by Invesco’s profitability this quarter but still uneasy about how durable those earnings might be over a full cycle? Have a look at our curated list of sturdier balance sheet ideas in the list of solid balance sheet and fundamentals stocks (24 results)
Q3 2026 Earnings Summary
- Revenue (Q3 2026 vs. Q3 2025): US$1,873.2m vs. US$1,640.4m (top line improved)
- Net Income, Excl. Extra Items (Q3 2026 vs. Q3 2025): US$294.5m vs. US$301.3m (slightly softer bottom line)
- Basic EPS, Earnings Per Share (Q3 2026 vs. Q3 2025): US$0.66 vs. US$0.67 (broadly stable per share result)
- Adjusted Operating Margin (Q3 2026 vs. Q2 2026): 40.7% vs. 37.5% (margin expansion quarter on quarter)
Earnings tell you what Invesco booked this quarter, but cash flows tell you what the business is actually throwing off that might matter for long term valuation work. Investors who care about what they are paying for NYSE:IVZ often start there.
On Invesco’s cash flows alone, and using that stream of cash as the yardstick rather than one quarter of profit, the stock could be a dramatic 42% undervalued.
Invesco bullish story: scale, QQQ and margins on trial
Supporters argue that Invesco’s push in ETFs, private markets and digital tools will translate into structurally better profitability.
"Invesco's strong growth in global ETF and index products (notably QQQ and QQQM) and ongoing innovation in both active and passive strategies position the firm to benefit from the continued investor shift towards low-cost, scalable investment options, supporting asset growth and potentially higher fee-based revenue and operating margins."
The latest quarter backs up the scale part. ETF assets reached US$775b with about US$29b of inflows, and the QQQ suite drew roughly US$16b alone. Net long term inflows of US$35.1b and 40.7% adjusted operating margin show the platform is currently converting growth into higher efficiency.
Bear case on fee pressure and execution faces mixed evidence
Skeptics worry that the very ETF shift powering Invesco will grind down revenue yield and blunt margin progress.
"The ongoing secular shift from higher-fee active management to lower-fee passive investment strategies and ETFs is reducing Invesco's net revenue yield, as evidenced by continued declines to 23.2 bps, and is likely to sustain pressure on its revenue and profit margins long term."
Current results show both sides of that tension. Net revenue yield slipped again to 21.5 bps with money market and ETF mix, and the exit yield was 21.3 bps. Yet adjusted operating margin reached 40.7% and net revenue was about US$1.4b, helped by expense discipline and tech related cost control, so fee compression has not yet derailed profitability progress.
One Narrative has put a figure on that disagreement. → See the Narrative with its higher Fair Value, assumptions and all.
Hunt Quiet Dislocations In Plain Sight
Invesco recently highlighted how a strong earnings story can be met with a surprisingly muted share price reaction. The real opportunity is hunting for stocks that could be undervalued before the market closes these gaps.
- Company 1 - 27% below our estimate - builds large-scale AI superclusters that support a leading model developer with added compute resilience.
- Company 2 - 38% below our estimate - expands a device trade-in and refurbishment network as recycling subsidies and younger shoppers support secondhand electronics.
- Company 3 - 46% below our estimate - converts a near record construction backlog into work on large projects while managing legacy legal disputes.
Those are three of them. See every one of the 29 undervalued companies on it →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com