
Huntsman (HUN) Could Be 16% Undervalued On Earnings Beat Hopes
Huntsman earnings expectations come into focus
Investor attention around Huntsman (HUN) has picked up as the market waits for the September 2026 quarter report, with expectations for changes in earnings and revenue shaping sentiment ahead of the planned November 2 release.
Recent moves in Huntsman’s share price have been choppy, with a 9.35% 7 day share price return and a 2.47% 30 day gain following a much sharper 23.75% decline over the past 90 days. The 3 year total shareholder return of 54.86% and 5 year total shareholder return of 66.72% both point to a longer stretch of weak compounding despite a positive 3.86% total shareholder return over the past year, suggesting that recent momentum has picked up but from a lower base as investors weigh potential earnings upside against prior setbacks.
Scan Huntsman’s setup ahead of earnings alongside a curated list of materials players showing resilient fundamentals in our 29 high quality undervalued stocks.
After a sharp three month slide followed by a short burst of strength, Huntsman now poses a simple question to buyers: Does the current price still offer enough upside to justify the risks as earnings expectations build?
Most Popular Narrative: 16% Undervalued
On the narrative view, Huntsman’s fair value of $10.85 sits above the recent $9.12 close. This puts the focus firmly on whether the underlying business shifts can justify that gap as earnings expectations reset.
Demand for Huntsman's advanced materials and polyurethane-based products is expected to benefit from accelerating global trends in sustainability, energy efficiency, and lightweighting, especially as infrastructure and construction activity resumes, and the EV/clean tech markets expand. This supports potential for higher long-term revenue growth and greater market share.
See why 14 investors see Huntsman as 16% undervalued.
Result: Fair Value of $10.85 (UNDERVALUED)
Still, if chemical demand in Europe stays weak or overcapacity in polyurethanes persists, Huntsman’s margin recovery story could look far less convincing.
Find out about the key risks to this Huntsman narrative.
Another View on Huntsman’s value
The earlier fair value narrative presents Huntsman as 16% undervalued. A different perspective suggests a more cautious interpretation. Our DCF model points to a future cash flow value of $7.22 per share, which is below the current $9.12 price and indicates overvaluation on that basis.
This difference between a DCF result below the market price and a higher narrative fair value leaves you with a choice. Which set of assumptions around earnings recovery and required return aligns more closely with how you view Huntsman’s next few years, and which one are you more comfortable relying on when real money is at risk?
Look into how the SWS DCF model arrives at its fair value.
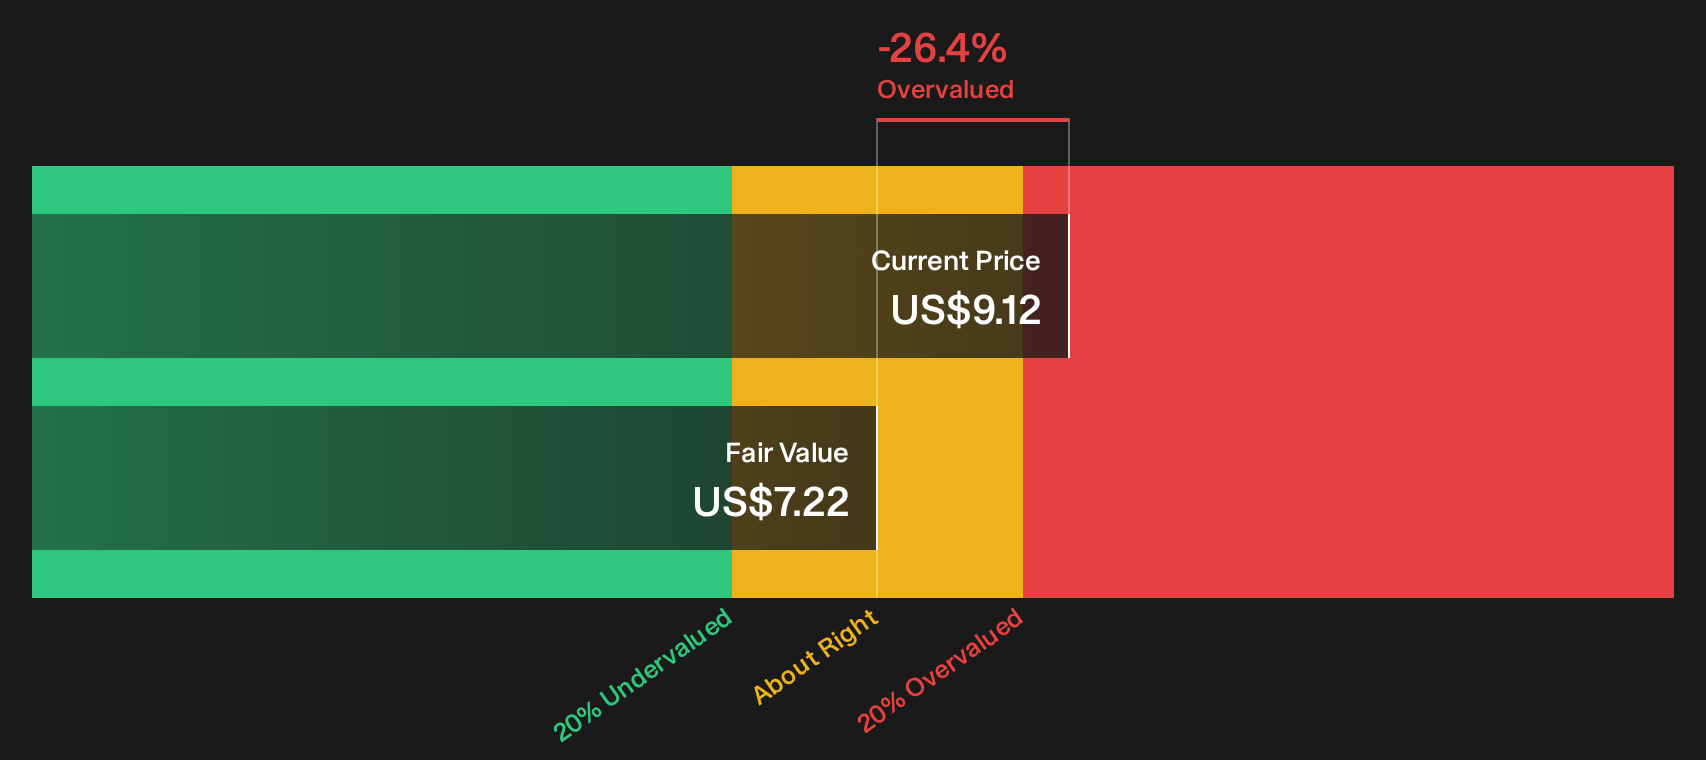
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Huntsman for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 29 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment on Huntsman is clearly split. This is exactly why it pays to move fast, test the numbers yourself, and weigh both the downside and upside using the 2 key rewards and 2 important warning signs.
Looking for more Huntsman investment ideas?
If Huntsman has you rethinking your watchlist, broaden your search now with data driven shortlists so you are not stuck reacting after the next move.
- Target resilient balance sheets and steadier fundamentals with a curated list of solid balance sheet and fundamentals (24 results) that can help you stress test your current holdings.
- Hunt for potentially mispriced opportunities by scanning a focused 21 high quality undiscovered gems that many investors may not be watching yet.
- Dial back volatility risk and still stay in the market by reviewing a 30 resilient stocks with low risk scores tailored for more defensive positioning.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com