
Learn Why The Bull Case For Norsk Hydro (OB:NHY) Could Change Following Analyst Downgrades
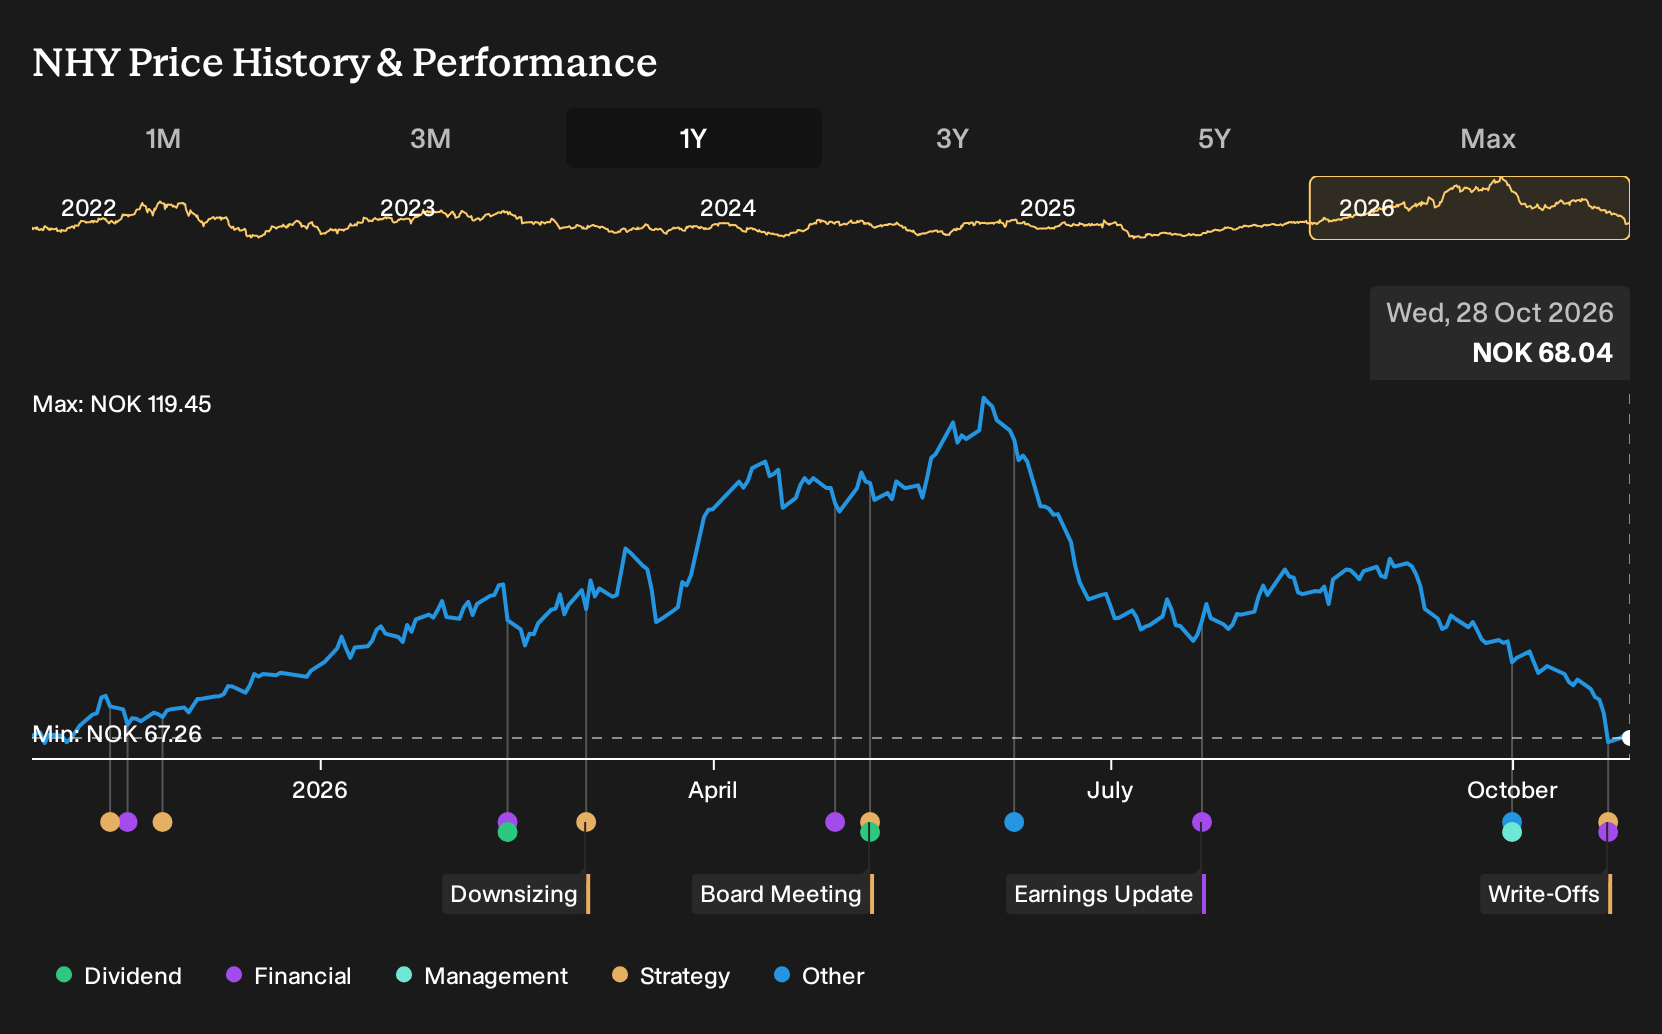
- Norsk Hydro reported third quarter 2026 revenue of NOK 53,240 million and net income of NOK 5,378 million, alongside NOK 70 million of fixed asset impairments.
- The combination of higher earnings and fresh write downs highlights how Norsk Hydro is still adjusting its asset base while managing cost and pricing pressures in aluminium markets.
- This article will examine how Norsk Hydro's investment narrative is influenced by earnings strength and by higher cost concerns noted in recent analyst commentary.
Compare Norsk Hydro's latest earnings and cost pressures with peers by scanning our hand picked list of solid balance sheet and fundamentals (207 results) that may be better insulated from similar shocks.
Norsk Hydro Investment Narrative Recap
Norsk Hydro appeals to investors who buy into a simple idea. The business needs to turn its low carbon aluminium, growing recycling operations and long term Nordic power contracts into steady cash generation despite choppy energy and alumina markets. The latest quarter, with NOK 5,378 million in net profit and NOK 70 million of impairments, keeps that operational story intact.
The bigger swing factor near term is how energy and input costs shape earnings from 2027, not the size of this impairment. Gas exposure at Alunorte and alumina pricing remain the headline risks. Progress on securing long term gas and keeping Bauxite & Alumina margins in check is the key operational catalyst to watch.
The most relevant fresh datapoint is management’s plan to lay out a 2027 outlook at the capital markets day on 25 November 2026. That event comes as some brokers highlight falling aluminium premiums, rising LNG costs and lower EBITDA estimates, which puts execution in the spotlight. Investors get an important check on how Norsk Hydro frames volumes, capex and cost discipline against those headwinds.
For investors, that presentation is where the medium term story either tightens up or becomes harder to underwrite. Watch for detail on gas contracting for Alunorte, recycling EBITDA ambitions and the use of long term Norwegian power contracts to support primary aluminium margins. Those points link directly back to the main near term catalysts and the energy related risk around 2027 earnings quality.
Norsk Hydro’s current analyst storyline points to NOK 221.7b in revenue and NOK 15.0b in earnings by 2029, which reflects 2.7% yearly top line growth and an earnings increase of roughly NOK 5.2b from NOK 9.8b today.
Uncover why Norsk Hydro's fair value indicates a 31% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One bullish angle on Norsk Hydro focuses on cost savings rather than gas risk. The most optimistic analysts had pencilled in revenue of about NOK 237.9b and earnings of NOK 22.4b by 2029, assuming workforce cuts and plant closures lift margins. After the strong Q3 profit and fresh impairments, those pre news forecasts may shift, so you should compare several viewpoints before leaning on any single story.
Explore 4 other Norsk Hydro fair value estimates, including one that suggests as much as 69% upside from the current price!
Decide For Yourself
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Norsk Hydro research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Norsk Hydro. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Norsk Hydro's overall financial health at a glance.
Looking For More Investment Ideas Beyond Norsk Hydro?
If you want to stress test your Norsk Hydro thesis and broaden your watchlist, it helps to line it up against other companies with different risk and return profiles using the Simply Wall St Screener.
- For investors hunting for companies that trade below their estimated worth while still showing solid fundamentals, scan our hand picked 195 high quality undervalued stocks and compare how their profiles stack up against Norsk Hydro.
- If resilience and capital preservation matter most to you, review a 223 resilient stocks with low risk scores and see which businesses score well on stability alongside Norsk Hydro in your research list.
- For those who care about quality finances and a cushion against shocks, broaden your search with a list of solid balance sheet and fundamentals (207 results) and weigh those balance sheets against what you see at Norsk Hydro.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com