
Upwork (UPWK) Stock May Look Reasonable Based On Earnings Power
Upwork trades around US$9.07 a share after a long stretch of mixed returns, which raises a simple question for you as an investor: Is the current price level sensibly anchored to the earnings power of the freelance marketplace business, or has sentiment moved further than the underlying profits justify?
- The stock has fallen 81.4% over the past 5 years, which puts the focus squarely on whether the earnings it generates today can support even this lower valuation base.
- The marketplace model depends heavily on converting client and freelancer activity into consistent profits, so the way fees translate into earnings may support or constrain how much value the current share price can reasonably reflect.
- Your read on Upwork is one view; the desks covering it have another. See what analysts think Upwork's shares could be worth.
The stock's next move may depend on whether Upwork's earnings are strong and reliable enough to make the current valuation look sensible on an earnings basis.
If you want to review more than one earnings story, a focused stock screen is a helpful next step. To continue your research, you can compare Upwork with 29 high quality undervalued stocks
Is Upwork a Bargain on Earnings?
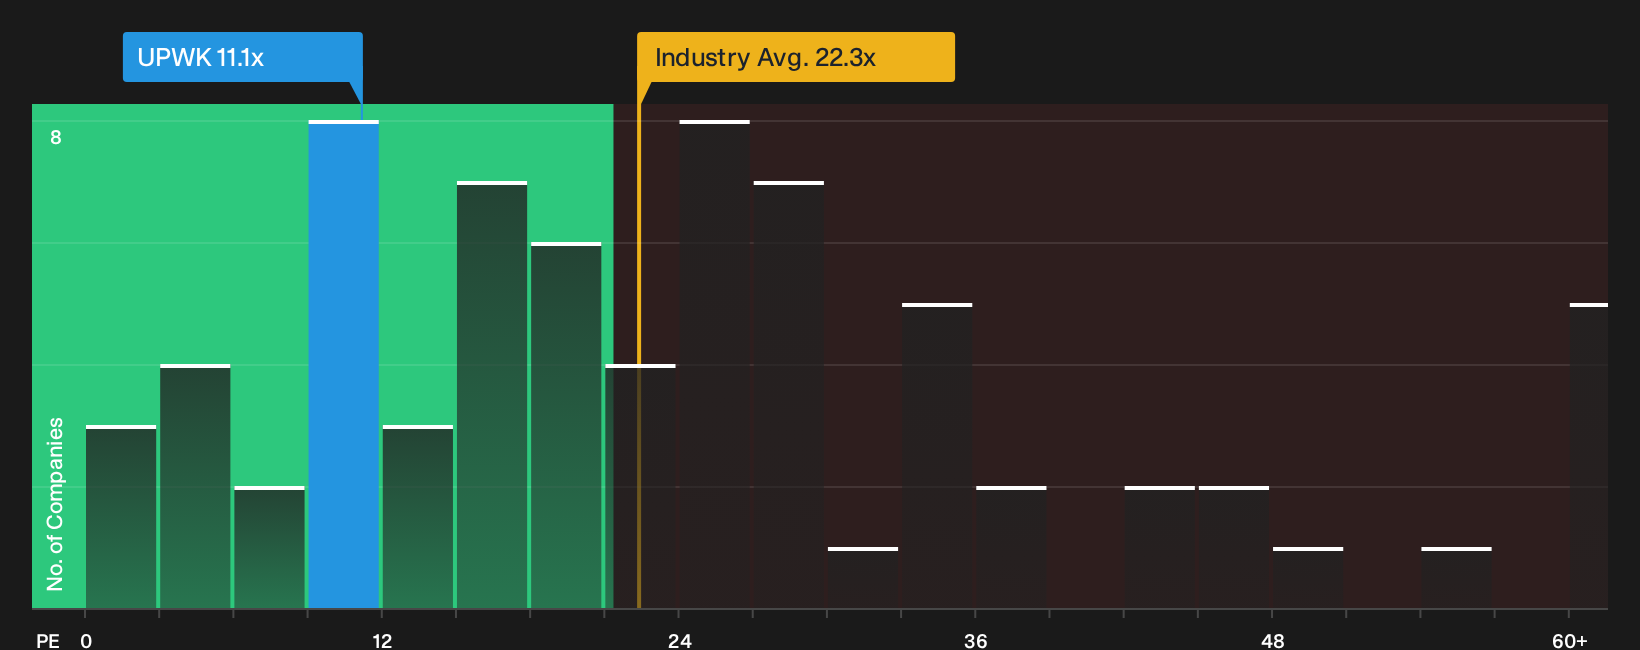
The P/E ratio suits a platform like Upwork because investors often anchor their expectations to how efficiently it can turn marketplace activity into net income. On that metric, Upwork trades on roughly 11.1x earnings, compared with about 22.3x for the wider Professional Services industry and around 20.6x for its peer group. As a result, the stock changes hands at a noticeably lower earnings multiple than many comparable businesses.
The valuation model that blends Upwork's growth profile, margins, size and risk suggests a higher P/E would usually be expected for a company with these characteristics, and the current 11.1x sits below that tailored reference point. For you as a shareholder or potential buyer, that gap points to a market price that embeds more cautious expectations than the model implies. This puts the focus back on whether you think Upwork's earnings quality can justify a rerating. Explore the numbers behind Upwork's P/E valuation.
The Upwork Narrative: What Would Justify Today's Price?
Upwork Narratives pick up where the P/E puzzle leaves off and explain what combination of future growth, margins and earnings power would need to occur for the stock to look meaningfully above or below today's price on Simply Wall St's Community page. Each scenario links a fair value estimate to a particular view of Upwork's possible catalysts and risks, so you can track over time which version of events appears closest to reality.
Community views on Upwork split between investors who see underappreciated earnings power and those who think current client and traffic pressure already set the ceiling.
Bull case: 8% undervalued
"The main thing that has to go right is that Upwork converts its repositioning as AI native infrastructure and its Business Plus and Lifted offerings into durable client growth..."
Discover why this Narrative puts Upwork at 8% undervalued.
Bear case: 13% overvalued
"Although Upwork is growing higher value offerings such as Business Plus and Lifted with rising GSV per active client, total GSV of US$966 million, revenue of US$191.7 million, and 763,000 active clients in Q2 2026 show that higher spend per client has not yet offset pressure from AI automation, macro softness, and weaker SEO driven acquisition..."
Explore why this Narrative puts Upwork at 13% overvalued.
Upwork's price is only one clue in the bigger decision
Market pricing tells you what investors pay today, but analyst models sketch where they think Upwork could be a few years from now, which gives you one more yardstick to compare with the current valuation. Explore where analysts expect Upwork to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com