
Learn Why The Bull Case For Kymera Therapeutics Stock Could Change Following Earnings Beat
- Kymera Therapeutics is expected to report a quarterly loss of $1.26 per share on revenue of about $6.05 million, with revenue projected to be very large compared with the same period a year earlier.
- Progress in Kymera Therapeutics’ immunology pipeline, including positive Phase 1b data for oral STAT6 degrader KT-621 and rapid Phase 2b enrollment in atopic dermatitis, points to rising operational focus on orally delivered, protein-degrading therapies.
- Next, the focus will be on how Kymera Therapeutics’ expected earnings beat and KT-621 progress could reshape the broader investment narrative.
Kymera Therapeutics Investment Narrative Recap
To own Kymera Therapeutics, you need to believe its protein degradation platform, especially in immunology, can turn clinical data into durable commercial assets before the cash runway tightens. The current setup is still high burn and loss making, with R&D and trial execution absorbing capital as management advances multiple oral programs in parallel.
The short term swing factor is clinical progress and readouts around KT 621 and adjacent immunology assets. The expected quarterly loss of $1.26 per share paired with revenue of about $6.05 million does not materially change that. The bigger near term risk is trial setbacks or delays that stretch spending into a finite mid 2027 runway.
The recent focus on KT 621, including positive Phase 1b data in atopic dermatitis and rapid completion of Phase 2b BROADEN2 enrollment, sits closest to the core earnings story. This program is positioned to test whether Kymera Therapeutics can offer biologics like efficacy in an oral format across diseases such as atopic dermatitis and asthma.
If BROADEN2 data by late 2026 are strong, they could support the plan to start Phase 3 trials by mid 2027 and give more substance to revenue growth forecasts. Weak or inconclusive results would cut against that and make Kymera’s already high R&D spend, ongoing losses, partnership reliance and projected cash runway a more pressing concern for holders.
Kymera Therapeutics’ analyst narrative points to forecast revenue of US$52.5 million and projected earnings of US$9.3 million by 2029, with revenue assumed to decline by 20.6% a year and profit shifting from a reported loss of US$299.6 million today to that future earnings level.
Uncover why Kymera Therapeutics' fair value indicates a 17% potential upside to its current price that could narrow quickly.
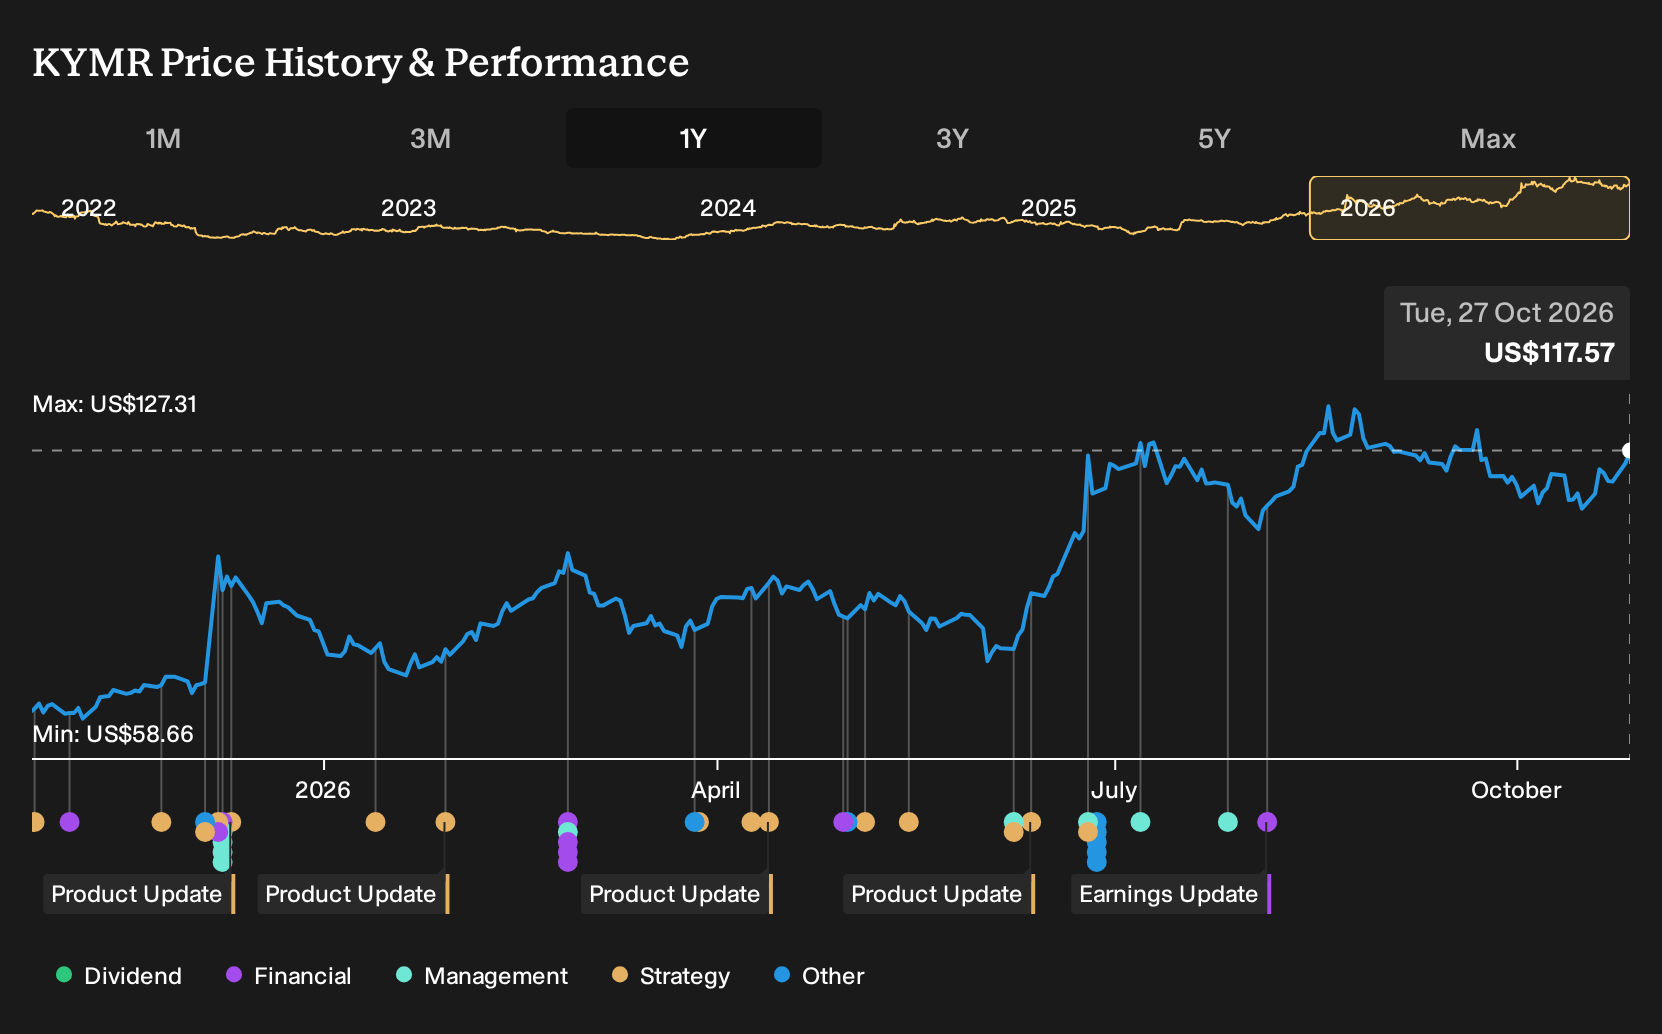
Exploring Other Perspectives
Some of the most optimistic analysts focus on KT-621 as a portfolio maker rather than a single drug, which is a very different tone from the consensus caution on cash burn. Before this earnings print, the bullish camp was working off 2029 forecasts of about US$102.9 million in revenue and US$16.4 million in earnings. That is far ahead of the baseline view and could shift again once the latest results are fully reflected in fresh models, so treat it as one of several stories to compare for Kymera Therapeutics.
The Verdict Is Yours
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Kymera Therapeutics research is our analysis highlighting 1 key reward and 4 important warning signs that could impact your investment decision.
- See our latest analysis for Kymera Therapeutics. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Kymera Therapeutics' overall financial health at a glance.
Looking For More Investment Ideas Beyond Kymera Therapeutics?
Once you have a handle on Kymera Therapeutics, it can help to compare it with other businesses that share similar traits in size, balance sheet strength or perceived mispricing. The Simply Wall St Screener can narrow that field quickly so you spend more time weighing actual trade offs and less time paging through tickers.
- If you want potential upside with tight budgets, scan smaller companies where every dollar of progress matters through 7 elite penny stocks with strong financials.
- For those hunting for mispriced quality, focus on stronger fundamentals and sensible valuations using the 29 high quality undervalued stocks.
- If capital protection ranks high for you, concentrate on sturdier balance sheets and cleaner finances via the list of solid balance sheet and fundamentals (24 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com