
Does Stronger Q3 Earnings Change The Bull Case For Wintrust Financial Stock (WTFC)?
- Wintrust Financial reported third quarter 2026 net interest income of US$621.6 million and net income of US$239.05 million, with higher basic and diluted earnings per share from continuing operations than in the same period a year earlier.
- The bank paired those stronger third quarter and nine month earnings with previously announced common and preferred dividends, highlighting a focus on both profitability and direct cash returns to shareholders.
- This article will examine how Wintrust Financial's stronger third quarter earnings may influence the longer term investment narrative that has been built around organic growth.
Compare Wintrust Financial's blend of earnings strength and cash returns with a hand picked 5 dividend fortresses that shares a similar focus on income and resilience.
Wintrust Financial Investment Narrative Recap
To own Wintrust Financial, you generally need to believe its core community and specialty banking model can keep turning a larger earning asset base into consistent profits while managing credit risk in commercial real estate and office exposure. The recent quarterly results and earnings per share trends support that operating story. The near term swing factor still looks like credit quality versus loan growth, and the Q3 net charge offs do not appear to materially change that balance.
The biggest operational risk right now is that competition in commercial and commercial real estate lending squeezes loan yields at the same time Wintrust Financial keeps spending on technology and branch expansion. That combination could pressure net interest margin and operating leverage if growth slows or premium finance and mortgage banking revenue remains volatile.
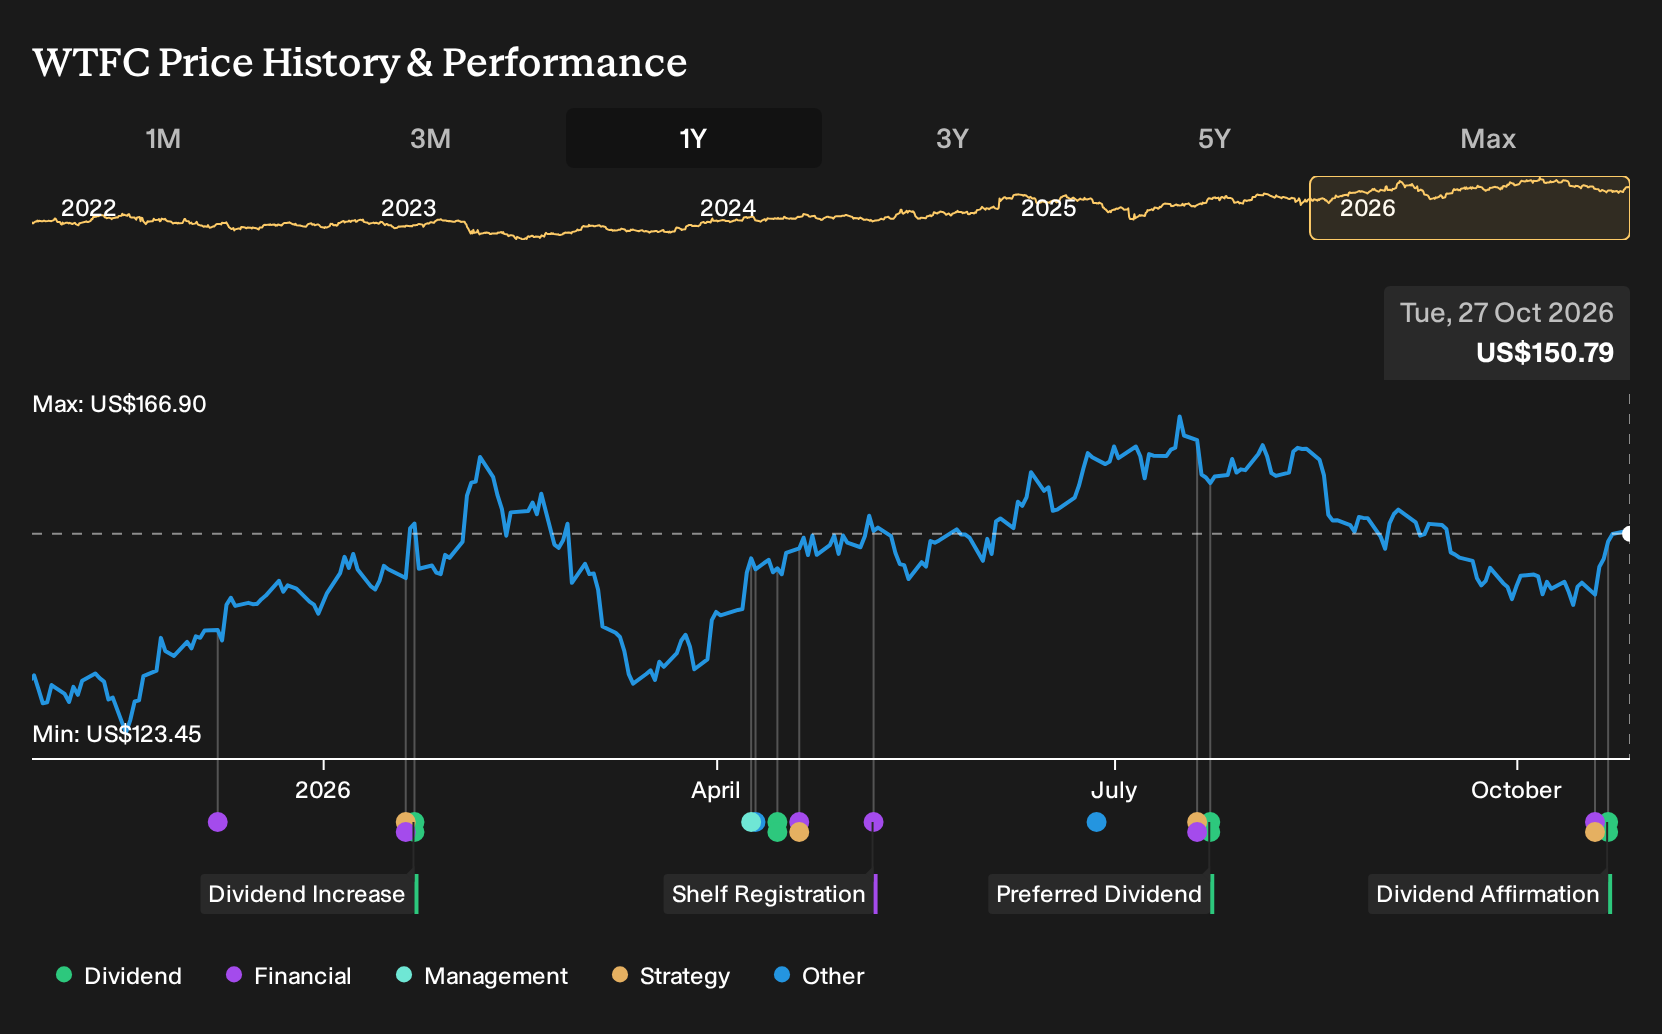
The common dividend affirmation at US$0.55 per share is the clearest near term signal relevant to this earnings update. For an income focused holder, a maintained payout alongside higher quarterly and nine month earnings suggests management sees current profitability and capital levels as sufficient to support ongoing cash distributions while funding growth in community banking and specialty finance.
For catalysts, that payout sits next to several moving pieces. Organic loan and deposit growth, digital banking investment and expansion in Chicago and Northwest Indiana branches are intended to build scale, while premium finance repricing, mortgage revenue swings and any deterioration in commercial real estate could offset those efforts. The dividend decision slots into that picture as one more variable for you to weigh against credit risk and expense growth when judging Wintrust Financial’s execution.
How Wintrust Financial’s Earnings Outlook Connects To The Story
Wintrust Financial’s narrative projects US$3.5b revenue and US$1.1b earnings by 2029, based on analyst estimates that imply 8.6% yearly revenue growth and an earnings increase of about US$252m from US$847.9m today.
Uncover why Wintrust Financial's fair value indicates a 17% potential upside to its current price, which could narrow quickly if Wintrust Financial keeps executing on this earnings path.
Exploring Other Perspectives
Fair value estimates from the Simply Wall St Community span roughly US$176.20 to about US$297.13 across 2 separate views, so retail opinions on Wintrust Financial already vary widely. Set those pre news valuations against rising Q3 earnings, affirmed common and preferred dividends, and ongoing credit and expense risks, and you are looking at a company where contrasting narratives can coexist. Use that spread as a prompt to test several community viewpoints before deciding how this mix of income, growth initiatives and credit exposure fits your own expectations.
Explore another Wintrust Financial fair value estimate, including one that suggests it could be worth just $176.20.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Wintrust Financial research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Wintrust Financial. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Wintrust Financial's overall financial health at a glance.
Looking for more investment ideas beyond Wintrust Financial?
If Wintrust Financial fits how you think about earnings power, dividends and credit risk, it can help to compare it with other businesses that share some of those qualities but play in different corners of the market.
- If you want income with a sturdier feel to the balance sheet, line up Wintrust Financial against a list of solid balance sheet and fundamentals (24 results) to see which ones better match your comfort level on debt and liquidity.
- If value is your priority, set the current Wintrust Financial story beside a curated 29 high quality undervalued stocks that screens for stronger fundamentals at prices that may look more conservative.
- If you are hunting for ideas that the market may not be focused on yet, broaden your watchlist beyond Wintrust Financial by scanning a 21 high quality undiscovered gems with quality metrics front and centre.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com