
MaxLinear (MXL) Earnings Rebound And Guidance Put Its Valuation Back In Focus
MaxLinear earnings jump and fresh guidance set tone for investors
MaxLinear (MXL) just paired a sharp swing back to profitability in the third quarter with fresh fourth quarter revenue guidance, giving investors a clearer view of where the business is heading next.
The sharp 12.34% one-day share price gain to US$74.67 came after MaxLinear paired this earnings rebound with fresh fourth quarter guidance and an expanded US$200 million revolving credit facility. However, the 30-day share price return is still down 17.03%, while the year-to-date share price return and 1-year total shareholder return both remain very large, signalling strong longer term momentum despite recent volatility.
Scan other chipmakers that show similar earnings and guidance momentum to MaxLinear with our hand picked 55 AI infrastructure stocks.
Bulls point to MaxLinear’s sharp swing back to profit and fresh guidance, while bears highlight the recent share price spike and past losses. Which story do the current valuation signals support next?
Most Popular Narrative: 21% Undervalued
MaxLinear’s most followed narrative pegs fair value at $94.55, well above the latest close at $74.67. This puts the recent earnings jump and guidance into a wider context for how much optimism is already reflected in long term expectations.
Accelerating demand for high-speed data center optical interconnects and next-generation PAM4 DSP solutions (Keystone and Rushmore), supported by robust design win momentum with major module makers and hyperscale customers, positions MaxLinear to capture a significant share of growing global data/AI infrastructure spend, likely driving meaningful revenue growth from late 2025 through 2027.
See why 16 investors see MaxLinear as 21% undervalued.
Result: Fair Value of $94.55 (UNDERVALUED)
Still, the narrative can unravel if MaxLinear remains heavily tied to maturing broadband demand or if pricing pressure from larger, low-cost rivals intensifies.
Find out about the key risks to this MaxLinear narrative.
Another View: MaxLinear looks expensive on sales multiples
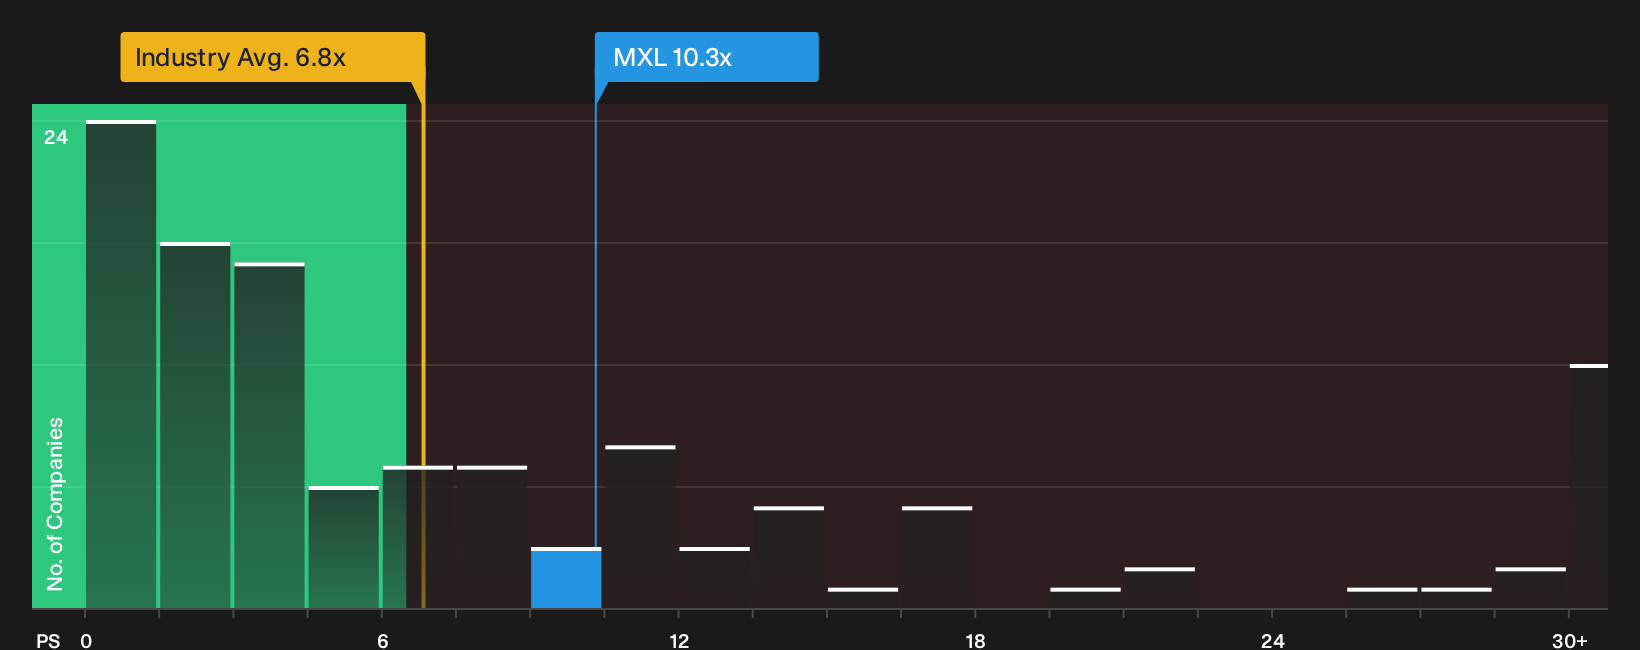
That 21% gap to MaxLinear’s narrative fair value contrasts with a very different signal from simple sales multiples. The stock trades on a P/S of 10.3x compared with 6.8x for the US Semiconductor sector and 5.5x for peers, even though the fair ratio sits higher at 14.8x.
This mix of a rich headline P/S against both industry and peer groups, yet still below the fair ratio, points to valuation risk if sentiment cools and potential room for repricing if the market moves closer to that fair ratio. How you weigh that tradeoff will depend on your own view of the balance between downside risk and potential upside.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals can feel messy, especially when MaxLinear combines strong enthusiasm with clear risk flags. Consider reviewing both sides of the story promptly and ground your own stance in the 1 key reward and 2 important warning signs.
Looking for more MaxLinear investment ideas to compare?
If MaxLinear has your attention, do not stop at one ticker. Broaden your watchlist with a few focused stock ideas that match clear, data driven filters.
- Target quality and value together by scanning companies that screen as potential bargains using our 29 high quality undervalued stocks.
- Prioritise resilience by reviewing a list of solid balance sheet and fundamentals (24 results) so you focus on businesses with financial strength behind their stories.
- Hunt for tomorrow’s leaders before the crowd by tracking a 21 high quality undiscovered gems that many investors have not yet priced in.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com