
Will Revenue Growth Change Vivendi's Narrative
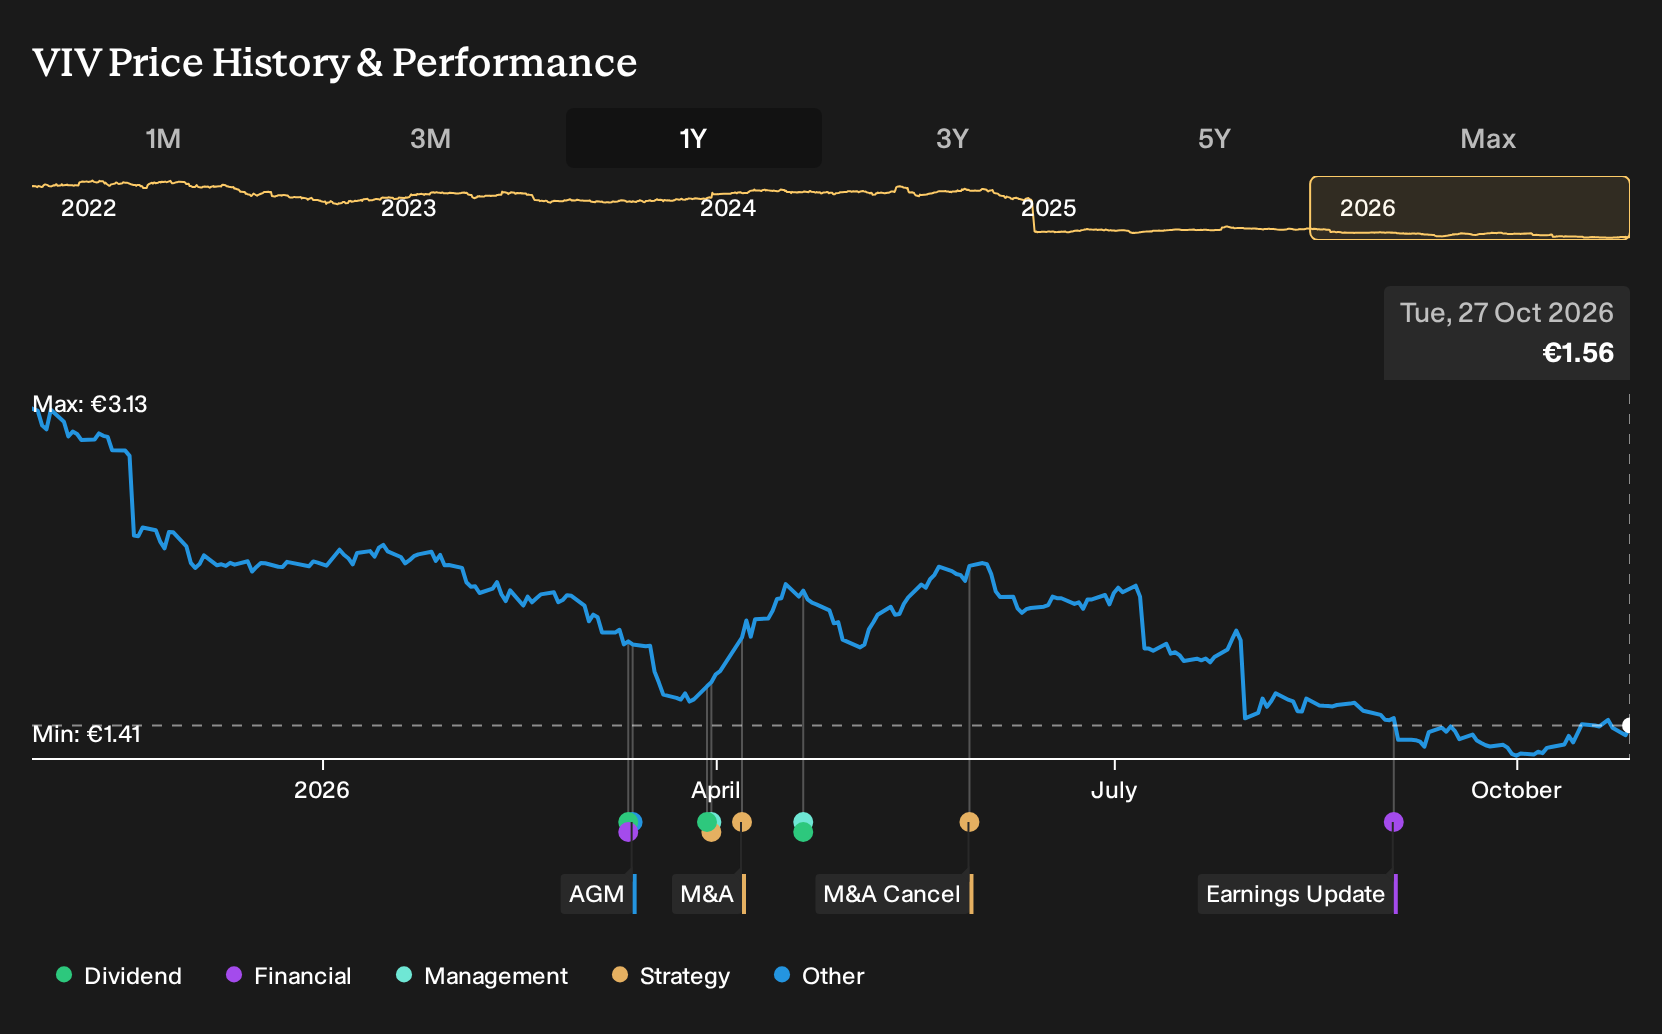
- Vivendi SE reported unaudited revenue of €77 million for the third quarter of 2026, up 13.8% year on year, and €217 million for the first nine months, up 2.1% versus the prior year period.
- This recent revenue uplift provides investors with fresh data on how Vivendi’s content focused portfolio and cost efforts are translating into top line progress.
- We examine how Vivendi’s investment narrative is affected by this 13.8% quarterly revenue rise and what it may signal.
Scan how Vivendi’s latest revenue step up compares with other content focused players by reviewing the hand picked 610 high quality undiscovered gems sitting off most investors’ radar.
Vivendi Investment Narrative Recap
To own Vivendi, you need to believe the content portfolio can turn modest top line progress into sturdier profitability while the balance sheet remains manageable. The 13.8% Q3 revenue uplift to €77 million and €217 million for the first nine months gives some support to that view, but it is a single data point, not a reset.
The near term catalyst still sits in operational follow through. Investors are watching whether cost reductions, Gameloft’s mix toward PC and console titles, and dividend income from the listed portfolio can offset prior revenue softness. The biggest risk remains renewed pressure on margins and earnings if top line momentum stalls again.
Against this backdrop, the earlier disclosure that net financial debt fell from about €2.57b to €1.5b still matters most. That reduction gives Vivendi more room to manage through uneven quarters like the first half of 2026, when revenue declined 3.5% to €140 million and left EBITDA and margins exposed to any misstep.
The latest unaudited revenue update plugs directly into that story. If management can keep debt contained while Gameloft’s €303 million of revenue and record €31 million operating cash flow in 2025 are sustained or improved, then execution on content, cost cuts, and portfolio income stays the key operational catalyst. Any reversal in that mix would quickly bring the leverage and dividend coverage questions back into focus.
Vivendi's current analyst narrative points to forecast revenue of €348.3 million and earnings of €227.1 million by 2029, based on an assumed 4.9% yearly revenue growth rate and an earnings increase of about €211.1 million from earnings today of €16.0 million.
Uncover how Vivendi's fair value indicates a 29% potential upside to its current price, which could narrow quickly if sentiment shifts.
Exploring Other Perspectives
One alternate view puts dividend reliability at the center. Before this Q3 update, the most cautious analysts were working off revenue of €337.0 million and earnings of €227.6 million by 2029 and still landed on a €1.7 target. That group worries portfolio dividends might prove patchy, so your takeaway from Vivendi’s new revenue beat could end up very different from theirs.
Explore 2 other Vivendi fair value estimates, including one that suggests as much as 22% downside from the current price!
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Vivendi research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Vivendi. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Vivendi's overall financial health at a glance.
Looking For More Investment Ideas Beyond Vivendi?
Once you have a view on Vivendi, it can help to stress test that conviction against other opportunities that offer different mixes of value, income, and balance sheet strength. The Simply Wall St Screener is a straightforward way to line up those alternatives side by side and see how they compare on the metrics that matter most to you.
- If you are hunting for quality at a reasonable entry point, line up potential candidates using a 195 high quality undervalued stocks that filters for fundamentals as well as pricing.
- If capital protection sits high on your checklist, start with a 223 resilient stocks with low risk scores that spotlights businesses with stronger financial risk profiles.
- If balance sheet resilience is non negotiable for you, focus on a list of solid balance sheet and fundamentals (207 results) to see which companies carry less financial strain.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com