
Insight Enterprises (NSIT), What Is Behind The Fresh Attention?
Insight Enterprises (NSIT) has been named an OpenAI Advanced Partner, a step that puts its AI consulting, deployment, and managed services relationship with OpenAI in sharper focus for investors.
Recent trading has been strong for Insight Enterprises, with the share price up 8.55% over the past week and 39.97% across the last 90 days, contributing to a 112.42% year to date share price return and a 69.86% total shareholder return over 12 months. This indicates building momentum around the OpenAI partnership and other recent announcements such as the Las Vegas Grand Prix agreement.
Spot 55 AI infrastructure stocks that, like Insight Enterprises, are positioned to support organizations building and scaling advanced AI capabilities on top of modern cloud and data platforms. After a run that strong, driven by the OpenAI partnership and the Las Vegas Grand Prix deal, the question now is simple: Does Insight Enterprises still offer an attractive trade-off between upside potential and downside risk at this price, once valuation enters the frame?Most Popular Narrative: 9% Overvalued
Insight Enterprises closed at $178.35 compared with a widely followed fair value anchor of $163.75. As a result, the current quote sits above that narrative reference point and raises the bar for what needs to go right on execution.
The company’s pivot from legacy partner programs toward higher-margin cloud, managed services and AI-focused consulting is now reinforced by cloud gross profit rising into the high double digits in recent quarters and by higher gross margin guidance. Together these factors point to a sustained mix shift that could support gross margin and adjusted EPS growth.
See why 3 investors see Insight Enterprises as 9% overvalued.
Result: Fair Value of $163.75 (OVERVALUED)
However, relatively flat sales over five years and sensitivity to changes in vendor programs leave Insight Enterprises exposed if higher margin services do not scale as expected.
Find out about the key risks to this Insight Enterprises narrative.
Another View: What Multiples Say About Insight Enterprises
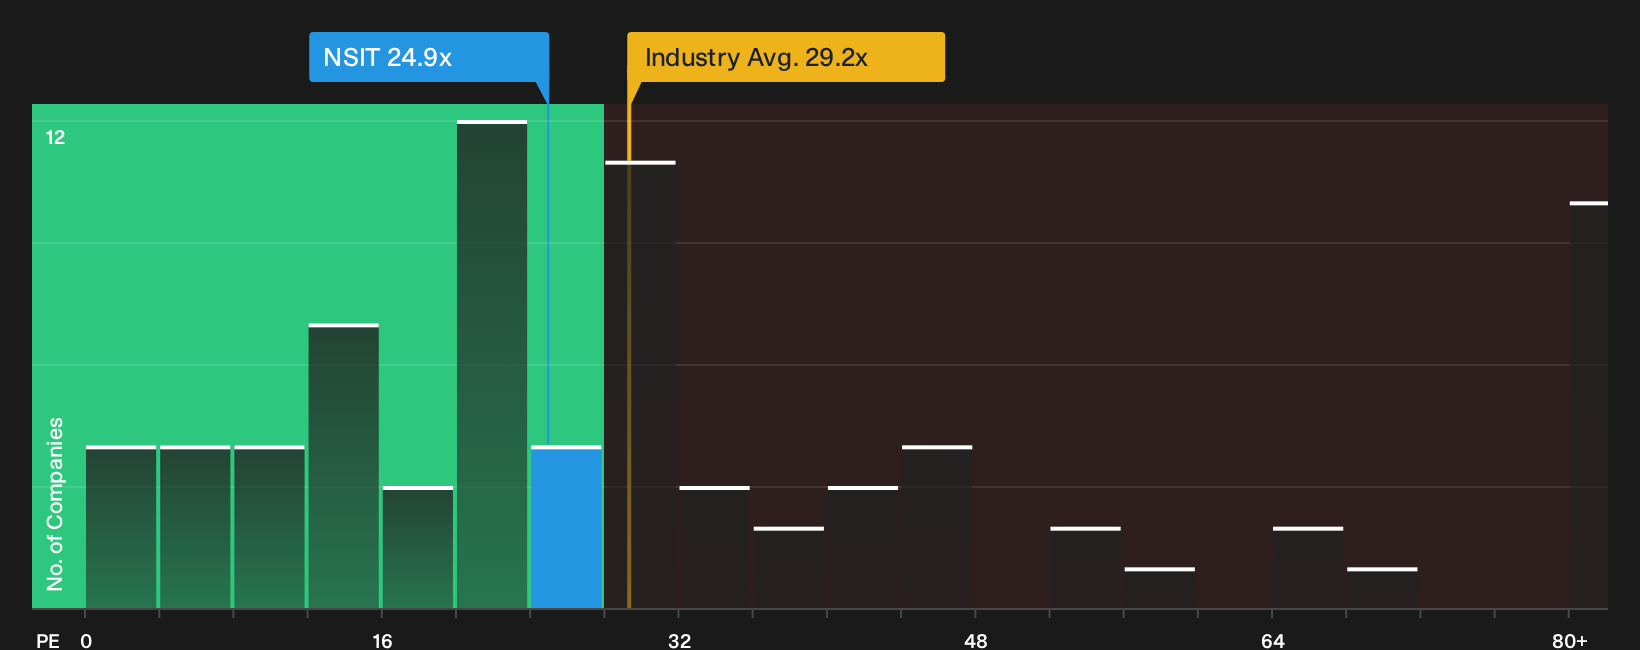
Analyst targets frame Insight Enterprises as 9% overvalued on a fair value line at $163.75. The P/E picture is different. NSIT trades on 24.9x earnings, above a peer average of 18x yet below a 31.1x fair ratio estimate and the 28.7x US Electronic industry level.
So the stock screens richer than closer peers but cheaper than both the sector and the fair ratio the market could move toward. This leaves you asking whether this is valuation risk building in after a sharp run or a premium that still has room to compress upward.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages in the Insight Enterprises story so far. If the balance of risks and rewards feels finely poised, move quickly, review the numbers, and judge the trade-off for yourself with 3 key rewards and 3 important warning signs.
Looking for more Insight Enterprises style investment ideas?
If Insight Enterprises has sharpened your focus on quality and valuation, now is the moment to widen your search before the next wave of opportunities gets crowded.
- Target mispriced quality by scanning a curated 29 high quality undervalued stocks that combines resilient businesses with prices that sit below their assessed worth.
- Prioritise capital strength by filtering for a list of solid balance sheet and fundamentals (24 results) that can better withstand shocks and fund growth without leaning heavily on debt.
- Get ahead of the crowd by checking a focused set of 21 high quality undiscovered gems that pair strong fundamentals with relatively low market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com