
What Comes Next For Texas Instruments After A 90% Gain
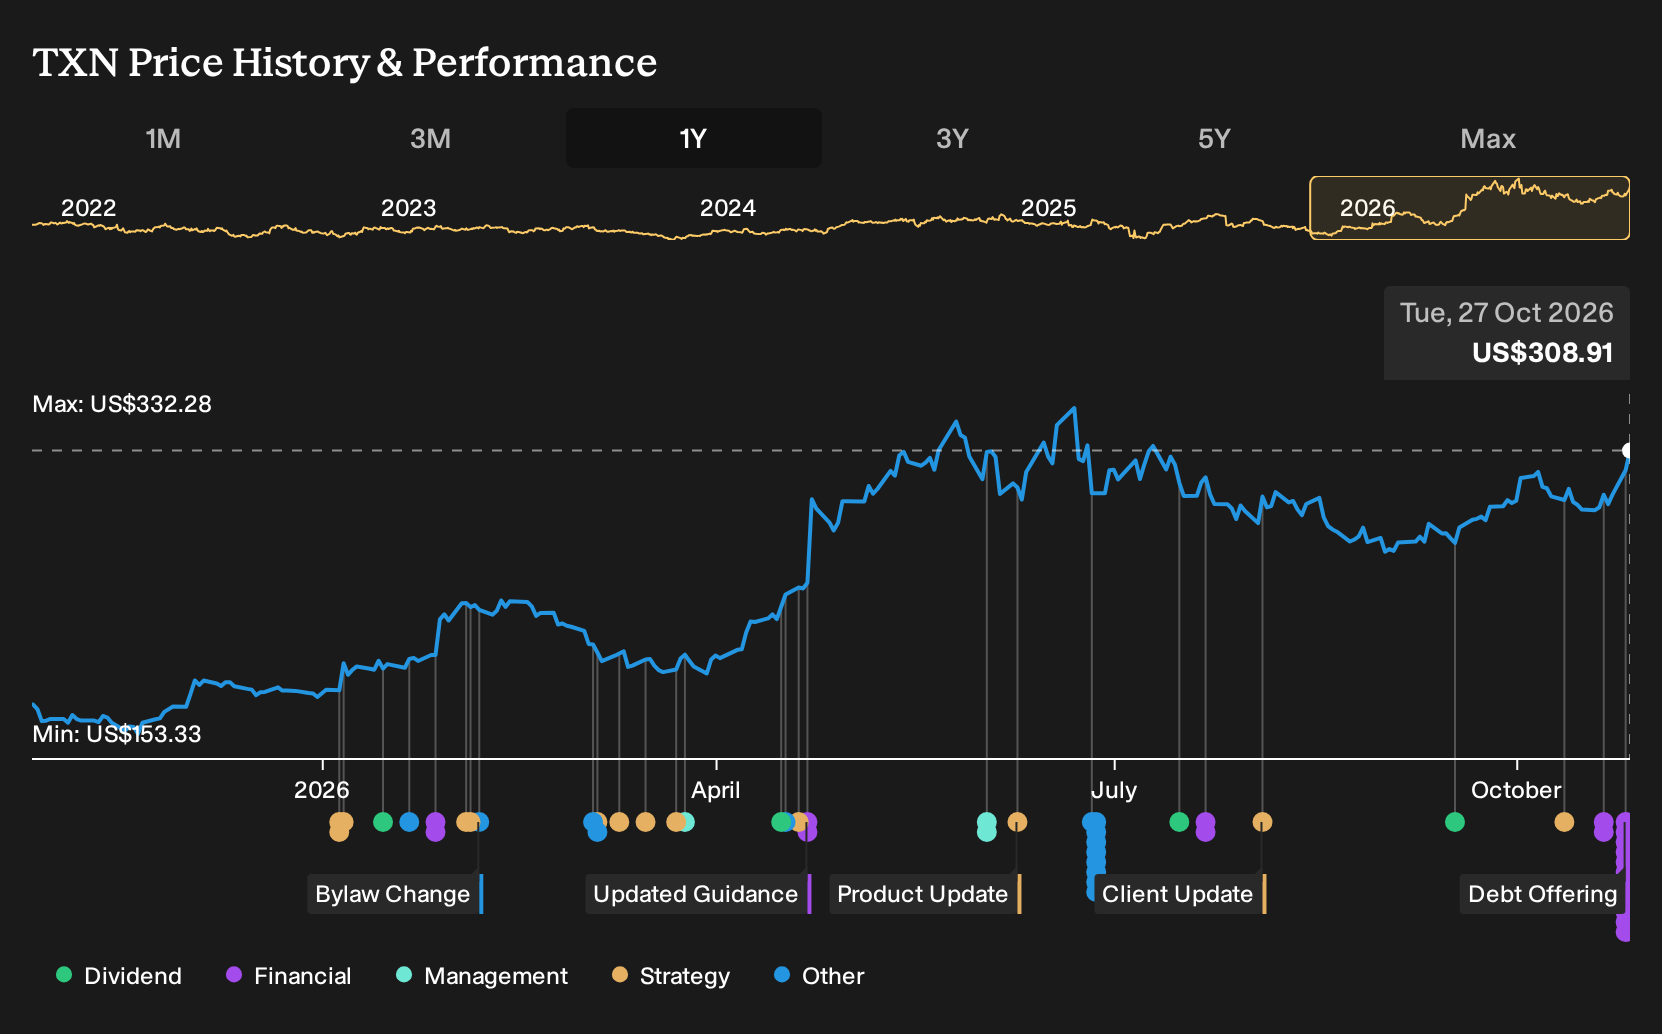
If you had focused only on Texas Instruments' big AI data center headlines this year, it might be easy to forget a quieter but very concrete move. GE Appliances agreed to source one third of the chips for its new Kentucky laundry plant from TI, nearly doubling what it spends with the supplier. Holding Texas Instruments over the past year would have returned 89.9%, including dividends. If that decision sat on your desk back in October 2025, what exactly did you need to believe about TI’s industrial and automotive future to press “buy” before any of this news arrived?
The useful thing about a Narrative is that the reasoning is checkable: the assumptions sit beside the argument, and together they imply an estimated Fair Value you can disagree with.
Texas Instruments is not the only name tied to this theme. Zero in on 55 AI infrastructure stocks and compare how each one is priced.
The Two Texas Instruments Stories Investors Were Weighing
The shares cost US$169 at the start of the period, and Texas Instruments sat between two very different but credible narratives about its future.
On the optimistic side, the October 2025 industrial and automotive thesis put fair value at US$206, which was 21% above the start price. That view rested on rising semiconductor content in factories and vehicles, as well as heavy U.S. 300mm fab investment that could strengthen supply security and support higher margins.
The May 2025 bear case pinned fair value at US$125, which was 26% below the start price. It focused on maturing analog and embedded markets, tougher Asian competitors, and rising compliance and capacity spending that could pressure margins and restrain free cash flow.
What The Texas Instruments Evidence Actually Tested
Texas Instruments’ Q3 2026 update showed revenue at US$6.06b versus US$4.74b a year earlier, with net income at US$2.41b versus US$1.36b. Net margin moved from 28.6% to 39.8%. That pattern supported the optimistic case that industrial, automotive, and data center demand could support higher profitability, although the planned Silicon Labs acquisition added future integration and financing questions.
The lesson is simple. When a story hinges on better margins, treat net margin progression as the key “receipt” and track whether each year’s percentage actually lines up with the original claim.
What Texas Instruments’ Price Already Assumes After The Run
After an 89.9% gain over the past year, Texas Instruments now trades at US$309, well above the selected Narrative’s Fair Value. That Narrative argues the stock already bakes in strong revenue, margin and free cash flow outcomes.
Its central question for you is whether heavy 300mm fab spending truly converts into durable cost benefits and earnings power, or whether higher depreciation and softer end markets blunt that payoff over time.
"Although Texas Instruments highlights long term cost and supply benefits from its more than US$20b 300mm U.S. fab buildout and higher internal production, the July 2026 concerns about rising depreciation and the potential for weaker industrial and automotive demand suggest the expanded footprint could compress gross margins and limit the uplift to net earnings if utilization falls short of expectations."
One Narrative has put a figure on that disagreement. → See the Narrative with its lower Fair Value, assumptions and all
Looking Past Texas Instruments
Texas Instruments anchors one side of the story. Your next decision is whether to look deeper into the plumbing of AI and data.
All that extra computing needs to be linked, stored, and managed reliably. Another business concentrates on the connective tissue, from high speed networking to private cloud software that keeps workloads flowing.
It focuses less on eye catching chips and more on underlying digital infrastructure that keeps them useful.
If demand for processing spreads further, the question shifts. How might the suppliers of that connective fabric see their role change?
The case is on the record, with the assumptions it rests on. → See the Narrative that values this company 90% above its price
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com