
SiteOne Landscape Supply (SITE) Heads Into Q3 Earnings, Is It Still 14% Undervalued?
SiteOne Landscape Supply (SITE) heads into its Q3 report this week with fresh attention after previously missing revenue, EPS, and EBITDA estimates, while current forecasts point to only modest top-line progress.
Short term momentum has picked up for SiteOne Landscape Supply, with a 1-day share price return of 1.50% and a 30-day share price gain of 12.84%, even though the year-to-date share price return is down 17.62% and the 5-year total shareholder return has declined 57.22%.
Scan how traders are positioning around SiteOne Landscape Supply ahead of earnings by lining it up against our hand picked 29 high quality undervalued stocks in similar segments.
SiteOne Landscape Supply runs a broad, specialized wholesale network that many contractors rely on, yet the share price only just bounced after a long slide. Is that business strength already fully reflected in today’s valuation, or not?
Most Popular Narrative: 14.5% Undervalued
At a last close of $103.03 versus a narrative fair value of $120.50, the most followed view sees room above where SiteOne Landscape Supply currently trades, with that gap depending on whether management can keep executing its playbook.
Increased emphasis on high-margin private label brands and product mix optimization, supported by private brands moving from 14% to roughly 15% of sales, Pro-Trade products nearing $200m and rising nearly 50% in Q2 2026, and a plan to lift private-brand penetration by about 100 basis points of sales per year toward a 25% to 30% mix with an estimated 20 basis point annual contribution to gross margin, is supporting EBITDA margin expansion and earnings growth.
See why 2 investors see SiteOne Landscape Supply as 14% undervalued.
Result: Fair Value of $120.50 (UNDERVALUED)
Still, the narrative around SiteOne Landscape Supply could shift quickly if weak volumes in key Sunbelt markets persist, or if organic revenue and EPS remain flat for longer than analysts expect.
Find out about the key risks to this SiteOne Landscape Supply narrative.
Another View: SiteOne Landscape Supply Looks Expensive On Earnings
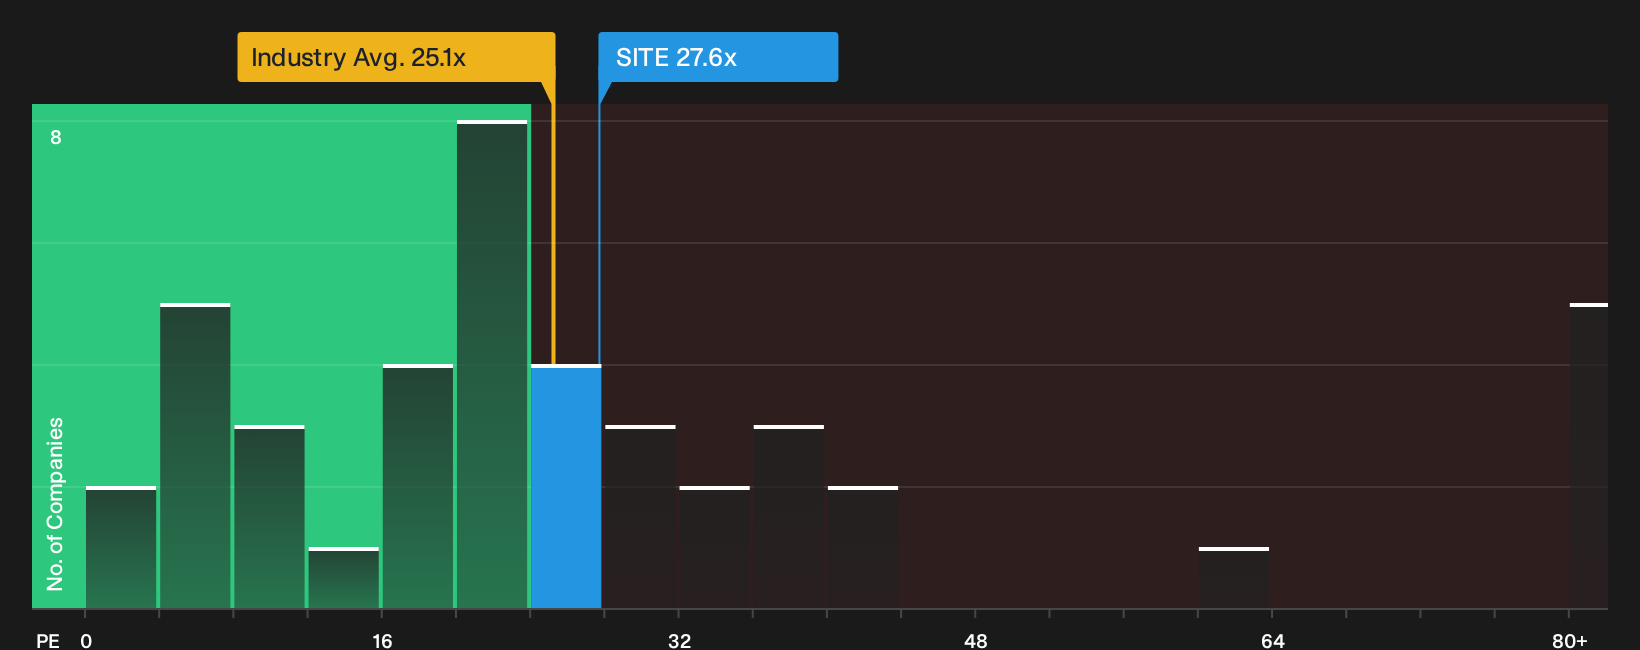
The fair value narrative paints SiteOne Landscape Supply as 14.5% undervalued at $120.50, yet the current P/E of 27.6x tells a tougher story. It sits above the estimated fair ratio of 22.5x and above the US Trade Distributors average of 24.4x, even though it is below a lofty 68.5x peer average. That gap suggests valuation risk if sentiment or earnings expectations cool from here, so which signal do you trust most?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on SiteOne Landscape Supply can create noise. Move quickly, check the underlying data yourself, and see what the market might be missing in the 2 key rewards.
Looking for more investment ideas beyond SiteOne Landscape Supply?
If SiteOne Landscape Supply has your attention, do not stop here. Broaden your watchlist with fresh ideas that could sharpen your next move.
- Target potential mispricing by scanning companies that combine quality fundamentals with attractive valuations through the 29 high quality undervalued stocks.
- Strengthen portfolio resilience by reviewing a 30 resilient stocks with low risk scores that highlights businesses with more defensive characteristics and tempered risk scores.
- Hunt for overlooked opportunities by checking a 21 high quality undiscovered gems that surfaces lesser-known stocks with solid underlying fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com