
Antero Resources (AR) Stock Looks Undervalued As Its 101% Five Year Run Continues
Antero Resources has logged a strong multiyear share price run, so the key issue now is whether the current US$42.10 price is adequately supported by the earnings the business produces. With the spotlight on past returns, the real decision point for you is how those profits stack up against what the market is paying today.
- Over the past 5 years the stock has delivered a total return of 101.1%, which puts real pressure on the question of whether its earnings profile justifies that kind of gain.
- The business model is tightly linked to cash flow from energy production, so any change in drilling economics or cost discipline can feed directly into the earnings power that backs the current valuation.
- There is a second opinion on Antero Resources worth weighing. See what analysts think Antero Resources's shares could be worth.
The stock's next move may depend on whether Antero Resources' current earnings are strong and durable enough to support the price investors are paying today.
You can test the same earnings question you are asking of Antero Resources against a wider field by scanning 29 high quality undervalued stocks.
Does Antero Resources Look Undervalued on Earnings?
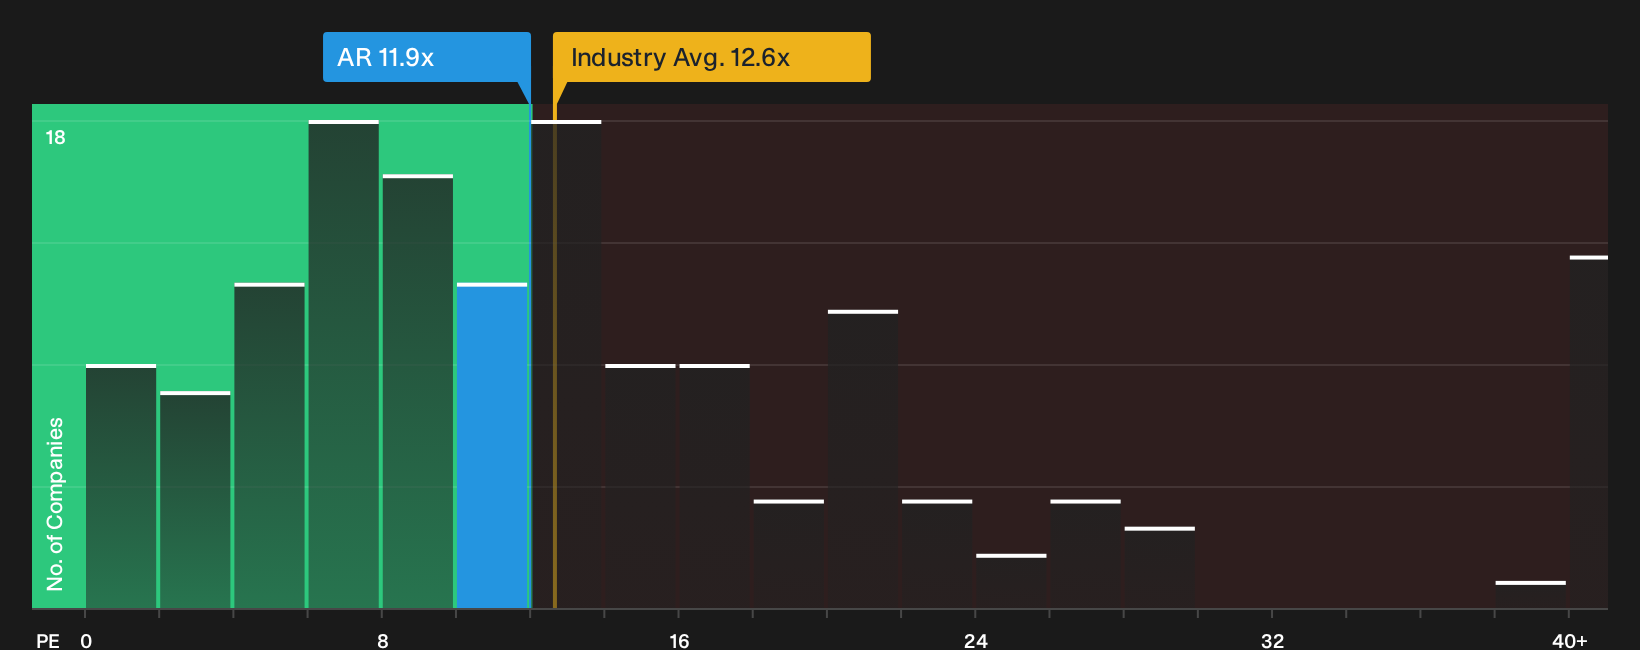
The P/E ratio is a useful lens for Antero Resources because investors often anchor energy producers to the earnings power of their existing asset base. At a current P/E of 11.9x, the stock trades slightly below the Oil and Gas sector average of about 12.6x and also a bit under the peer group on roughly 12.6x, so the market is not attaching a premium tag to the current earnings stream.
The tailored fair multiple for Antero Resources, which reflects its specific growth outlook, margins, size and risk profile, sits above where the shares change hands today. That gap points to an undervalued reading on this earnings yardstick, with the market pricing each dollar of profit more cautiously than the framework suggests. For anyone already following the story, the key question is whether the quality and stability of those earnings justify that lower P/E or whether the discount is wider than the business fundamentals warrant. Explore the numbers behind Antero Resources's P/E valuation.
The Antero Resources Narrative: What Would Justify Today's Price?
Narratives for Antero Resources pick up where the P/E puzzle leaves off by spelling out which expectations for growth, margins and earnings would need to hold for the stock to be worth materially more or less than it is today, and they sit on Simply Wall St's Community page. Each one treats fair value as a thesis about Antero Resources' business that you can watch over time, rather than a single valuation snapshot.
Community views on Antero Resources are split between export driven upside and concern that cost and margin delivery may fall short of the promise.
Bull case: 16% undervalued
"Antero Resources focus on liquids rich production combined with firm transport to premium Gulf Coast and export outlets is now complemented by a detailed plan to cut total cash costs by over 25% to about US$2.00 per Mcfe by year end 2028...
Discover why this Narrative puts Antero Resources at 16% undervalued.
Bear case: 5% overvalued
"Although Antero Resources highlights a multi year plan to reduce cash costs to around US$2.00 per Mcfe by year end 2028, the company’s five year revenue CAGR of 5.6% and a 5.1 percentage point decline in EBITDA margin over the last year indicate that any future cost savings may be absorbed by rising expenses...
Explore why this Narrative puts Antero Resources at 5% overvalued.
Antero Resources: why the people in charge could matter more than the current share price
Price and earnings only tell part of the story for Antero Resources, because the judgement and incentives of the executives steering the business can pull those numbers in very different directions over time. See who runs Antero Resources and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com