
Is Crocs (CROX) Still Undervalued After Its 38% Run?
Crocs has delivered a 37.8% gain over the past year, which puts a spotlight on a simple question for anyone looking at the stock today. Is the current US$119.50 share price adequately grounded in the cash the business is expected to generate?
- The 37.8% one year return has rewarded recent holders, which raises the stakes on whether that move is in line with what Crocs' future cash flows can reasonably support.
- Fresh attention on the company's tax arrangements in Malta and a more optimistic sell side view on its growth path both feed directly into expectations for how much cash Crocs can keep and for how long.
- Prefer to judge Crocs on earnings? See what Crocs's 9.7x P/E says about the price.
The issue now is whether the cash flows implied by the Discounted Cash Flow (DCF) intrinsic value estimate line up with where Crocs shares trade today.
If you are weighing Crocs against other ideas that are also analysed on their fundamentals, a focused stock screen can be a useful next step. You could start with 29 high quality undervalued stocks.
Does Crocs Look Undervalued on Cash Flow?
The Discounted Cash Flow (DCF) model used here starts with what Crocs already produces in cash. Over the last twelve months the business generated about $688.7 million in free cash flow, and the forecast path assumes this cash generation broadly holds at current levels rather than surging or collapsing.
Analyst projections feeding into the DCF keep free cash flow in a fairly tight range through the next decade, so this is being treated more like a mature cash engine than a high growth story. Because the Barclays upgrade points to a more upbeat growth narrative while the DCF leans on steady cash flows instead of aggressive expansion, the result is that the model still places Crocs' estimated intrinsic value substantially above the current US$119.50 share price. Find out what Crocs could be worth using our Discounted Cash Flow (DCF) estimate.
The Crocs Narrative: What Would Justify Today's Price?
Narratives on Crocs pick up where the DCF puzzle leaves off by spelling out which mix of future growth, margins and earnings would need to hold for the shares to be worth materially more or materially less than today’s price on Simply Wall St’s Community page. Each scenario ties a fair value to a particular path for Crocs' potential catalysts and risks, so you can track over time which version of events is actually unfolding.
Community views on Crocs split between a cash rich expansion story and a margin risk overhang that could cap what the shares are worth.
Bull case: 14% undervalued
"Expansion of Crocs beyond the Classic Clog into sandals approaching $0.5b in expected 2026 revenue, new lifestyle franchises such as Ballet Flat and Mellow, and HEYDUDE extensions in sandals, work and boots points to a broader portfolio that can support a wider customer base and more stable revenue…"
Discover why this Narrative puts Crocs at 14% undervalued.
Bear case: 26% overvalued
"Enterprise adjusted gross margin already declined 90 basis points in Q1 2026 and 170 basis points in Q2 2026 as tariffs and adverse product and brand mix took hold…"
Explore why this Narrative puts Crocs at 26% overvalued.
One more Crocs check that sits alongside the cash flow story
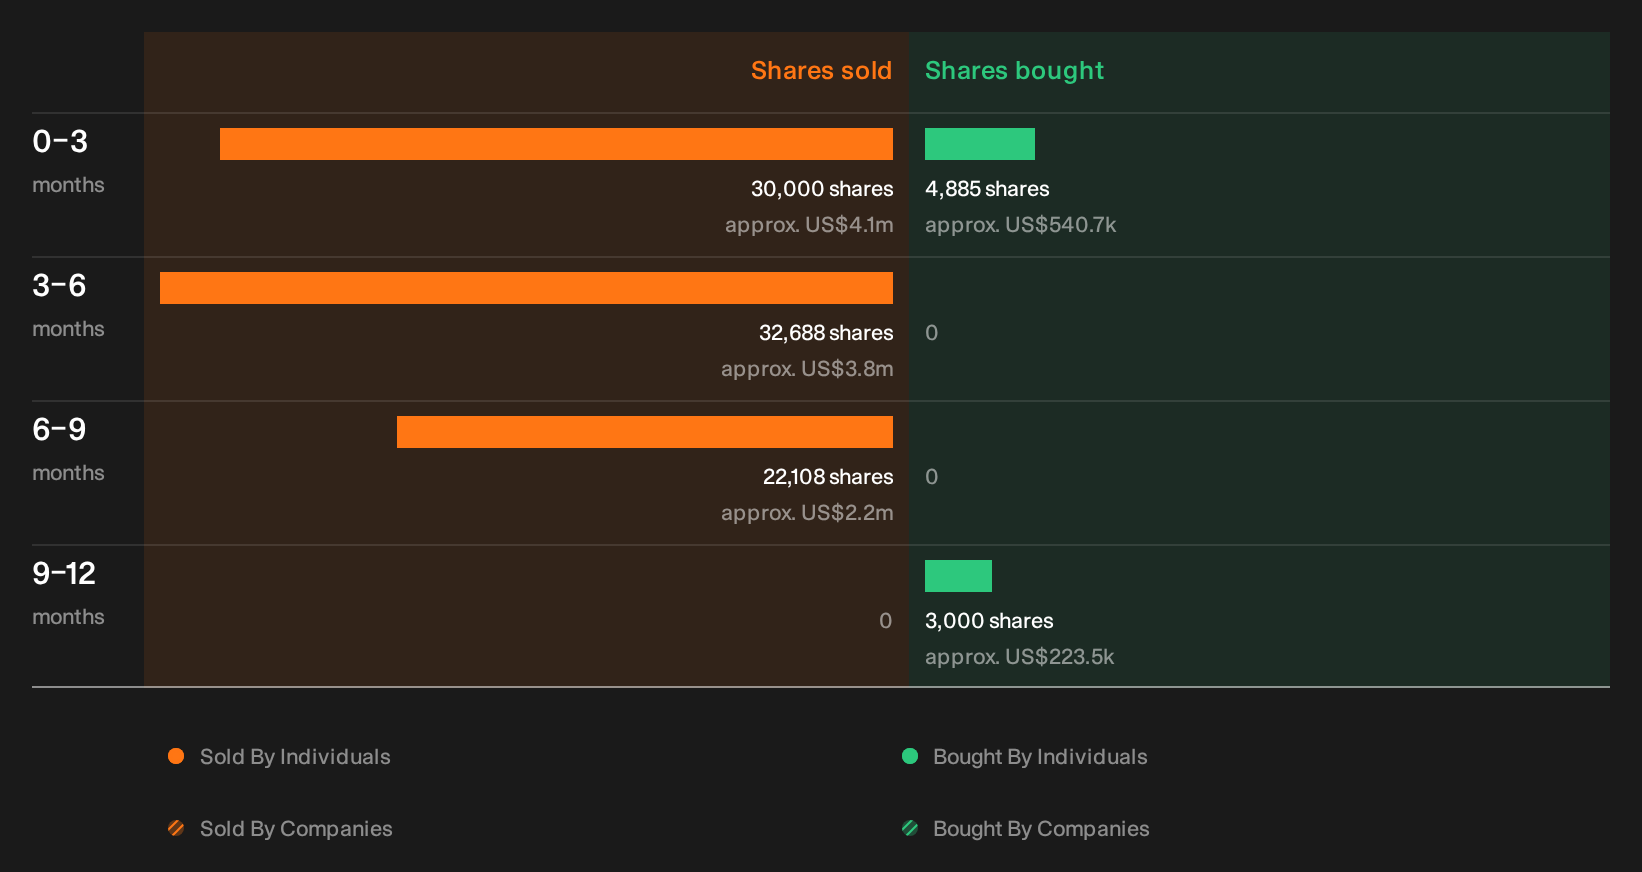
Price and cash generation tell a lot about Crocs, but our checks also highlight recent share sales by people inside the business, with the individuals, size of sales and possible reading of those moves left for you to review next. See the recent insider selling flagged for Crocs.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com