
Is Rush Enterprises (RUSH.A) Cheap On Q3 Earnings, Dividend And Joint Venture News?
Rush Enterprises (RUSH.A) reported its third quarter 2026 earnings, posting higher revenue, net income and earnings per share, along with a dividend and a new refrigerated transport joint venture.
Rush Enterprises shares trade at US$45.48, with the stock down 5.2% on a 1 month share price return and 16.4% on a 3 month share price return. However, it shows a 26.1% year to date share price return and a 38.2% 1 year total shareholder return, which points to longer term momentum holding up despite recent weakness around earnings and regulatory uncertainty.
Scan how Rush Enterprises compares with other commercial vehicle and capital goods plays by reviewing the curated list of solid balance sheet and fundamentals (24 results), which may be better aligned with your risk and quality filter.
After a strong year for Rush Enterprises despite the recent pullback, the key question is whether most of the easy gain is already in the rear-view mirror or if the current price still leaves room on the table when you look at valuation.
Preferred P/E of 20x: Is it justified?
On simple headline numbers, Rush Enterprises changes hands at a P/E of 20x, which lines up with a share price of $45.48 and screens as relatively undemanding compared with several peers in the Trade Distributors space.
The P/E ratio compares what investors are paying today for each dollar of current earnings. For a commercial vehicle retailer like Rush Enterprises, that link to profit matters because the group generates income not just from truck sales, but also from higher margin services such as parts, repairs, leasing and insurance. These activities can help smooth out more cyclical areas of the operation.
Against both peers and an internally estimated fair P/E level, the current tag looks restrained. Management is expected to grow earnings at 12.45% per year and revenue at 9.9% per year, which is slower than some broader US benchmarks. Yet the stock trades on a P/E that is lower than the US Trade Distributors industry average of 24.4x and below the peer average of 67.2x. The ratio also sits slightly beneath an estimated fair P/E of 20.9x. This points to a price level the market could move towards if expectations hold steady.
The combination of trading at comparatively low value relative to both peers and the sector, plus alignment with that 20.9x fair ratio, indicates that investors are not paying a particularly elevated price for Rush Enterprises earnings at current levels, even after strong 1 year and multi year shareholder returns.
Explore the SWS fair ratio for Rush Enterprises.
Result: Price-to-earnings of 20x (UNDERVALUED)
Still, Rush Enterprises faces real pressure points if truck demand cools or regulatory changes lift compliance costs faster than service income can offset them.
Find out about the key risks to this Rush Enterprises narrative.
Another View: SWS DCF Says Rush Enterprises Looks Expensive
The story changes once you switch from the P/E lens to the SWS DCF model. On that framework, Rush Enterprises has an estimated future cash flow value of $19.17 per share against a current price of $45.48, which flags the stock as materially overvalued on cash flows.
A big gap like that does not automatically make the P/E view wrong. It simply indicates that the current share price reflects assumptions of stronger cash generation than the DCF model incorporates. This raises the question of whether earnings quality or long term growth can comfortably bridge that distance.
Look into how the SWS DCF model arrives at its fair value.
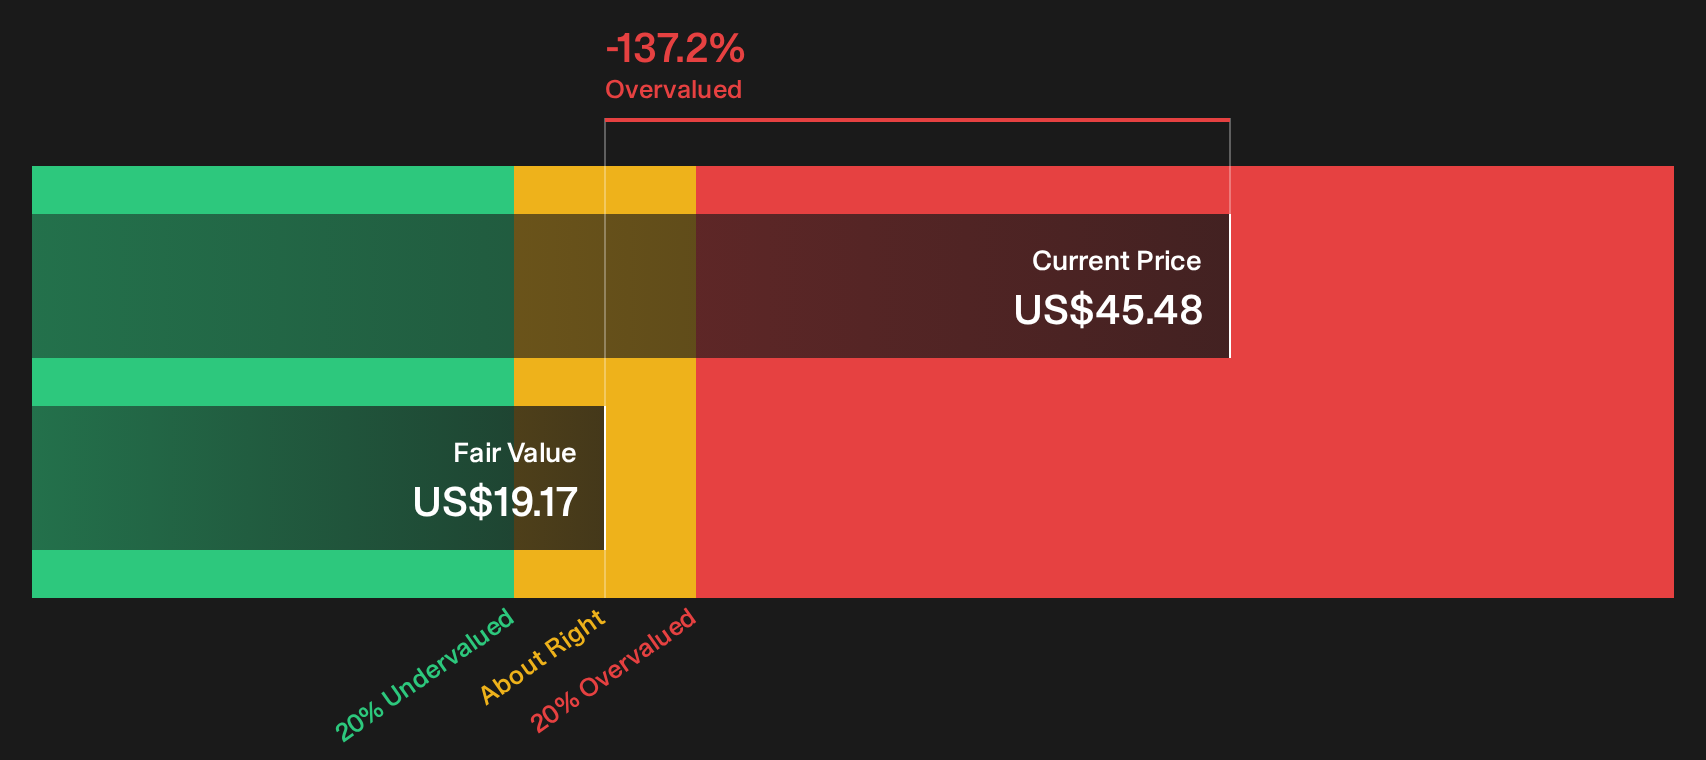
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Rush Enterprises for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 29 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Rush Enterprises so far. If you want to move quickly and form your own view, start by weighing the 4 key rewards and 1 important warning sign
Looking for more Rush Enterprises investment ideas?
Do not stop with Rush Enterprises. If you want a broader watchlist that fits your style, use the Simply Wall Street screener to quickly surface focused sets of opportunities that match clear fundamental filters.
- Target value first by scanning companies that combine quality fundamentals with restrained pricing through the 29 high quality undervalued stocks.
- Prioritise resilience by filtering for businesses with stronger balance sheets using the list of solid balance sheet and fundamentals (24 results).
- Hunt for lesser known potential by reviewing the 21 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com