
How Investors Are Reacting To Northland Power (TSX:NPI) Full Turbine Installation
- Northland Power reported that all 73 turbines at its 1.0 GW Hai Long offshore wind project in the Taiwan Strait are now installed and producing electricity. Construction costs were described as aligned with original expectations, and final permitting is still targeted for the first half of 2027.
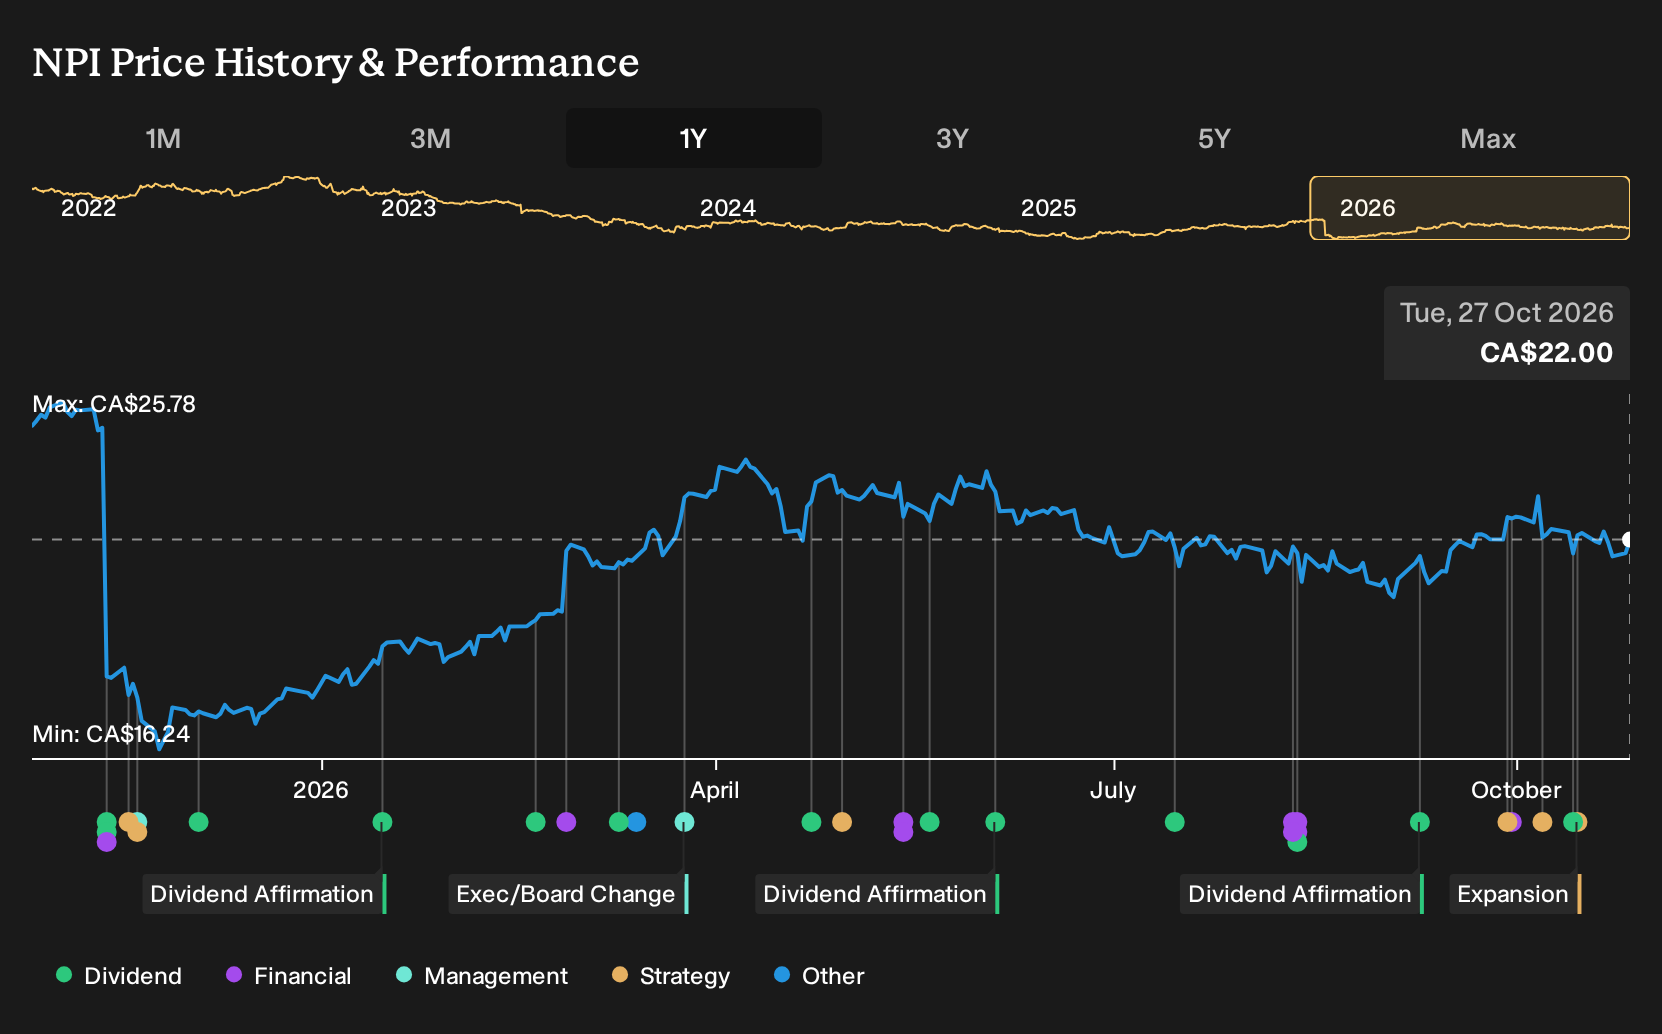
- The Hai Long project, backed by a 30 year offtake agreement and expected to supply power for more than one million Taiwanese households, is positioned to provide contracted cash flow alongside Northland Power’s affirmed monthly dividend of C$0.0600 per share announced for November 2026.
- We will now assess how Northland Power’s investment narrative could be influenced by Hai Long’s full turbine installation and contracted revenue profile.
Northland Power Investment Narrative Recap
To be a shareholder in Northland Power you need to believe that large offshore wind and storage projects can move from a heavy build phase to stable contracted cash flow over time. Hai Long reaching full turbine installation reduces one piece of construction risk, although other projects and the balance sheet still matter more for the broader build out story.
The key short term catalyst remains execution on large assets reaching full commercial operation while keeping capital needs contained enough to avoid fresh equity. The biggest near term risk is still cost or timing issues across the wider project slate that could pressure operating cash flow coverage of debt and the dividend.
The Hai Long construction update ties directly to that mix of risks and catalysts. Management previously indicated that weaker pre completion revenues could require additional equity for the project, which would be dilutive. With all turbines now producing, that specific concern appears less acute, even though final permitting is still pending into the first half of 2027.
Alongside this, the reaffirmed monthly dividend of C$0.0600 per share for November 2026 keeps the income angle at the forefront for Northland Power. For you as an investor, the key tension lies between a payout that is not well covered by current earnings and a pipeline where execution and contracted revenue, especially from Hai Long, need to improve cash generation and support that distribution over time.
What The Hai Long Milestone Means For Northland Power’s Forecasts
Northland Power’s narrative projects CA$2.8b revenue and CA$433.7m earnings by 2029. This rests on analysts assuming 3.4% yearly revenue growth and an earnings swing of about CA$582m from a CA$148.2m loss today to the 2029 consensus earnings level.
Uncover why Northland Power's fair value indicates a 21% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One alternative view focuses on Hai Long execution risk rather than its contracted upside. The most cautious analysts were only pencilling in about CA$2.5b of revenue and CA$346.4m of earnings by 2029 for Northland Power before this milestone. You can treat today’s turbine update as a fresh data point that might eventually shift those expectations.
Explore 2 other Northland Power fair value estimates, including one that suggests it could be worth just CA$26.71!
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis.
- A great starting point for your Northland Power research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Northland Power. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Northland Power's overall financial health at a glance.
Looking For More Investment Ideas Beyond Northland Power?
If Hai Long has sharpened your view on contracted renewables and you want to broaden your watchlist, it can help to compare Northland Power with other businesses that share some of the qualities you care about most, whether that is valuation, stability or income.
- For investors who care most about paying a sensible price for quality, start by scanning 3 high quality undervalued stocks that combine supportive cash flows with balance sheets analysts rate highly.
- If resilience matters more to you than rapid expansion, narrow your search to a 8 resilient stocks with low risk scores that screens for businesses with lower risk scores and more predictable fundamentals.
- Income focused investors who prize reliability over excitement can review a 3 dividend fortresses that target companies with yields of 5% or more backed by established payout records.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com