
Does Strong Earnings Report Change The Bull Case For Commercial Metals Stock (CMC)?
- Commercial Metals reported fourth-quarter 2026 sales of US$2,658.33 million and net income of US$212.52 million, with full-year sales of US$9,393.9 million and net income of US$655.85 million, all from continuing operations.
- The full-year basic earnings per share from continuing operations reached US$5.92 compared with US$0.75 a year earlier, highlighting a sharp shift in reported profitability that sheds light on how Commercial Metals operational model is translating into bottom-line results.
- We will now look at how Commercial Metals investment narrative is affected by this sharp full-year earnings step up.
Scan how Commercial Metals earnings compare with peers and identify other steel and materials stocks with resilient balance sheets using our curated list of solid balance sheet and fundamentals (24 results).
Commercial Metals Investment Narrative Recap
To own Commercial Metals, you need to be comfortable with a steel producer that leans heavily on project activity in North America and on execution of its Transform, Advance, Grow program and Construction Solutions mix shift. The sharp move in full year earnings to US$655.85 million and basic EPS of US$5.92 shows what the operating model can produce in a favourable setup.
In the short term, the key swing factor is how mill volumes and pricing hold up if construction awards soften due to tariffs or interest rates. The main risk is that less visible parts of the portfolio or higher capital needs dilute the earnings and free cash flow profile that many investors are watching closely.
For this earnings print, the most relevant element is management’s earlier guidance that the TAG program aims for more than US$350 million of gross run rate EBITDA benefits by fiscal 2027, with over US$200 million framed as durable margin uplift. The latest results provide additional context on how far Commercial Metals has already progressed toward that ambition.
In terms of potential catalysts, the Arizona 2 micro mill ramp and the planned hot commissioning of the West Virginia micro mill in late summer 2026 sit alongside this earnings update. Higher utilisation and a fully built out long products network could influence volumes and mix at the same time investors are reassessing what this year’s earnings level implies for Commercial Metals from 2027 onward.
Commercial Metals Analyst Assumptions and Valuation Setup
Analysts are effectively asking investors to think about Commercial Metals as a business that can compound its revenue at 6.0% a year while holding most of its current profitability. The forecast points to earnings of US$687.8 million by 2029 on profit margins that are expected to ease slightly from 6.7% today to 6.5% over roughly three years, which keeps the focus on execution rather than aggressive margin expansion.
On earnings, the consensus framework moves from about US$595.1 million of profit today to that US$687.8 million outcome in 2029. That is an earnings increase of roughly US$92.7 million over the period, paired with an earnings per share expectation of US$6.19 as analysts also model a small 0.31% annual decline in the share count through buybacks.
The Commercial Metals narrative points to forecast revenue of about US$10.5b and expected earnings of US$687.8 million by 2029. This setup implies 6.0% yearly revenue growth and an earnings increase of roughly US$92.7 million from current earnings of about US$595.1 million.
Those future figures are then linked to a P/E multiple of 16.9x on the 2029 earnings estimate, compared with about 11.8x today. The analysts’ price target of US$79.36, bracketed by a bullish case at US$88.0 and a more cautious view at US$68.0, flows from that combination of mid single digit annual revenue growth, modestly lower margins and a higher valuation multiple than the stock currently carries.
Commercial Metals investors weighing this framework can stress test three moving parts. The first is whether a 6.0% top line growth rate over the next few years feels reasonable for a company with this exposure to North American construction activity and mill volumes. The second is whether a small step down in profit margin to 6.5% aligns with personal expectations for mix, cost discipline and any future pricing pressure. The third is whether a 16.9x P/E on those 2029 earnings feels acceptable when set against both the company’s own history and the current 19.3x P/E cited for the wider US metals and mining group.
Uncover how Commercial Metals' fair value indicates a possible 25% upside to its current price before the market closes that gap.
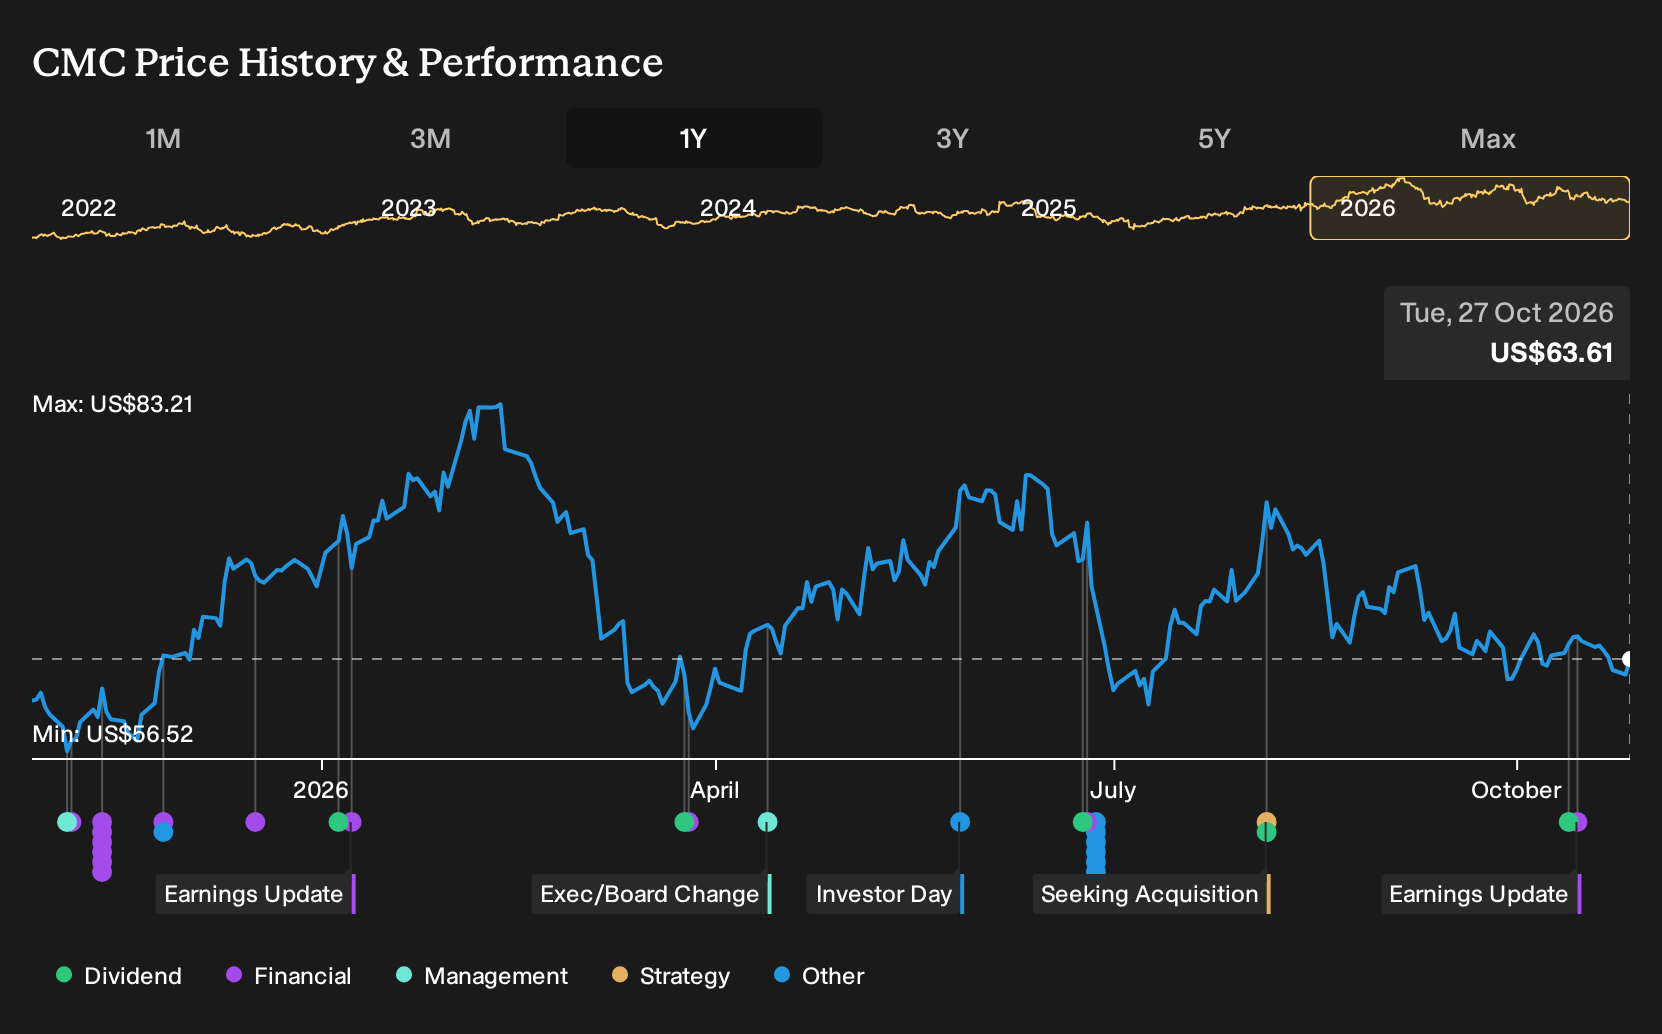
Exploring Other Perspectives
For Commercial Metals, the bearish twist in the alternate view leans heavily on scrap cost spikes and mill outages that could keep margins under pressure. Those analysts were pencilling in roughly US$10.7b of revenue and US$677.5 million of earnings by 2029, which supports a lower US$70.0 target and shows how sharply opinions can differ. Use this earnings release as a fresh data point, and compare several narratives before deciding which version of the story you find most convincing.
Explore 3 other Commercial Metals fair value estimates, including one that suggests it could be valued at $70.00.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Commercial Metals research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Commercial Metals. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Commercial Metals' overall financial health at a glance.
Looking for more Commercial Metals investment ideas?
If this Commercial Metals update has sharpened your view on the steel sector, you can widen the net and pressure test that thinking against other businesses using the Simply Wall St screener.
- For investors who want potential mispricing backed by fundamentals, scan a curated set of 29 high quality undervalued stocks that combine quality metrics with compressed P/E ratios.
- If capital preservation is high on your list, focus on steadier profiles by filtering for 30 resilient stocks with low risk scores that score well on balance sheet strength and earnings stability.
- To cast a wider net beyond well known tickers, broaden your watchlist with 21 high quality undiscovered gems that pair solid financials with relatively low market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com