
What Investors Got Wrong About Olin Before The Fall
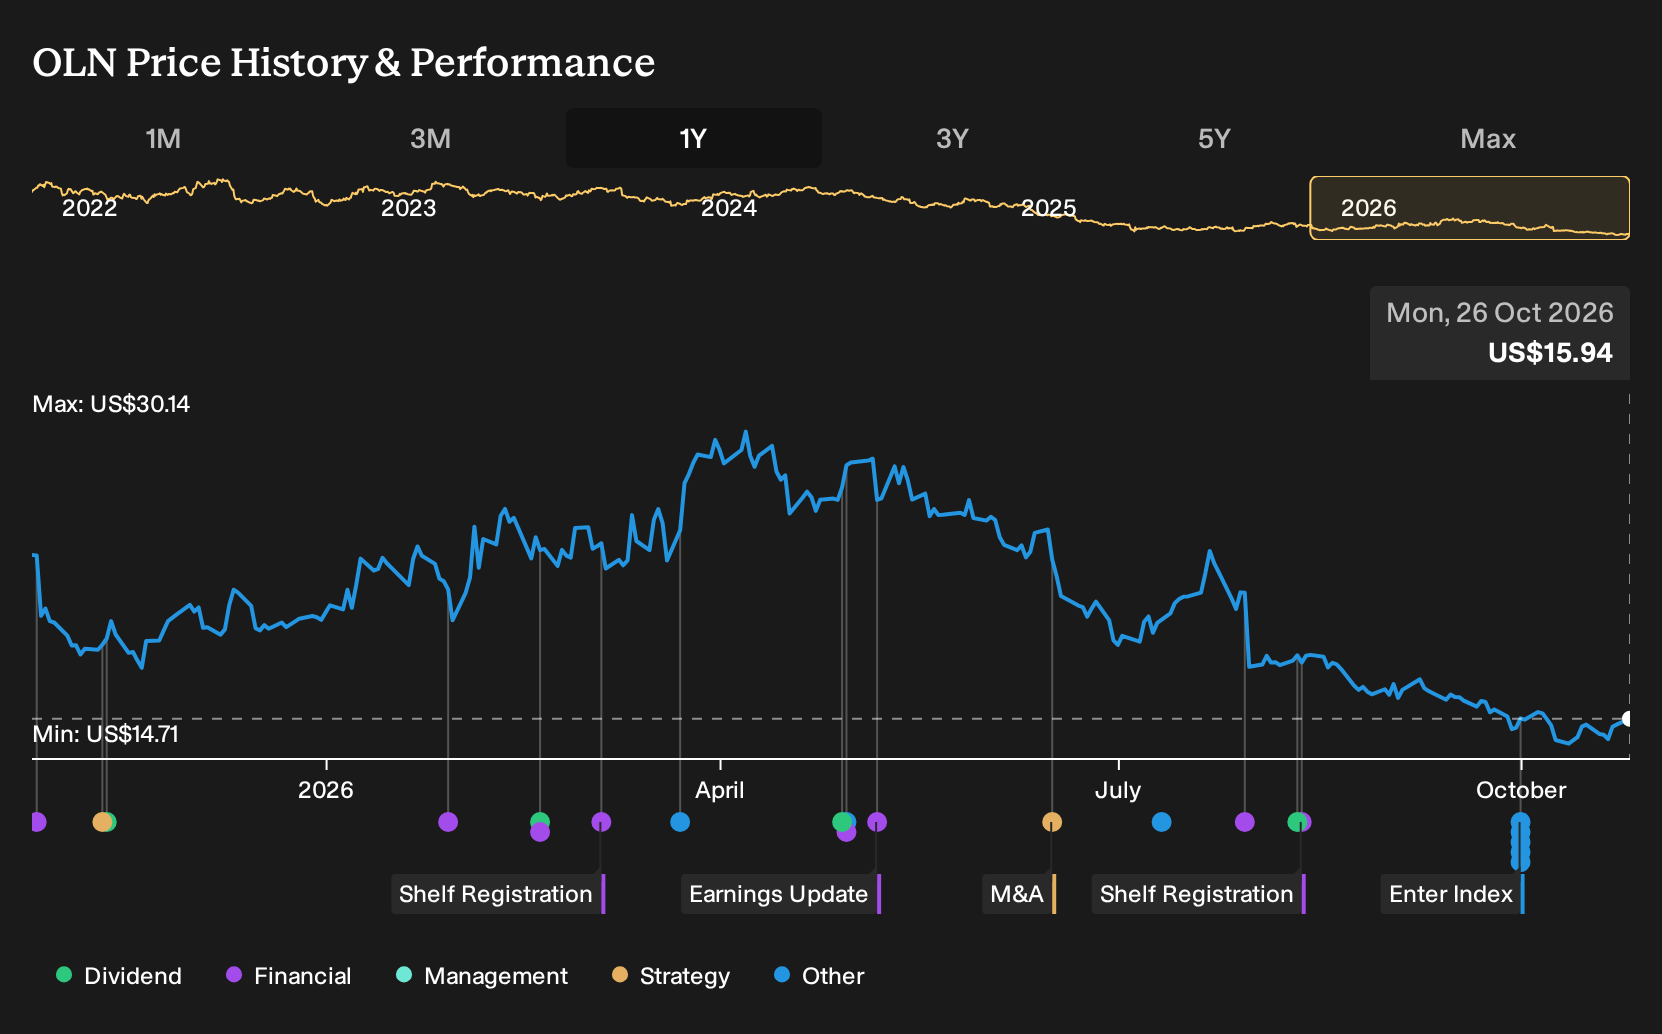
If you had decided on 26 October 2025 to sit out Olin and focus elsewhere, the choice might not have felt dramatic at the time. For Olin shareholders, the loss over the past year was 31.2%, including dividends. Over that same stretch, investors watched a proposed all stock merger with Huntsman advance, fresh losses reported, and multiple law firm investigations open. Looking back, which assumption about Olin’s cyclicality, leverage to PVC and epoxy, or merger risk would you want to stress test first?
On Simply Wall St, a Narrative is an investor's thesis written down: the reasoning, plus the numbers it rests on. Run those numbers and you get an estimated Fair Value.
Olin has already moved. See which of 29 high quality undervalued stocks still trade below our estimates.
The Two Stories Investors Had To Weigh On Olin
The shares cost US$24.06 at the start of the period, and Olin sat between two very different stories about its future.
The bullish Narrative put Fair Value at US$31 and leaned on expansion in PVC and specialty epoxies tied to global infrastructure and electrification themes, alongside cost reductions that analysts assumed would feed into higher free cash flow.
The bearish view set Fair Value at US$20 and focused on decarbonization pressure, where tightening sustainability rules and legacy environmental liabilities were expected to squeeze profitability and constrain future investment capacity.
What The Results Changed For The Olin Story
The most important fact for Olin in this window was that the firm still reported losses. Net income excluding extra items moved from a loss of US$1.3 million in Q2 2025 to a deeper loss of US$13.3 million in Q2 2026, while revenue slipped from US$1.76b to US$1.74b and net margin weakened from -0.1% to -0.8%. That record challenged the optimistic profitability path and supported the cautious case.
The lesson to carry elsewhere is simple. When a thesis hangs on margin repair, keep checking whether net margin, not just sales or narrative, is moving toward the target.
What Olin’s Lower Price Asks You To Believe Now
Olin trades at US$15.94 today, down sharply from a year ago, while the selected bullish Narrative’s Fair Value sits above that level based on its own assumptions about the business.
That Narrative now leans on portfolio reshaping, cost programs and the Huntsman merger. A buyer today would need to believe Olin can actually turn those planned synergies and structural savings into durable earnings despite higher leverage and execution risk.
"A key focus is successful execution of Beyond250 and the Huntsman integration to convert identified cost and integration synergies into durable earnings, while managing higher leverage and operational risks."
One Narrative has put a figure on that disagreement. → See the Narrative with its higher Fair Value, assumptions and all
Before The Next Story Makes Headlines
The next headline does not have to be where your research begins. Go straight to the companies and see whether a contrarian opportunity could be taking shape.
- Company 1 - 22% below our estimate - embeds AI agents into existing workplace tools for knowledge workers.
- Company 2 - 32% below our estimate - signs rapid-turnaround subsea tieback work using modular, reusable infrastructure designs.
- Company 3 - 37% below our estimate - tackles technically complex safety disputes as authorities scrutinize AI-linked decision processes.
Those are three of them. See the full list of 24 financially solid companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com