
PROG Holdings (PRG) Could Be 43% Undervalued On Credit Quality Questions
Short Seller Report Puts PROG Holdings' Credit Quality Under the Microscope
Jehoshaphat Research’s recent report on PROG Holdings (PRG) zeroes in on credit quality, alleging looser lending standards, optimistic loss assumptions, and raising questions about how revenue guidance changes were explained.
The short seller points to past-due loans at PROG’s Four and MoneyApp portfolio and to a cut in Purchasing Power’s revenue guidance, arguing these issues matter more than recent commentary on updated earnings expectations.
PROG Holdings’ share price has retreated sharply in recent months, with a 30-day share price return down 17.4% and a 90-day share price return down 32.5%. The 1-year total shareholder return is roughly flat at 0.5% and the 3-year total shareholder return is about 3.8%, suggesting recent credit concerns and short seller scrutiny have cooled momentum after steadier longer term performance.
Scan how other credit-focused lenders stack up on underwriting discipline and recent returns by comparing PROG Holdings with a curated list of 31 resilient stocks with low risk scores.After a one third slide in three months, PROG Holdings now trades on far cooler sentiment while analyst targets and reported earnings still point higher, so does that skew the risk reward toward patient buyers or caution.
Most Popular Narrative: 43% Undervalued
Against a last close of $30.52, the most followed narrative for PROG Holdings pegs fair value at about $53.43. This puts the short seller report up against a thesis built on a much broader earnings engine than just one credit cycle.
Ongoing traction in diversifying revenue through additional platforms in the ecosystem, including Purchasing Power’s rising GMV and expanding adjusted EBITDA contribution and MoneyApp within the broader suite, supports a larger consolidated profit base that is not solely tied to Progressive Leasing earnings.
See why 5 investors see PROG Holdings as 43% undervalued.
Result: Fair Value of $53.43 (UNDERVALUED)
Still, the bullish PROG Holdings narrative can crack if credit losses track closer to the short seller’s concerns or if BNPL growth in Four slows materially.
Find out about the key risks to this PROG Holdings narrative.
Another View: PROG Holdings On Earnings Multiples
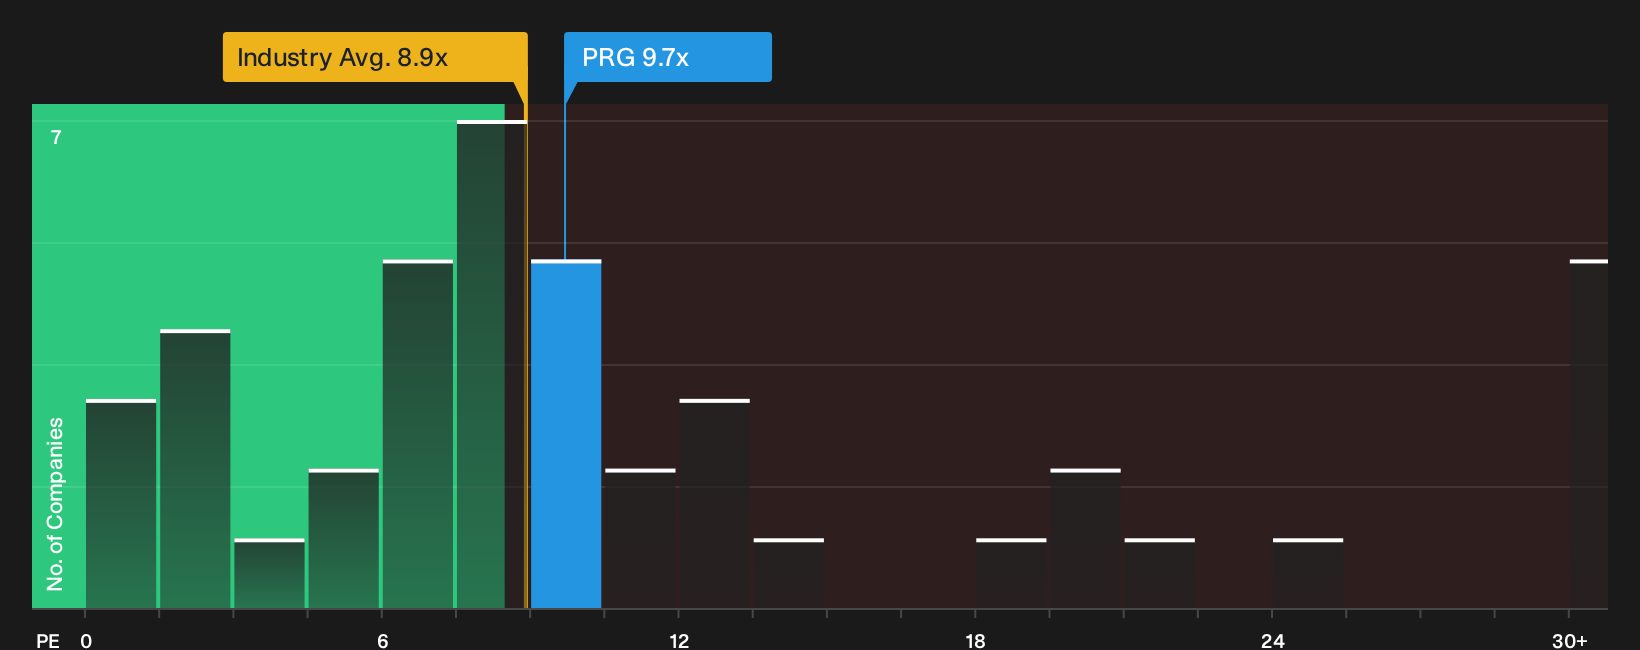
Against that fair value of $53.43, PROG Holdings trades on a P/E of 9.7x. The broader US Consumer Finance group sits around 8.9x, while the fair ratio for PRG is estimated at 12.4x. That mix of slight premium to sector but discount to fair ratio points to a valuation that could either compress toward peers or stretch toward the fair ratio if sentiment shifts. Which side of that gap do you think is more likely?
For a closer look at how the current P/E stacks up, including peer comparisons and the fair ratio, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Plenty in this PROG Holdings story pulls in opposite directions, so move quickly to review the full picture, stress test the numbers, and weigh both the 3 key rewards and 5 important warning signs
Looking For More Investment Ideas Beyond PROG Holdings?
Do not stop at PROG Holdings. Broaden your watchlist with fresh ideas so you are not relying on a single story when markets shift again.
- Target resilient balance sheets and steady fundamentals by scanning the list of solid balance sheet and fundamentals (25 results) that can help anchor a more durable portfolio core.
- Hunt for pricing gaps by reviewing the 29 high quality undervalued stocks that combine financial quality with market skepticism that may not last forever.
- Stack potential income streams by checking out the 8 dividend fortresses that focus on higher yields with an eye on sustainability.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com