
Debt Refinance Might Change The Case For Investing In Burke And Herbert Financial Services Stock
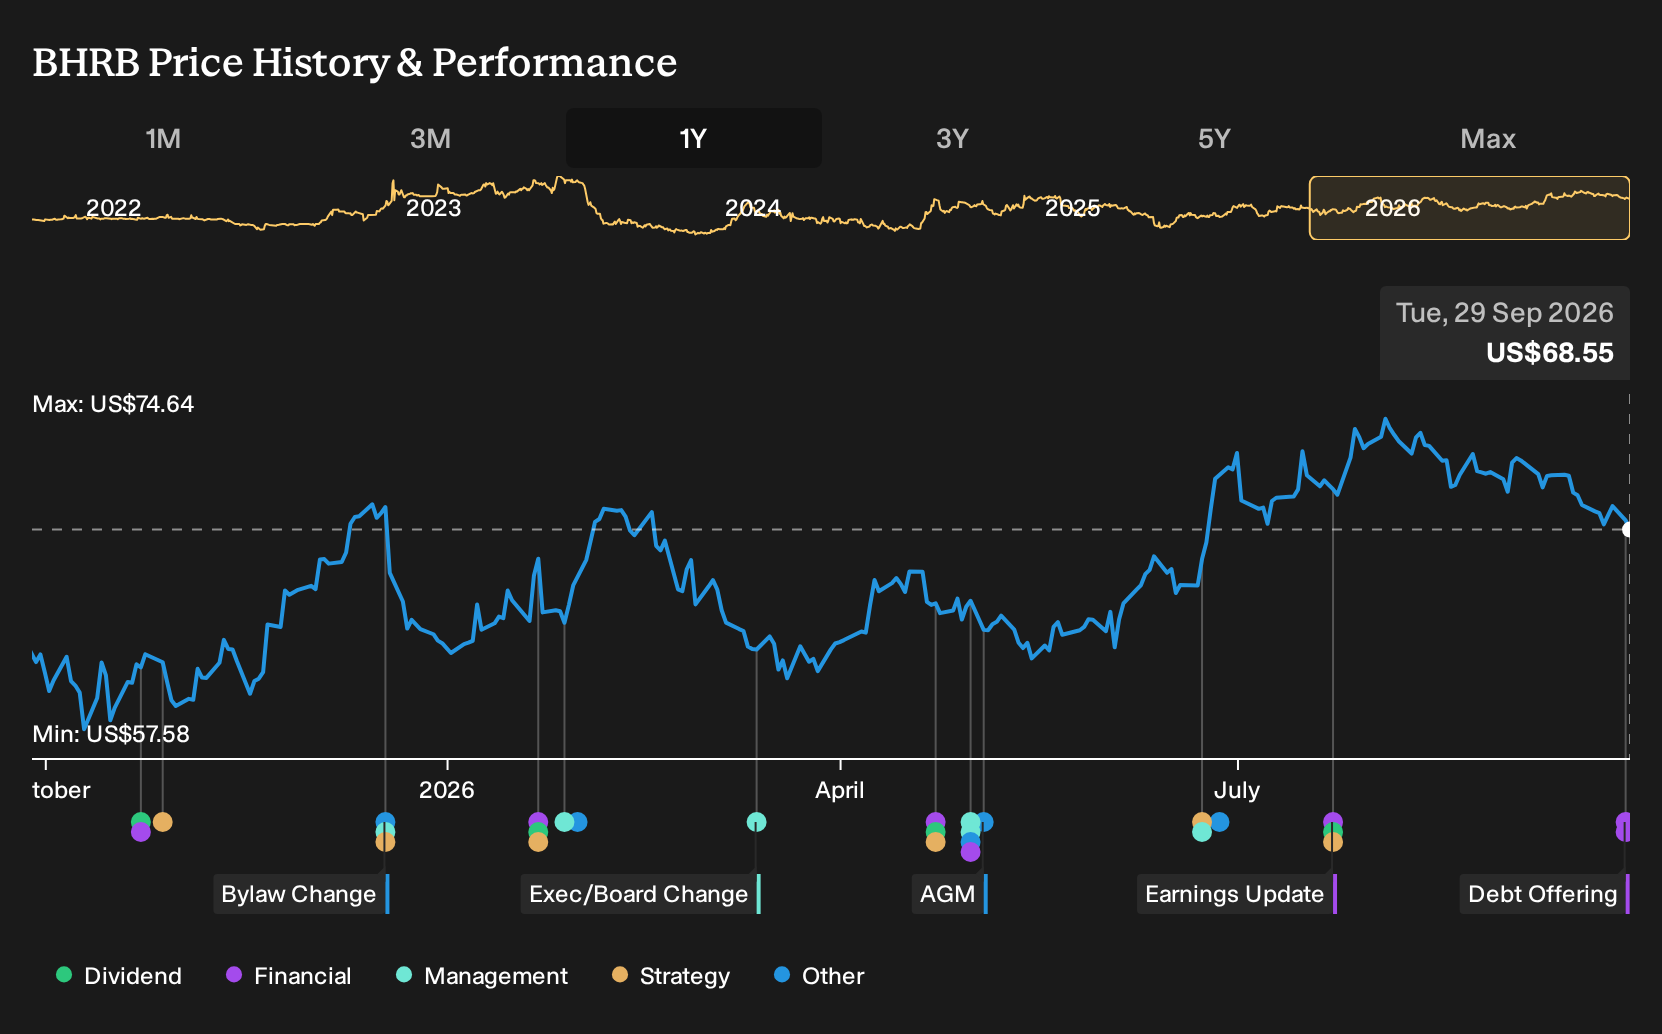
- Burke & Herbert Financial Services has completed a $100 million public issuance of fixed to floating rate subordinated notes due October 1, 2036, with a variable coupon and a callable, unsecured structure.
- The refinancing plan replaces several older, higher cost subordinated obligations with this single issue, targeting lower interest expense and a stronger regulatory capital position for Burke & Herbert Financial Services.
- We will now look at how Burke & Herbert Financial Services' investment narrative could shift given this $100 million subordinated debt refinancing.
Compare Burke & Herbert Financial Services' refinancing move with other balance-sheet focused opportunities by scanning our hand picked list of solid balance sheet and fundamentals (25 results).
What Is Burke & Herbert Financial Services' Investment Narrative?
To own Burke & Herbert Financial Services, you need to believe in a fairly straightforward banking story. A community focused institution with US$360.1m in revenue, a 26.7% net margin and a long operating history tries to balance growth, credit discipline and capital. The refinancing of US$100m into fixed to floating subordinated notes fits that script. Management is swapping several older, higher cost obligations for a single, longer dated instrument, which can support regulatory ratios and potentially free up earnings capacity if interest expense trends prove favourable.
The near term swing factors remain execution in core lending, credit quality and deposit behaviour rather than this one refinancing. Earnings have grown strongly over five years, but the last twelve months included a US$34.7m one off loss and profit contraction. Forecasts still point to rapid profit and revenue expansion, yet recent share performance has softened, returns on equity are modest at 8.1% and the allowance for bad loans sits at 99% of problem exposures. Shareholders also have to weigh recent insider selling and prior dilution against a 3.21% dividend yield and a P/E of 14.4x that sits below the wider US market but above many bank peers.
Even so, there is a sharper edge to the Burke & Herbert Financial Services story once you factor in ...
There's only one way to know the right time to buy, sell or hold Burke & Herbert Financial Services. Head to Simply Wall St's company report for the latest analysis of Burke & Herbert Financial Services's Fair Value.
Form Your Own Verdict
Disagree with this assessment? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Burke & Herbert Financial Services research is our analysis highlighting 3 key rewards and 4 important warning signs that could impact your investment decision.
- See our latest analysis for Burke & Herbert Financial Services. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Burke & Herbert Financial Services' overall financial health at a glance.
Looking For More Investment Ideas Beyond Burke & Herbert Financial Services?
If the refinancing story at Burke & Herbert Financial Services has you thinking more broadly about portfolio construction, it can help to line it up against other businesses with clear balance sheet, income and dividend profiles. The Simply Wall St Screener is built for exactly that kind of side by side comparison, so you can pressure test your thesis against a wider universe of listed companies.
Here are a few angles you might want to investigate next using different screener views:
- If capital preservation is high on your list, consider starting with companies that show relatively resilient profiles by reviewing 32 resilient stocks with low risk scores in the screener.
- If you are hunting for potentially mispriced opportunities with strong fundamentals, scan the market through 31 high quality undervalued stocks and see which businesses warrant a deeper look.
- If reliable income is a priority for your plan, focus on cash return potential by filtering for 6 dividend fortresses that might complement your current holdings.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com