
The Bull Case For Griffon (GFF) Could Change Following Revenue Miss and Lowered Guidance—Learn Why
- In its latest quarterly report, Griffon posted revenues of US$613.6 million, reflecting a 5.3% year-on-year decline and missing analysts' expectations, with full-year revenue guidance also falling short.
- This performance underscores a contrast between Griffon's historically strong earnings per share growth and its slower pace of long-term revenue expansion.
- We’ll explore how Griffon's weaker quarterly revenues and lowered guidance could reshape its outlook for home improvement and building products growth.
We've found 19 US stocks that are forecast to pay a dividend yield of over 6% next year. See the full list for free.
Griffon Investment Narrative Recap
To be a Griffon shareholder today, you’d need conviction in the company’s ability to restore demand and profitability in its core home improvement and building products markets despite recent setbacks. The latest revenue miss and reduced guidance are meaningful, as they weaken near-term momentum and reinforce that consumer demand is Griffon’s most immediate catalyst and biggest risk, the sharp drop in segment sales reflects ongoing vulnerability to cyclical spending, making consumer recovery central to forward-looking optimism.
Among Griffon’s latest announcements, the US$244 million impairment related to the Hunter Fan acquisition stands out. This one-off charge not only weighed heavily on recent earnings but also reinforces how sensitive Griffon remains to underperforming assets in downturns. For investors tracking catalysts, it puts even more focus on how successfully Griffon can realign its product mix and recover volumes in its consumer-facing segments.
By contrast, it helps to remember that Griffon's future margin improvement and earnings recovery also depend on whether...
Read the full narrative on Griffon (it's free!)
Griffon's outlook projects $2.7 billion in revenue and $517.0 million in earnings by 2028. This is based on a 1.8% annual revenue growth rate and an increase in earnings of $447.0 million from the current $70.0 million.
Uncover how Griffon's forecasts yield a $100.29 fair value, a 29% upside to its current price.
Exploring Other Perspectives
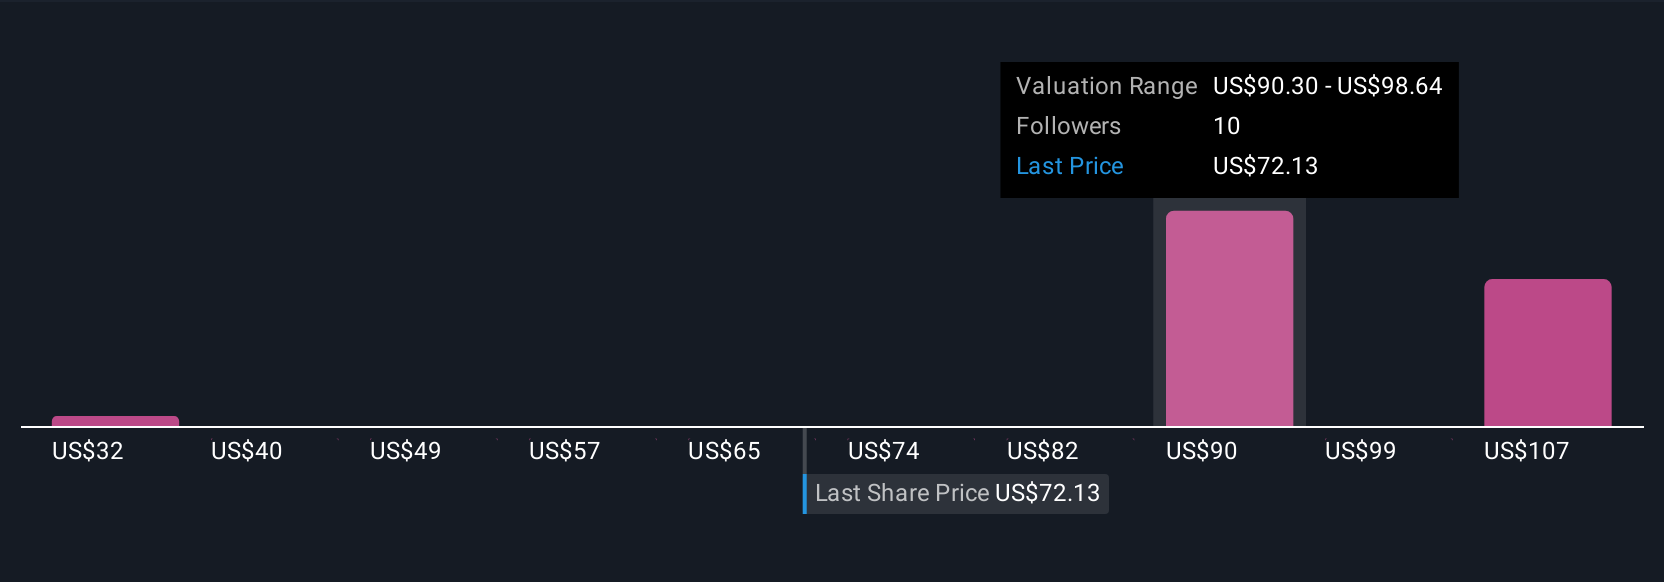
Four members of the Simply Wall St Community placed Griffon’s fair value estimates between US$31.88 and US$114.99, reflecting widely different views. With recent revenue pressure putting consumer demand in the spotlight, see how your outlook compares with those varied perspectives.
Explore 4 other fair value estimates on Griffon - why the stock might be worth less than half the current price!
Build Your Own Griffon Narrative
Disagree with existing narratives? Create your own in under 3 minutes - extraordinary investment returns rarely come from following the herd.
- A great starting point for your Griffon research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- Our free Griffon research report provides a comprehensive fundamental analysis summarized in a single visual - the Snowflake - making it easy to evaluate Griffon's overall financial health at a glance.
Want Some Alternatives?
Our daily scans reveal stocks with breakout potential. Don't miss this chance:
- The end of cancer? These 28 emerging AI stocks are developing tech that will allow early identification of life changing diseases like cancer and Alzheimer's.
- Trump's oil boom is here - pipelines are primed to profit. Discover the 22 US stocks riding the wave.
- These 13 companies survived and thrived after COVID and have the right ingredients to survive Trump's tariffs. Discover why before your portfolio feels the trade war pinch.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com