
St. Galler Kantonalbank (SWX:SGKN): Evaluating Valuation After Recent Period of Share Price Stability
St. Galler Kantonalbank (SWX:SGKN) has seen its share price remain stable over the past day, with a modest gain of 2% in the past week. Investors have noticed that the stock is holding steady after recent movements.
See our latest analysis for St. Galler Kantonalbank.
While St. Galler Kantonalbank’s share price has been fairly steady in recent months, its one-year total shareholder return of 27% shows meaningful longer-term gains. This suggests investor confidence is building, even as short-term momentum remains modest.
If you want to see which other companies are capturing investor attention, now could be the perfect time to uncover fast growing stocks with high insider ownership
With steady gains and a notable intrinsic discount, investors may be wondering whether the market has fully recognized St. Galler Kantonalbank’s growth potential or if there is still an attractive buying opportunity here.
Price-to-Earnings of 13.2: Is it justified?
St. Galler Kantonalbank's latest closing price of CHF505 puts its Price-to-Earnings (P/E) ratio at 13.2, making it appear attractively valued compared to its peer group average.
The P/E ratio compares a company's current share price to its per-share earnings. This helps investors assess how much the market is willing to pay for expected profits. In the banking sector, the P/E ratio is a common measure to gauge value and growth expectations.
With St. Galler Kantonalbank's P/E of 13.2 versus a peer average of 16, the stock is trading at a noticeable discount. This suggests the market may be underestimating the company’s earnings potential or rewarding it less generously relative to similar banks. Investors looking for value in the Swiss banking sector may see this as a positive sign.
However, compared to the broader European banks industry, where the average P/E is 9.9, St. Galler Kantonalbank is trading at a premium. This reflects the market's view of its financial health or growth profile relative to European peers.
See what the numbers say about this price — find out in our valuation breakdown.
Result: Price-to-Earnings of 13.2 (UNDERVALUED)
However, slower revenue growth or sector-wide sentiment shifts could pose risks to St. Galler Kantonalbank’s current valuation outlook and investor confidence.
Find out about the key risks to this St. Galler Kantonalbank narrative.
Another View: Discounted Cash Flow Model
While the stock appears undervalued based on its price-to-earnings ratio, the SWS DCF model provides a different perspective. According to our estimate, St. Galler Kantonalbank is trading roughly 26% below its fair value. Does this strengthen the idea of a bargain, or is the gap a signal for caution?
Look into how the SWS DCF model arrives at its fair value.
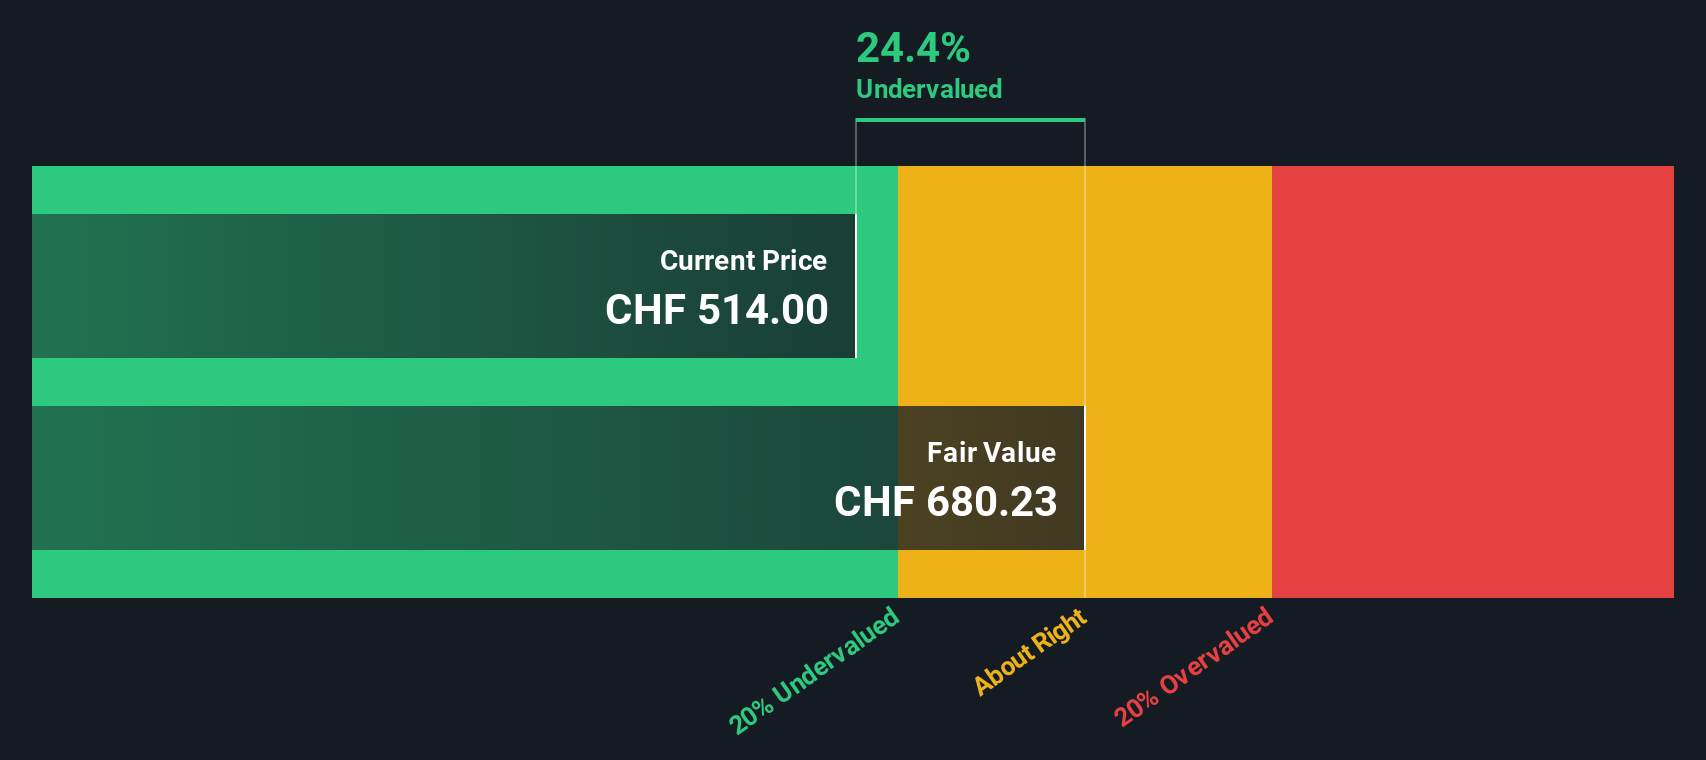
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out St. Galler Kantonalbank for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover undervalued stocks based on their cash flows. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Build Your Own St. Galler Kantonalbank Narrative
If you’d rather form your own view or dig deeper into the numbers, you can piece together your own story in just a few minutes, and Do it your way
A great starting point for your St. Galler Kantonalbank research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
Looking for more investment ideas?
Don’t limit your strategy to a single stock when so many compelling opportunities are just a click away using the Simply Wall Street Screener.
- Tap into high yield potential by checking out these 19 dividend stocks with yields > 3%, which offers yields above 3% and stable income streams.
- Spot tomorrow’s trendsetters and fuel your portfolio with these 24 AI penny stocks, companies harnessing artificial intelligence to transform industries.
- Access value-focused companies by reviewing these 910 undervalued stocks based on cash flows, a selection of stocks trading below their intrinsic worth based on cash flows.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com