
Is LAMEDITECH (KOSDAQ:462510) Using Debt Sensibly?
Legendary fund manager Li Lu (who Charlie Munger backed) once said, 'The biggest investment risk is not the volatility of prices, but whether you will suffer a permanent loss of capital.' When we think about how risky a company is, we always like to look at its use of debt, since debt overload can lead to ruin. We note that LAMEDITECH Co., Ltd. (KOSDAQ:462510) does have debt on its balance sheet. But should shareholders be worried about its use of debt?
When Is Debt Dangerous?
Debt and other liabilities become risky for a business when it cannot easily fulfill those obligations, either with free cash flow or by raising capital at an attractive price. In the worst case scenario, a company can go bankrupt if it cannot pay its creditors. However, a more usual (but still expensive) situation is where a company must dilute shareholders at a cheap share price simply to get debt under control. By replacing dilution, though, debt can be an extremely good tool for businesses that need capital to invest in growth at high rates of return. When we examine debt levels, we first consider both cash and debt levels, together.
What Is LAMEDITECH's Debt?
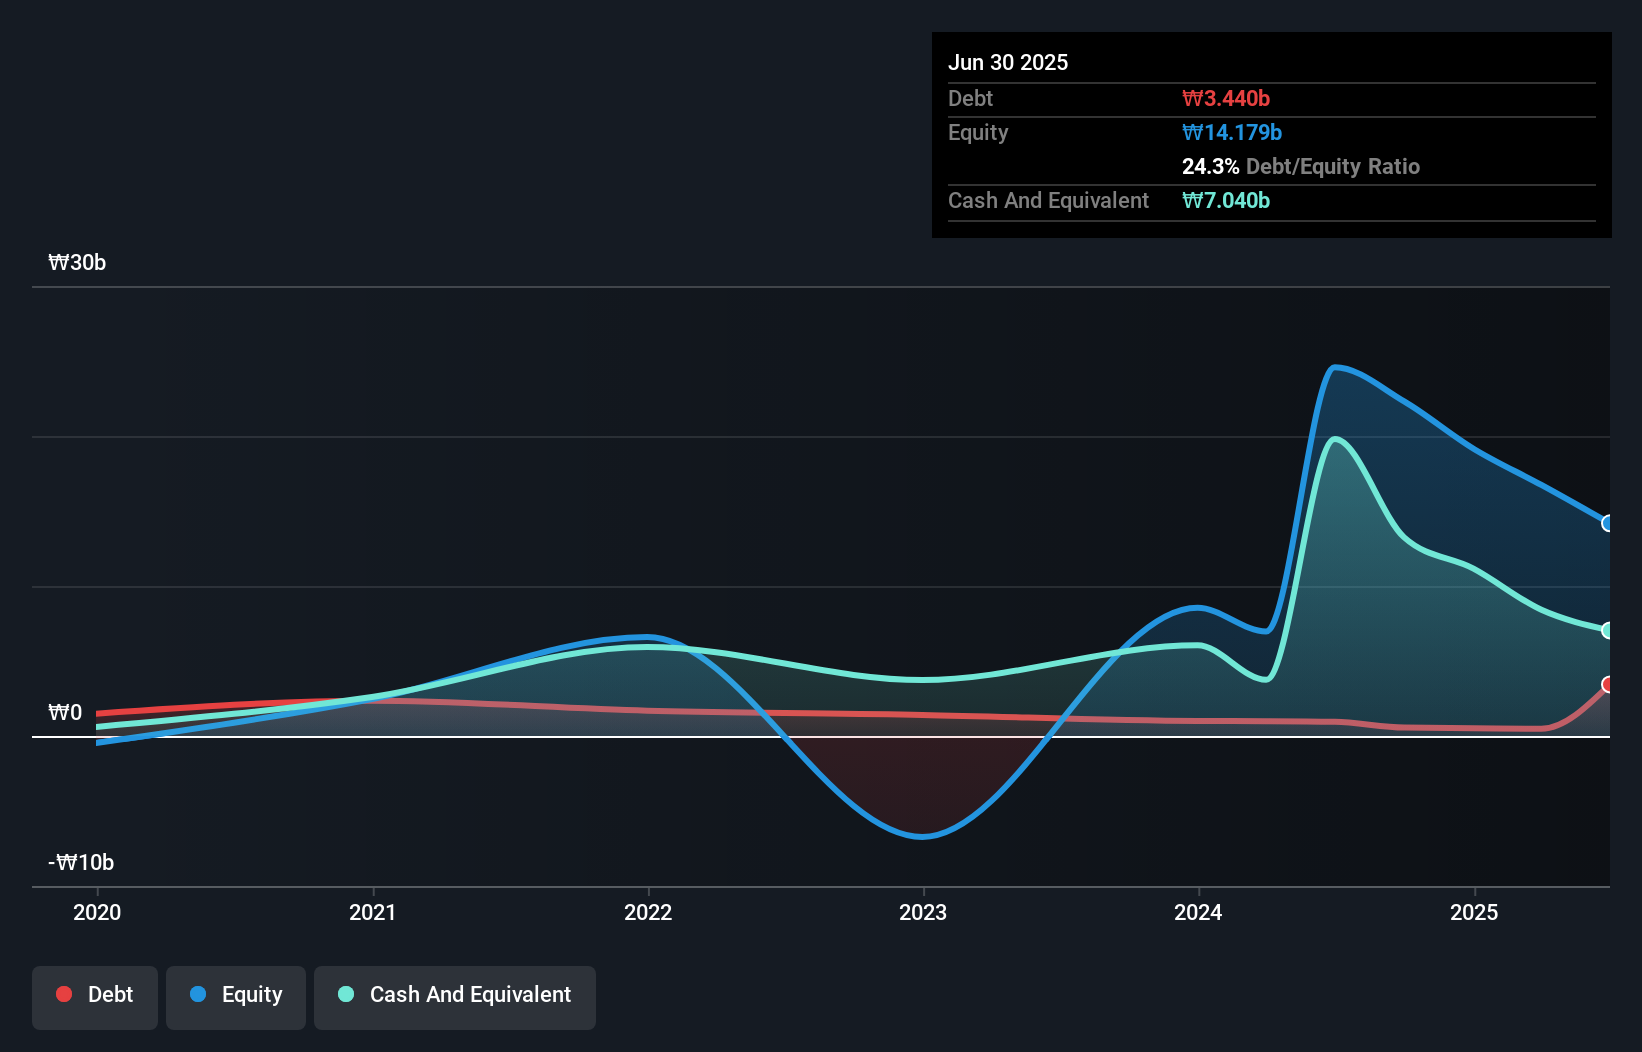
The image below, which you can click on for greater detail, shows that at June 2025 LAMEDITECH had debt of ₩3.44b, up from ₩943.0m in one year. But on the other hand it also has ₩7.04b in cash, leading to a ₩3.60b net cash position.
A Look At LAMEDITECH's Liabilities
We can see from the most recent balance sheet that LAMEDITECH had liabilities of ₩1.17b falling due within a year, and liabilities of ₩5.51b due beyond that. Offsetting these obligations, it had cash of ₩7.04b as well as receivables valued at ₩1.39b due within 12 months. So it actually has ₩1.75b more liquid assets than total liabilities.
This short term liquidity is a sign that LAMEDITECH could probably pay off its debt with ease, as its balance sheet is far from stretched. Succinctly put, LAMEDITECH boasts net cash, so it's fair to say it does not have a heavy debt load! The balance sheet is clearly the area to focus on when you are analysing debt. But you can't view debt in total isolation; since LAMEDITECH will need earnings to service that debt. So if you're keen to discover more about its earnings, it might be worth checking out this graph of its long term earnings trend.
Check out our latest analysis for LAMEDITECH
In the last year LAMEDITECH wasn't profitable at an EBIT level, but managed to grow its revenue by 74%, to ₩7.3b. With any luck the company will be able to grow its way to profitability.
So How Risky Is LAMEDITECH?
We have no doubt that loss making companies are, in general, riskier than profitable ones. And in the last year LAMEDITECH had an earnings before interest and tax (EBIT) loss, truth be told. Indeed, in that time it burnt through ₩15b of cash and made a loss of ₩10b. With only ₩3.60b on the balance sheet, it would appear that its going to need to raise capital again soon. LAMEDITECH's revenue growth shone bright over the last year, so it may well be in a position to turn a profit in due course. By investing before those profits, shareholders take on more risk in the hope of bigger rewards. The balance sheet is clearly the area to focus on when you are analysing debt. But ultimately, every company can contain risks that exist outside of the balance sheet. Case in point: We've spotted 4 warning signs for LAMEDITECH you should be aware of, and 2 of them are a bit unpleasant.
At the end of the day, it's often better to focus on companies that are free from net debt. You can access our special list of such companies (all with a track record of profit growth). It's free.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team (at) simplywallst.com.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.