'%3e %3cpath d='M41.7832962%2c0 C41.9459106%2c0 42.0882746%2c0.0866854658 42.1666825%2c0.216359069 C43.8289923%2c2.66540836 44.7676281%2c5.46271319 44.7676281%2c8.43208061 C44.7676281%2c18.1345746 34.7460532%2c26 22.383814%2c26 C10.0215749%2c26 0%2c18.1345746 0%2c8.43208061 C0%2c5.46716016 0.935826425%2c2.67378733 2.58829888%2c0.223985685 C2.67109477%2c0.0916264068 2.81687473%2c0 2.9840593%2c0 C3.23130408%2c0 3.43173558%2c0.200393004 3.43173558%2c0.447590303 C3.43173558%2c0.475056669 3.42926112%2c0.501945205 3.42452292%2c0.528045226 L3.41810883%2c0.550292077 C3.37800671%2c0.861741908 3.3575721%2c1.17661276 3.3575721%2c1.49443092 C3.3575721%2c7.98336 11.2132389%2c12.5742305 22.383814%2c12.5742305 C33.5543891%2c12.5742305 41.410056%2c7.98336 41.410056%2c1.49443092 C41.410056%2c1.17865223 41.3898828%2c0.865783153 41.3502888%2c0.556288325 C41.3402868%2c0.521941442 41.3356199%2c0.48531078 41.3356199%2c0.447590303 C41.3356199%2c0.200393004 41.5360514%2c0 41.7832962%2c0 Z' id='logo%e5%a4%87%e4%bb%bd-6' fill='white'%3e%3c/path%3e %3cpath d='M74.6899231%2c3.74404927 C75.2411227%2c3.74404927 75.7734299%2c3.66184338 76.2756219%2c3.50883715 L73.8159676%2c20.8666902 C73.5770593%2c22.5662954 72.8072434%2c23.0518969 71.4268838%2c23.0518969 L69.9934336%2c23.0518969 C68.7988917%2c23.0518969 68.1618027%2c22.458384 67.7901674%2c20.893668 L65.6930827%2c11.9909739 C65.639992%2c11.7481731 65.639992%2c11.6942174 65.5338105%2c11.6942174 C65.427629%2c11.6942174 65.4010836%2c11.7481731 65.3479929%2c11.9909739 L63.2509082%2c20.893668 C62.8792729%2c22.458384 62.2421839%2c23.0518969 61.047642%2c23.0518969 L59.6141918%2c23.0518969 C58.2338322%2c23.0518969 57.4640163%2c22.5662954 57.225108%2c20.8666902 L54.7463723%2c3.37406084 C55.3593498%2c3.61307396 56.0249975%2c3.74404927 56.7207458%2c3.74404927 C57.3314263%2c3.74404927 57.918917%2c3.64314414 58.4679557%2c3.4568446 L60.3574623%2c19.3829078 C60.3840076%2c19.6257086 60.3840076%2c19.7875757 60.4901891%2c19.7875757 C60.5963706%2c19.7875757 60.5963706%2c19.6257086 60.6494614%2c19.3829078 L62.9323637%2c9.91367858 C63.0916359%2c9.26620991 63.4632712%2c8.69967483 64.6047223%2c8.69967483 L66.4363532%2c8.69967483 C67.5778044%2c8.69967483 67.9494397%2c9.26620991 68.1087119%2c9.91367858 L70.3916142%2c19.3829078 C70.4447049%2c19.6257086 70.4447049%2c19.7875757 70.5508864%2c19.7875757 C70.6570679%2c19.7875757 70.6570679%2c19.6257086 70.6836133%2c19.3829078 L72.5891207%2c3.32292288 C73.2365902%2c3.59432921 73.9460524%2c3.74404927 74.6899231%2c3.74404927 Z' id='Combined-Shape' fill='white'%3e%3c/path%3e %3cpath d='M84.5933901%2c7.43171536 C88.6813779%2c7.43171536 90.9111894%2c10.2643908 90.9111894%2c14.2840921 L90.9111894%2c15.7948523 C90.9111894%2c16.2264981 90.7519172%2c16.4692988 90.3802819%2c16.4692988 L81.7264895%2c16.4692988 L81.7264895%2c16.5502324 C81.7264895%2c18.1149484 82.3635785%2c19.9764208 84.9119346%2c19.9764208 C86.849747%2c19.9764208 88.6813779%2c19.8145536 89.7962837%2c19.7066422 L89.8759198%2c19.7066422 C90.1413735%2c19.7066422 90.3537366%2c19.8415315 90.3537366%2c20.1113101 L90.3537366%2c21.8918489 C90.3537366%2c22.3234947 90.2741004%2c22.5123397 89.7962837%2c22.5932733 C88.0708343%2c22.9170076 87.0355646%2c23.0518969 84.6464808%2c23.0518969 C81.9919433%2c23.0518969 78.2225%2c21.5950924 78.2225%2c16.2804538 L78.2225%2c14.2840921 C78.2225%2c10.0755457 80.5319476%2c7.43171536 84.5933901%2c7.43171536 Z M84.5933901%2c10.5071915 C82.9475768%2c10.5071915 81.7530349%2c11.6942174 81.7530349%2c13.8254684 L81.7530349%2c13.9333799 L87.3806545%2c13.9333799 L87.3806545%2c13.8254684 C87.3806545%2c11.7211953 86.2392034%2c10.5071915 84.5933901%2c10.5071915 Z' id='Combined-Shape' fill='white'%3e%3c/path%3e %3cpath d='M97.4154906%2c2.98826245 L97.4148064%2c7.62056039 C98.3969853%2c7.48567108 99.3260735%2c7.43171536 99.9631625%2c7.43171536 C104.236968%2c7.43171536 106.307507%2c9.99461216 106.307507%2c14.2031585 L106.307507%2c16.2804538 C106.307507%2c20.4890001 104.236968%2c23.0518969 99.9631625%2c23.0518969 C98.2642584%2c23.0518969 96.2733553%2c22.7821183 94.627542%2c22.3504725 C94.0169984%2c22.1886054 93.9108169%2c22.0267382 93.9108169%2c21.6220703 L93.9098179%2c3.08694115 C94.4185466%2c3.24434375 94.9584615%2c3.32900525 95.5178331%2c3.32900525 C96.184659%2c3.32900525 96.8238351%2c3.20869291 97.4154906%2c2.98826245 Z M99.9631625%2c10.3453244 C99.3260735%2c10.3453244 98.1580769%2c10.4262579 97.4148064%2c10.5341694 L97.4148064%2c19.9494429 C97.9191686%2c20.0573544 99.007529%2c20.1382879 99.9631625%2c20.1382879 C102.246065%2c20.1382879 102.803518%2c18.4926384 102.803518%2c16.2804538 L102.803518%2c14.2031585 C102.803518%2c11.9909739 102.246065%2c10.3453244 99.9631625%2c10.3453244 Z' id='Combined-Shape' fill='white'%3e%3c/path%3e %3cpath d='M111.036668%2c8.72457747 C111.579488%2c8.72457747 112.103987%2c8.64485191 112.599444%2c8.49629404 L112.598761%2c16.5232546 C112.598761%2c19.3289521 113.607485%2c19.9764208 115.147117%2c19.9764208 L115.306389%2c19.9764208 C116.846021%2c19.9764208 117.854746%2c19.3289521 117.854746%2c16.5232546 L117.854207%2c8.4334735 C118.406525%2c8.62226395 118.997939%2c8.72457747 119.612866%2c8.72457747 C120.223332%2c8.72457747 120.810625%2c8.62374317 121.359498%2c8.43756894 L121.358735%2c16.5232546 C121.358735%2c22.4044283 116.872567%2c23.0518969 115.306389%2c23.0518969 L115.060464%2c23.0512514 C113.42215%2c23.0271041 109.094772%2c22.2994073 109.094772%2c16.5232546 L109.094446%2c8.36700801 C109.698522%2c8.59813531 110.353066%2c8.72457747 111.036668%2c8.72457747 Z' id='Combined-Shape' fill='white'%3e%3c/path%3e %3cpath d='M128.314162%2c3.03790128 L128.313623%2c22.269539 C128.313623%2c22.5662954 128.10126%2c22.836074 127.809261%2c22.836074 L125.340541%2c22.836074 C125.048542%2c22.836074 124.809634%2c22.5662954 124.809634%2c22.269539 L124.809455%2c3.04219481 C125.358161%2c3.22824247 125.945253%2c3.32900525 126.555503%2c3.32900525 C127.17043%2c3.32900525 127.761844%2c3.22669173 128.314162%2c3.03790128 Z' id='Combined-Shape' fill='white'%3e%3c/path%3e %3cpath d='M133.90653%2c3.32900525 C134.473329%2c3.32900525 135.02015%2c3.24208064 135.534793%2c3.08063296 L135.533966%2c22.269539 C135.533966%2c22.5662954 135.321603%2c22.836074 135.029603%2c22.836074 L132.560884%2c22.836074 C132.268884%2c22.836074 132.029976%2c22.5662954 132.029976%2c22.269539 L132.029909%2c2.99605058 C132.615669%2c3.21152525 133.2476%2c3.32900525 133.90653%2c3.32900525 Z' id='Combined-Shape' fill='white'%3e%3c/path%3e %3c/g%3e %3c/g%3e %3c/g%3e%3c/svg%3e)


Every time you sell a stock, ETF, or other investment at a profit, the IRS may want a share of your gains—and how much you owe can vary dramatically depending on one simple factor: how long you held the asset. Getting capital gains tax right isn't just about filing season; it shapes when you buy, when you sell, and how you structure your portfolio year-round. This guide walks through the 2025 and 2026 capital gains tax rates, explains the crucial difference between short-term and long-term treatment, and covers legitimate strategies to lower your bill—from tax-loss harvesting to smart holding-period planning.
Key Takeaways
Capital gains tax applies when you sell a capital asset—such as stocks, bonds, real estate, or cryptocurrency—for more than its adjusted cost basis (IRS Topic No. 409).
Short-term capital gains (assets held one year or less) are taxed as ordinary income at rates up to 37%.
Long-term capital gains (assets held more than one year) are taxed at 0%, 15%, or 20%, depending on taxable income and filing status.
High earners may owe an additional 3.8% Net Investment Income Tax (NIIT) on top of standard capital gains tax rates.
Capital losses can offset capital gains dollar-for-dollar, and up to $3,000 of net losses can offset ordinary income each year, with any excess carried forward.
This article contains sponsored references to Webull, a US brokerage platform; see disclosure above.
Capital gains tax is one of the most common tax questions long-term investors and active traders ask, and the answer depends heavily on two factors: how long you held the asset and your overall taxable income. Below, we walk through exactly how the IRS defines and calculates capital gains, current rate tables for 2025 and 2026, and practical steps for managing your tax liability throughout the year.
Part 1. What Is Capital Gains Tax and How Does It Work?
Capital gains tax is a federal tax on the profit realized from selling a capital asset. According to the IRS, almost everything you own and use for personal or investment purposes—including a home, household furnishings, stocks, or bonds—qualifies as a capital asset (IRS Topic No. 409). When you sell that asset, the difference between your adjusted cost basis and the sale price determines whether you have a capital gain or a capital loss.
1.1 Capital Gain vs. Capital Loss: Definitions
Capital gain: The profit you realize when you sell a capital asset for more than your adjusted cost basis. Cost basis typically includes the original purchase price plus commissions or fees paid at the time of purchase (Charles Schwab).
Capital loss: The amount by which the sale price of an asset falls short of its adjusted cost basis. Losses from the sale of personal-use property are not tax deductible, but losses on investment assets generally are (IRS Topic No. 409).
Realized vs. unrealized gains: A gain is "unrealized" as long as you continue to hold the asset—no tax is owed on paper gains. The gain becomes "realized," and therefore taxable, only in the year you actually sell the asset (Vanguard).
1.2 What Assets Are Subject to Capital Gains Tax?
Capital gains tax can apply to a wide range of assets, including:
Individual stocks and exchange-traded funds (ETFs)
Bonds and mutual funds
Cryptocurrency and NFTs (treated as "property" by the IRS)
Real estate, including investment property
Collectibles such as coins, art, and precious metals
Other personal-use valuables like jewelry
Investors who actively trade stocks or ETFs through an online brokerage account, such as Webull, will most commonly encounter capital gains tax on realized stock and options transactions reported at year-end on Form 1099-B.
1.3 When Do You Owe Capital Gains Tax?
You owe capital gains tax for the tax year in which the gain is realized—meaning the year you actually sell or otherwise dispose of the asset (Investopedia). If you have a taxable capital gain, you may also be required to make estimated tax payments throughout the year rather than waiting until the annual filing deadline (IRS Topic No. 409).
Part 2. Short-Term vs. Long-Term Capital Gains Tax Rates (2025–2026)
The single biggest factor influencing your capital gains tax bill is your holding period. The IRS draws a clear line at the one-year mark.
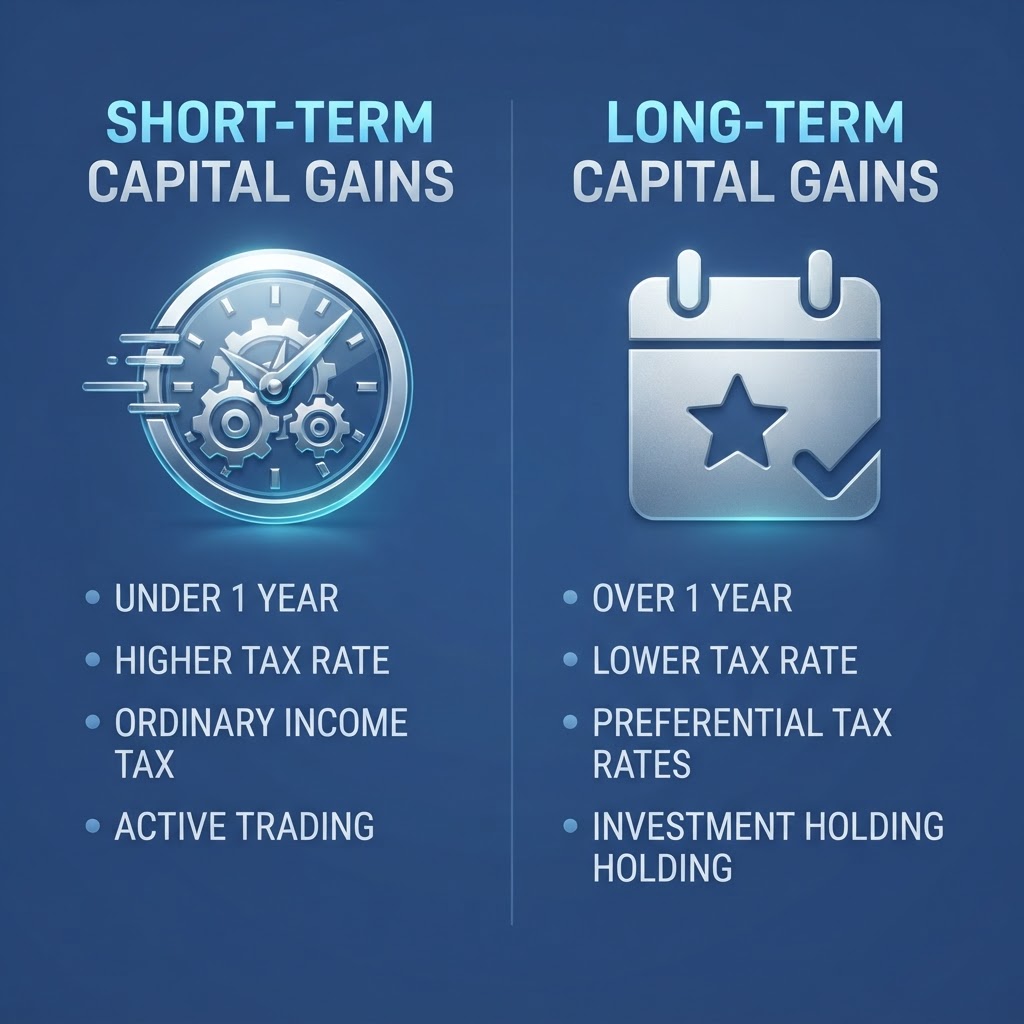
2.1 Short-Term Capital Gains: Held One Year or Less
A short-term capital gain or loss results from selling an asset you held for one year or less. Net short-term capital gains are taxed as ordinary income at your regular graduated federal tax rates—currently ranging from 10% up to 37% (IRS Topic No. 409; Forbes Advisor).
2026 Short-Term Capital Gains Tax Rates (Ordinary Income Brackets)
Tax Rate | Single Filer | Married Filing Jointly | Head of Household |
|---|---|---|---|
10% | $0 – $12,400 | $0 – $24,800 | $0 – $17,700 |
12% | $12,401 – $50,400 | $24,801 – $100,800 | $17,701 – $67,450 |
22% | $50,401 – $105,700 | $100,801 – $211,400 | $67,451 – $105,700 |
24% | $105,701 – $201,775 | $211,401 – $403,550 | $105,701 – $201,750 |
32% | $201,776 – $256,225 | $403,551 – $512,450 | $201,751 – $256,200 |
35% | $256,226 – $640,600 | $512,451 – $768,700 | $256,201 – $640,600 |
37% | $640,601+ | $768,701+ | $640,601+ |
2.2 Long-Term Capital Gains: Held More Than One Year
A long-term capital gain or loss applies to assets held for more than one year. A lower long-term capital gains tax rate may apply if your net long-term capital gain exceeds your net short-term capital loss for the year (IRS Topic No. 409). Most taxpayers pay no more than 15% on long-term gains (NerdWallet).
2025 Long-Term Capital Gains Tax Rates
Rate | Single | Married Filing Separately | Married Filing Jointly | Head of Household |
|---|---|---|---|---|
0% | ≤ $48,350 | ≤ $48,350 | ≤ $96,700 | ≤ $64,750 |
15% | $48,351 – $533,400 | $48,351 – $300,000 | $96,701 – $600,050 | $64,751 – $566,700 |
20% | > $533,400 | > $300,000 | > $600,050 | > $566,700 |
2026 Long-Term Capital Gains Tax Rates
Rate | Single | Married Filing Separately | Married Filing Jointly | Head of Household |
|---|---|---|---|---|
0% | ≤ $49,450 | ≤ $49,450 | ≤ $98,900 | ≤ $66,200 |
15% | $49,451 – $545,500 | $49,451 – $306,850 | $98,901 – $613,700 | $66,201 – $579,600 |
20% | > $545,500 | > $306,850 | > $613,700 | > $579,600 |
Sources: IRS Topic No. 409; Investopedia; Forbes Advisor; NerdWallet
2.3 Special Capital Gains Tax Rates Above 20%
Certain assets are taxed at higher long-term capital gains rates than the standard 0%/15%/20% brackets:
28% rate — Net capital gains from selling collectibles such as coins, art, antiques, and precious metals (IRS Topic No. 409; Charles Schwab).
28% rate — Taxable gain from selling Section 1202 qualified small business stock (QSBS) above the exclusion amount (IRS Topic No. 409; Carta).
25% rate — Unrecaptured Section 1250 gain from selling depreciated real property (IRS Topic No. 409; Investopedia).
Section 1256 contracts (futures, options on futures, broad-based index options) receive blended treatment: 60% of gains taxed at long-term rates and 40% at ordinary income rates, regardless of actual holding period.
Part 3. Net Investment Income Tax (NIIT) and Capital Losses
Beyond standard capital gains tax rates, two additional rules can significantly affect your total tax bill: the Net Investment Income Tax for high earners, and the treatment of capital losses.
3.1 The 3.8% Net Investment Income Tax (NIIT)
Individuals with significant investment income may also be subject to the Net Investment Income Tax in addition to standard capital gains tax rates (IRS Topic No. 409). The NIIT adds 3.8% on investment income—including capital gains, dividends, interest, and rental income—once modified adjusted gross income (MAGI) exceeds:
Filing Status | MAGI Threshold |
|---|---|
Single / Head of Household | $200,000 |
Married Filing Jointly | $250,000 |
Married Filing Separately | $125,000 |
(Investopedia; Vanguard; Charles Schwab). Unlike the capital gains tax brackets, these NIIT thresholds are not indexed for inflation (Tax Policy Center).
3.2 Capital Loss Deduction Rules
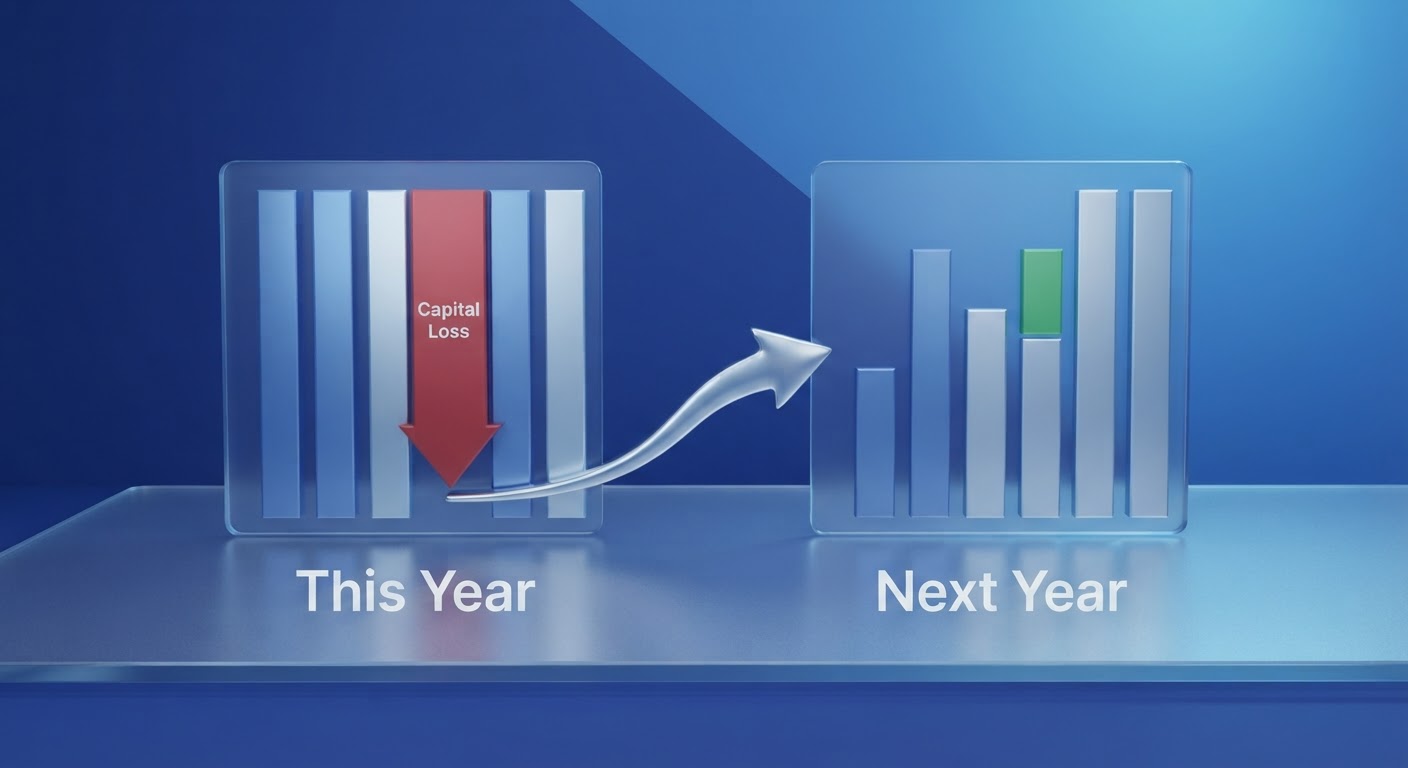
If your capital losses exceed your capital gains for the year, you can deduct the excess against ordinary income—but the deduction is capped. The deductible amount is limited to the lesser of $3,000 ($1,500 if married filing separately) or your total net loss (IRS Topic No. 409; NerdWallet). Any remaining net capital loss beyond that limit carries forward to future tax years indefinitely.
How losses offset gains, step by step:
Separate all sales into short-term and long-term categories.
Net short-term gains against short-term losses, and long-term gains against long-term losses, separately.
If one category shows a net loss and the other a net gain, combine them to find your overall net capital gain or loss.
If the result is a net loss, deduct up to $3,000 ($1,500 married filing separately) against ordinary income.
Carry forward any remaining loss to next year's tax return (Charles Schwab; NerdWallet).
3.3 Wash Sale Rule Considerations
Investors using tax-loss harvesting should be aware of the wash sale rule: repurchasing the same or a substantially identical investment within 30 days of selling it at a loss can disallow the loss for tax purposes. Brokerage tax documents, including those generated through platforms like Webull, typically flag wash sale adjustments on Form 1099-B to help investors report accurately.
Part 4. Reporting, Exclusions, and Special Situations
Capital gains tax isn't limited to stock sales—real estate, inherited assets, and retirement accounts each follow distinct rules.
4.1 How to Report Capital Gains
Capital gains and losses are generally reported on Schedule D (Form 1040), supported by details from Form 8949 (Charles Schwab; Investopedia). Brokerages issue Form 1099-B for individual security sales and Form 1099-DIV for fund distributions that include capital gains (Vanguard). Many self-directed investors download these forms directly from their brokerage account—for example, Webull provides consolidated 1099 tax documents through its app and web platform for eligible account holders.
4.2 The Primary Residence Exclusion
Homeowners selling a primary residence may exclude a portion of the gain from capital gains tax:
Single filers: up to $250,000 excluded
Married filing jointly: up to $500,000 excluded
To qualify, you generally must have owned and lived in the home for at least two of the five years preceding the sale (Investopedia; Charles Schwab; NerdWallet).
4.3 Inherited and Gifted Assets
Inherited assets: Cost basis is "stepped up" to the fair market value on the date of the original owner's death. This means appreciation that occurred before death is generally not subject to capital gains tax, and the asset is treated as long-term regardless of how long the heir actually holds it.
Gifted assets: The recipient generally assumes the original owner's cost basis and holding period, sometimes called "carryover basis" (Charles Schwab).
4.4 Tax-Advantaged Accounts
Capital gains taxes generally do not apply to buy-and-sell activity that occurs inside tax-advantaged accounts such as traditional IRAs, Roth IRAs, 401(k)s, and 529 college savings plans (Charles Schwab). Traditional account withdrawals are typically taxed as ordinary income, while qualified Roth IRA and Roth 401(k) withdrawals made after age 59½ and after the account has been open at least five years are generally tax-free (Investopedia). Investors who want to trade actively without triggering annual capital gains events on each transaction sometimes use an IRA offered through a brokerage; Webull, for instance, offers traditional, Roth, and rollover IRA account types alongside its standard taxable brokerage accounts.
Part 5. Strategies to Reduce or Manage Capital Gains Tax
While capital gains tax cannot be eliminated for realized profits in a taxable account, several widely used, IRS-recognized strategies can help manage the amount owed.
5.1 Practical Steps for Managing Capital Gains Tax
Hold assets longer than one year whenever consistent with your investment goals, to qualify for the lower long-term capital gains tax rates instead of ordinary income rates (Investopedia; Forbes Advisor).
Use tax-loss harvesting by selling underperforming positions to realize losses that offset realized gains elsewhere in your portfolio (NerdWallet; Vanguard).
Track your cost basis carefully, including reinvested dividends and fees, since a higher basis reduces your taxable gain (Investopedia).
Choose your cost-basis method deliberately—options include FIFO, LIFO, specific share identification, or average cost for mutual funds (Investopedia).
Use tax-advantaged retirement accounts for buy-and-hold or actively managed strategies where you want to avoid annual capital gains tax events (Charles Schwab; NerdWallet).
Manage income thresholds by considering whether spreading a large sale across two tax years could keep you in a lower capital gains bracket (Forbes Advisor).
Avoid wash sales by waiting more than 30 days before repurchasing a security you sold at a loss (Investopedia).
5.2 Pros and Cons of Common Capital Gains Tax Strategies
Tax-loss harvesting
Pros: Directly reduces current-year taxable gains; unused losses carry forward indefinitely.
Cons: Requires monitoring the wash sale rule; selling at a loss means realizing that loss permanently unless the position is later repurchased after 30 days.
Holding period extension (buy and hold past one year)
Pros: Access to substantially lower long-term rates (0%/15%/20% vs. up to 37%).
Cons: Market risk continues while holding; not suitable if the investment thesis has changed.
Using tax-advantaged accounts
Pros: No annual capital gains tax drag inside the account; Roth accounts can offer tax-free qualified withdrawals.
Cons: Contribution limits apply; early withdrawals from retirement accounts may trigger penalties.
5.3 Choosing a Brokerage That Supports Tax-Efficient Investing
Because holding periods and cost-basis tracking are central to managing capital gains tax, the brokerage platform you use can meaningfully affect how easily you monitor your tax exposure throughout the year. The following section contains Webull's features relevant to capital gains tax planning:
Real-time position tracking that shows unrealized gains and losses on open positions, helping investors see potential tax impact before selling.
Consolidated 1099 tax forms delivered through the Webull app and web platform, covering 1099-B, 1099-DIV, and related statements for eligible taxable brokerage accounts.
Multiple account types, including individual taxable brokerage accounts and IRAs (traditional, Roth, and rollover), allowing investors to separate tax-deferred or tax-free activity from taxable trading.
Commission-free trading on US-listed stocks and ETFs, which can simplify cost-basis calculations since trading commissions do not need to be added back into basis on every transaction.
Order history and transaction records accessible directly in-platform, which may help investors and their tax preparers reconcile realized short-term and long-term gains at year-end.
Other well-known US brokerages, including Charles Schwab and Vanguard, similarly provide 1099 tax documents and cost-basis reporting tools; account holders should compare specific reporting features, account minimums, and available account types across platforms based on their individual needs. All capital gains tax rules described in this guide apply uniformly under IRS regulations regardless of which registered brokerage an investor uses.
5.4 Platform Safety and Regulatory Oversight
When selecting any US brokerage for taxable or tax-advantaged investing, it's worth confirming basic regulatory safeguards. Brokerages operating in the United States are typically registered with the Securities and Exchange Commission (SEC), are members of the Financial Industry Regulatory Authority (FINRA), and provide Securities Investor Protection Corporation (SIPC) coverage, which protects customer securities and cash up to certain limits in the event of brokerage insolvency (this does not protect against investment losses from market movements). Investors should verify a firm's specific registrations directly through FINRA BrokerCheck or the SEC's investment adviser search tools before opening an account.
Frequently Asked Questions
What is the capital gains tax rate for 2025?
For 2025, long-term capital gains are taxed at 0%, 15%, or 20% depending on taxable income and filing status, while short-term capital gains are taxed as ordinary income at rates up to 37% (IRS Topic No. 409; Forbes Advisor).
How do I avoid paying capital gains tax on stocks?
You cannot legally avoid capital gains tax on a profitable sale in a taxable account, but you can reduce it by holding assets more than one year to qualify for long-term rates, using tax-loss harvesting to offset gains, or trading inside tax-advantaged accounts like IRAs (Charles Schwab; NerdWallet).
Is capital gains tax based on income?
Yes. Long-term capital gains tax brackets (0%, 15%, 20%) are based on your total taxable income and filing status, and short-term capital gains are taxed at your ordinary marginal income tax rate (IRS Topic No. 409; Carta).
Do I pay capital gains tax if I reinvest the money?
Reinvesting proceeds from a sale does not eliminate or defer capital gains tax; the gain is taxable in the year of the sale regardless of what you do with the proceeds afterward (Charles Schwab).
What is the Net Investment Income Tax and who pays it?
The NIIT is an additional 3.8% tax on investment income, including capital gains, for individuals with modified adjusted gross income above $200,000 (single) or $250,000 (married filing jointly) (IRS Topic No. 409; Vanguard).
How much capital loss can I deduct in one year?
You can deduct up to $3,000 in net capital losses against ordinary income per year ($1,500 if married filing separately); any excess loss carries forward to future tax years (IRS Topic No. 409; NerdWallet).
Do capital gains taxes apply inside a Roth IRA or 401(k)?
No. Trades made within tax-advantaged accounts such as Roth IRAs, traditional IRAs, and 401(k)s are not subject to capital gains tax while funds remain in the account; different tax rules apply upon withdrawal (Charles Schwab; Investopedia).
What happens to capital gains tax on inherited stock?
Inherited assets typically receive a "step-up" in cost basis to the fair market value on the date of the original owner's death, and are treated as long-term holdings regardless of how long the heir has actually owned them (Charles Schwab; Tax Policy Center).
The Bottom Line
Capital gains tax depends primarily on your holding period and income level, with long-term rates (0%–20%) generally far more favorable than short-term ordinary income rates. Reviewing your cost basis, holding periods, and available deductions before year-end can help you plan more effectively.
Disclamer
Securities trading is offered to self-directed customers by Webull Financial LLC, member SIPC, FINRA. All investments involve risk, including the possible loss of principal. You should consider your investment objectives carefully before investing. This is not a recommendation, investment advice, or a solicitation for the purchase or sale of a security. Additional info: webull.com/disclosures
Disclosure
Webull Financial LLC, Member SIPC, FINRA. Investing involves risk. More info at webull.com/policy
